

Artificial intelligence (AI) is rapidly changing the cybersecurity landscape, and CrowdStrike Holdings (CRWD) believes the threat is no longer theoretical. CEO George Kurtz recently described the situation as the “genie’s out of the bottle,” underscoring that AI capabilities are now widely available and can be exploited by attackers. CrowdStrike’s 2026 Global Threat Report found that AI-enabled adversary activity surged 89% year-over-year, while the company has also observed attacks moving at machine speed.
Kurtz said AI agents should be secured like privileged users, with strict permissions, temporary credentials, and emergency shutdown capabilities, while humans retain control over critical decisions. He also urged AI companies such as Anthropic and OpenAI to work more closely with cybersecurity firms and independent evaluators to address emerging AI-related threats.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
This growing risk should strengthen the long-term investment case for cybersecurity platforms even as concerns about slowing AI development weigh on parts of the technology market. CrowdStrike has been expanding its AI-focused security capabilities, and the stock may therefore offer an opportunity as the need to protect increasingly autonomous AI systems becomes more pressing.
About CrowdStrike Stock
CrowdStrike is a leading cybersecurity technology company specializing in cloud-native endpoint protection, threat intelligence, and cyberattack response solutions through its subscription-based Falcon platform. Headquartered in Austin, Texas, the firm serves a global customer base with advanced tools designed to prevent breaches and secure cloud workloads, identities, and data in real time. The company commands a market cap of around $248.4 billion, reflecting its stature in the technology sector.
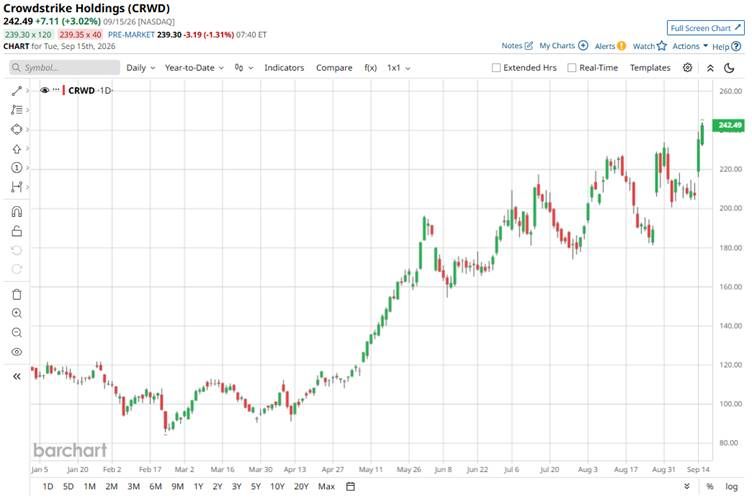
CrowdStrike stock has delivered a sharp rebound in recent trading, with shares climbing to $242.49 as of Sept. 15, after a powerful two-day rally. The stock jumped 13.9% on Sept. 14, its strongest one-day gain in recent history, as growing concerns about the cybersecurity risks associated with increasingly capable AI systems boosted investor interest in security stocks. Shares added another 3% on Sept. 15, extending the rally, while hitting a multi-year high of $243.98 during the session.
The recent move has significantly strengthened CrowdStrike’s broader performance profile. CRWD gained about 15.5% over the past five trading days, while the stock is up roughly 106.9% year-to-date (YTD) and 118.1% over the past 52 weeks.
CrowdStrike is positioning cybersecurity as a critical line of defense in the rapidly expanding AI economy. At Fal.Con 2026, CrowdStrike unveiled new AI-security capabilities, including its Cyber Superintelligence Lab, SafeMind, and Agentic Identity Provider, as it seeks to protect enterprises from increasingly autonomous AI-driven threats.
It is trading at 2,667.61 times forward earnings and 50.09 times sales, which is substantially higher compared to the sector average.
 www.barchart.com
Solid Financial Standing
CrowdStrike reported its second-quarter fiscal 2027 results on Aug. 26, for the quarter ended Jul. 31. Total revenue increased 26% year-over-year (YOY) to $1.5 billion, compared with $1.2 billion in the prior-year quarter. Subscription revenue grew 27% to $1.4 billion, versus $1.1 billion a year earlier, continuing to account for the overwhelming majority of the company’s sales.
CrowdStrike’s recurring-revenue metrics were particularly strong. Ending annual recurring revenue (ARR) reached $5.8 billion, up 25% YOY. Net new ARR accelerated considerably, rising 51% YOY to $333 million. Falcon Flex ARR more than doubled to $2.3 billion, up 101% YOY, highlighting increasing adoption.
Profitability also improved meaningfully. On an adjusted basis, net income increased to $322.9 million, from $237.4 million, while adjusted EPS rose 34.8% to $0.31 from $0.23. Non-GAAP operating income increased to $371.6 million, compared with $255 million in the year-ago period.
CrowdStrike also continued to generate substantial cash. Operating cash flow reached $530.3 million, while free cash flow rose to a record $377.4 million.
Furthermore, management raised its fiscal 2027 outlook following the strong quarter. CrowdStrike now expects full-year revenue of $5.991 billion to $6.011 billion, compared with its previous forecast of $5.915 billion to $5.959 billion. The stronger outlook reflects continued demand for cloud-based cybersecurity solutions.
Full-year ARR is expected to reach approximately $6.60 billion, non-GAAP operating income is projected at $1.497 billion to $1.508 billion, and adjusted EPS at $1.25 to $1.26.
For the third quarter of fiscal 2027, CrowdStrike expects revenue of $1.52 billion to $1.53 billion, with adjusted EPS of about $0.31.
Analysts tracking CRWD project the company’s EPS to rise significantly YOY to $0.08 in fiscal 2027 and $0.22 in fiscal 2028.
What Do Analysts Expect for CrowdStrike Stock?
Wall Street analysts have continued to update their views on CrowdStrike following its strong second-quarter fiscal 2027 results.
Most recently, Wedbush initiated coverage with an “Outperform” rating and a $250 price target, citing CrowdStrike’s positioning in the expanding cybersecurity market and growing security needs associated with artificial intelligence.
Also, this month, Rosenblatt Securities reiterated its “Buy” rating on CrowdStrike and maintained a $250 price target, as the firm remained constructive on the cybersecurity company following its strong fiscal second-quarter results and recent developments.
However, some were cautious despite the plausible growth potential, including Macquarie, which maintained its “Neutral” rating on CrowdStrike with a $200 price target.
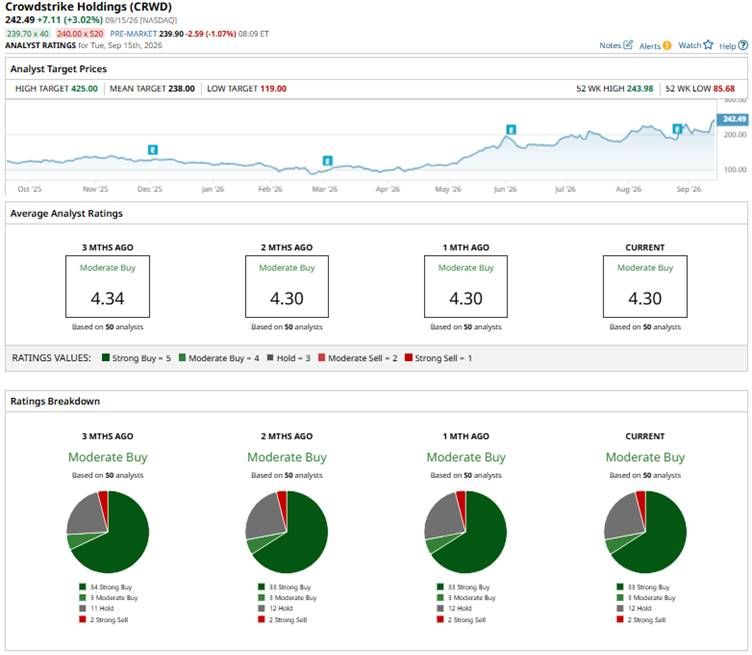
Overall, CRWD has a consensus rating of a “Moderate Buy.” Of the 50 analysts covering the stock, 33 advise a “Strong Buy,” three suggest a “Moderate Buy,” 12 analysts give it a “Hold” rating, and two “Strong Sell.”
While CRWD is currently trading above the average price target of $238, the Street-high target of $425 signals that the stock could rise as much as 75.3% from current levels.
 www.barchart.com
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘The Genie’s Out of the Bottle’ on AI Risks, Creating a Buying Opportunity in CrowdStrike Stock Nasdaq Futures Climb as Chipmakers Extend Advance Ford Hasn’t Raised Its Dividend in Years. Don’t Count on a Hike in 2026. FLNC Stock Alert: What to Know as Fluence Energy Cuts Guidance