

Financing has become a key topic of debate in regard to CoreWeave (CRWV). CRWV stock has fallen about 12% over the past five days and is nearing its 52-week low as investors wonder whether the company can fund one of the most aggressive infrastructure buildouts in the artificial intelligence (AI) industry.
But Piper Sandler seems to think the market is overreacting. Analyst James Fish recently kept an "Overweight" rating on CoreWeave stock while reducing his price target to $124 from $153. Despite the reduction, Piper Sandler believes CoreWeave is a preferred pick in the space and that the financing issues are overblown, with AI infrastructure companies able to rely on customer prepayments, asset-based financing, and cash flows from existing contracts for funding new capacity.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
CoreWeave Stock Overview
Headquartered in Livingston, New Jersey, CoreWeave operates a specialized cloud platform for AI workloads providing high-performance computing infrastructure mainly based on Nvidia (NVDA) GPUs. The company was founded in 2017 and has a market capitalization of $24.9 billion.
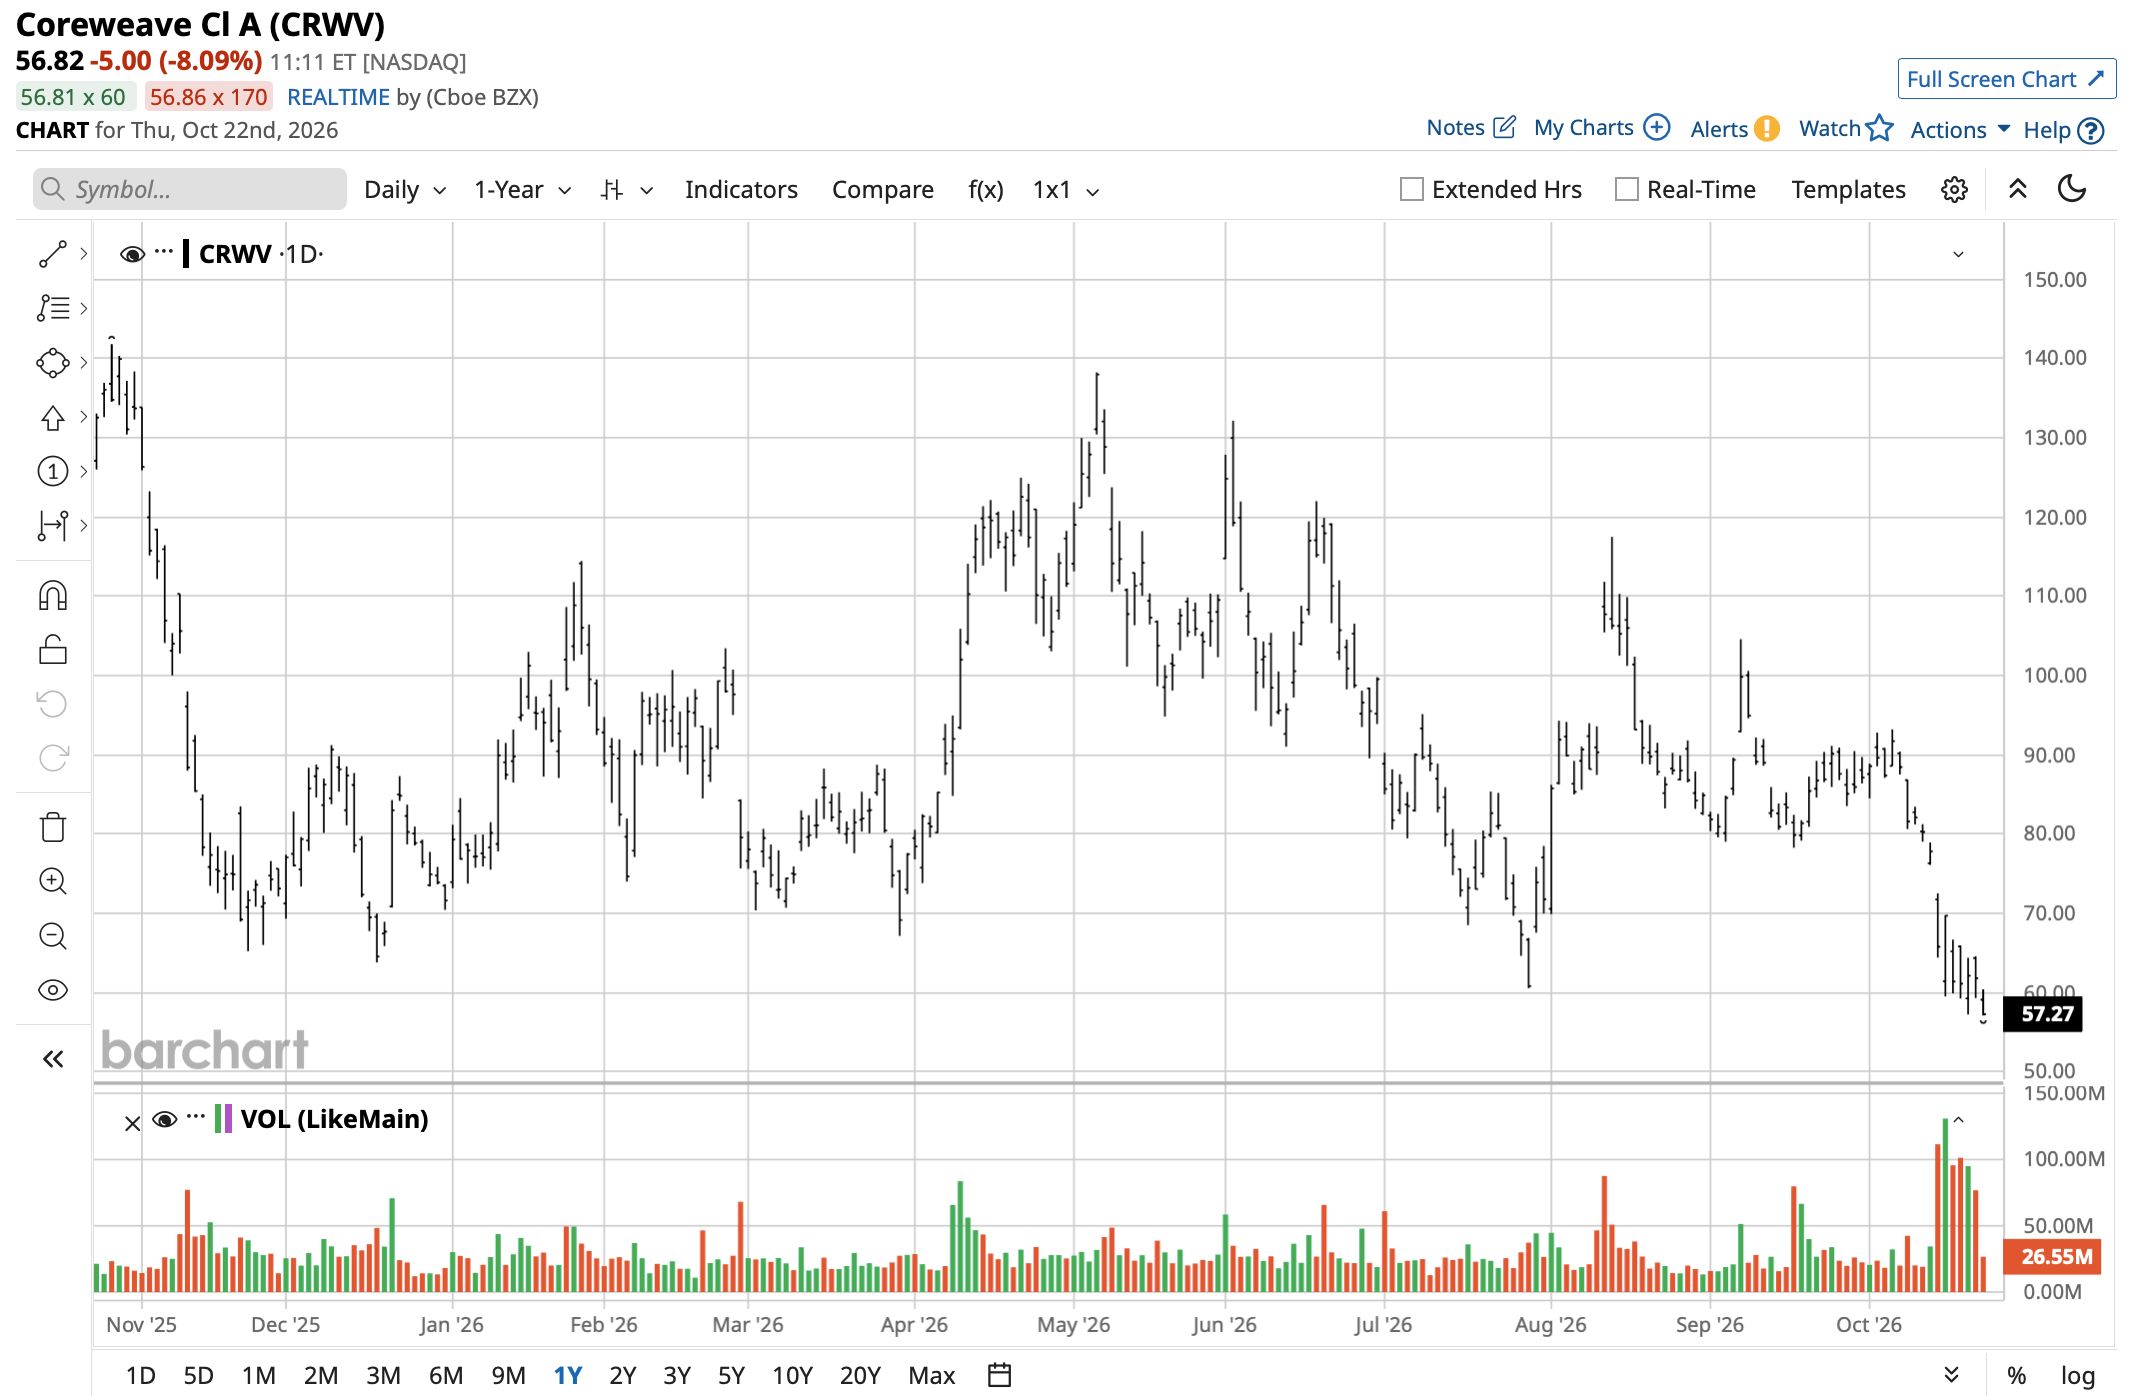
CRWV stock has experienced an unprecedented plunge. Shares now trade at $54.24, approximately 62% below the 52-week high of $141.79 and just slightly above the 52-week low of $53.50. The stock is also down about 24% so far this year, while the S&P 500 ($SPX) is up by about 13% year-to-date (YTD).
 www.barchart.com
The valuation is compressed together with the decline. CRWV stock trades at 4.9 times sales and has no meaningful price-to-earnings (P/E) ratio due to CoreWeave's losses. The sales multiple looks somewhat reasonable for such a rapidly growing company. However, the bigger question is whether the company will be able to turn its enormous contracted demand into cash flows fast enough to finance its capital structure.
CoreWeave Reports Earnings Beat
Demand is clearly not the issue, as can be seen from CoreWeave's second-quarter results. Revenue reached $2.58 billion in Q2, up about 112% year-over-year (YOY) from $1.21 billion and beating expectations of roughly $2.54 billion. Adjusted loss per share amounted to $1.03, which was better than the expected loss of $1.20 per share.
However, the expenses for this growth were enormous. The company reported a GAAP net loss of $626 million compared to a loss of $290 million a year ago, while net interest expenses jumped from $267 million to $640 million in Q2. Meanwhile, adjusted EBITDA grew to $1.51 billion from $753 million, resulting in an adjusted EBITDA margin of 59%.
Management increased its revenue forecast for 2026 to a range of $12.4 billion to $13.2 billion and guided for Q3 revenue of $3.45 billion to $3.6 billion. But this growth is not cheap at all, as the company expects capital expenditures of $35 billion to $39 billion for the year and around $860 million to $940 million of interest expenses in Q3 alone.
That is where Piper Sandler's argument comes into play. As of the end of Q2, CoreWeave had a revenue backlog of approximately $104 billion, without accounting for an additional $25 billion of customer commitments added in early Q3. The company also has demonstrated access to capital with a $3.1 billion term loan, $1 billion of strategic investment from Jane Street, and “more than $10 billion of unsecured debt and convertible bonds.”
Finally, the demand environment remains healthy, too. CoreWeave noted in September that it continues to sign new compute contracts while its contracted power has increased to approximately 4.2 gigawatts. In other words, CoreWeave's balance sheet risks are evident, but there is also no sign of the demand for its AI compute capacity slowing down.
What Do Analysts Think of CoreWeave Stock?
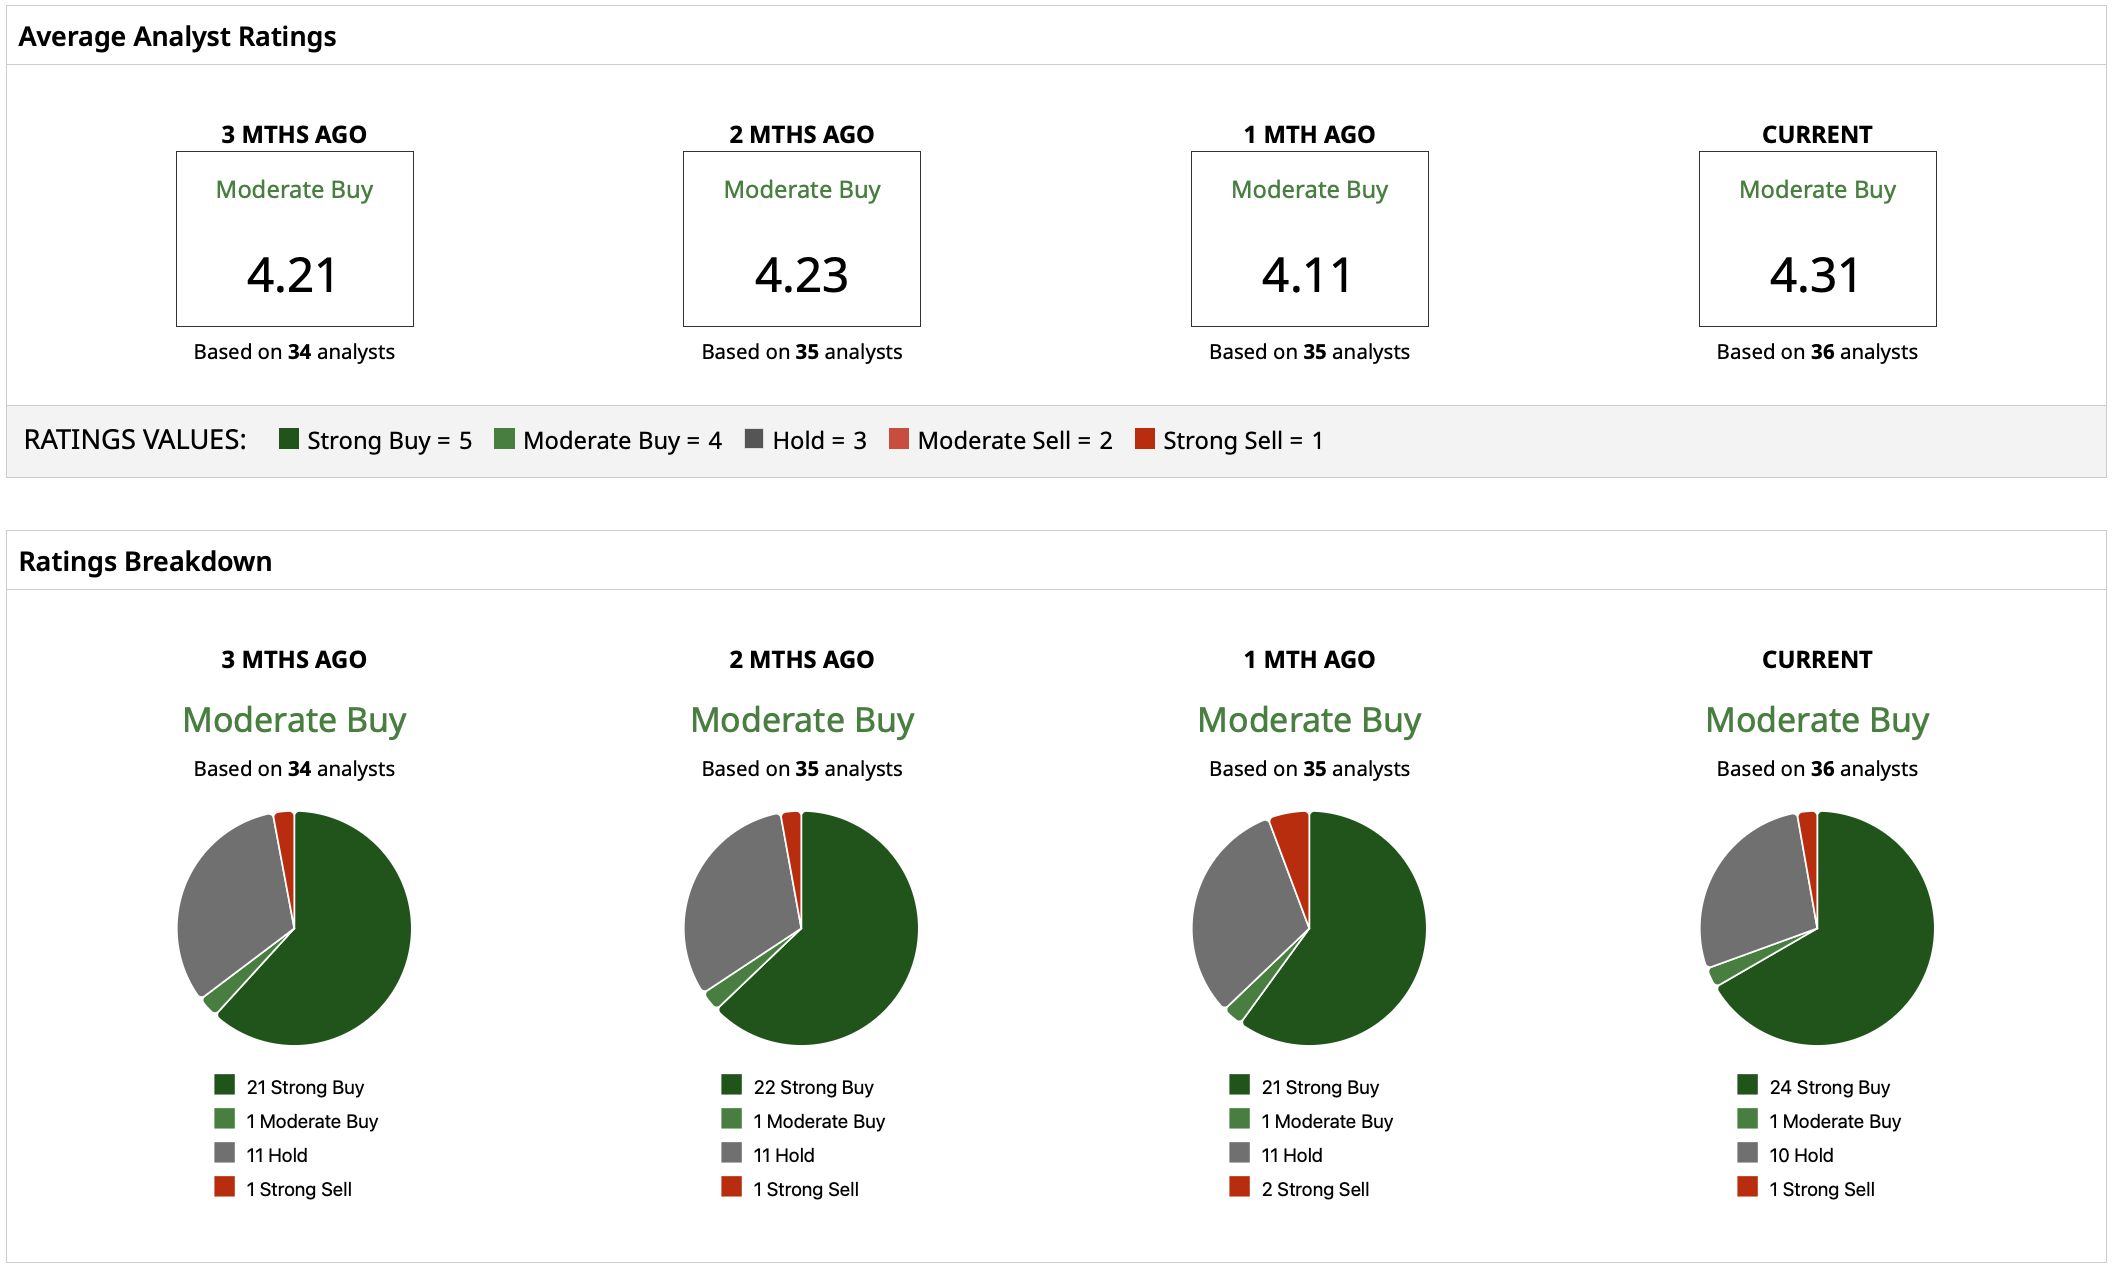
Despite the fall in CRWV stock, Wall Street remains optimistic with a consensus "Moderate Buy" rating overall. The mean price target of $131.83 implies potential upside of approximately 143% from current levels. CRWV stock has a high price target of $250 and a low price target of $39 per share.
Meanwhile, Piper Sandler's revised target of $124 implies potential upside of around 129% from here. Still, the firm is not saying that the risks have disappeared. Piper Sandler expects AI infrastructure stocks to continue to trade under pressure until free cash flow improves, borrowing rates stabilize, or investors have better visibility when it comes to financing.
 www.barchart.com
On the date of publication, Yiannis Zourmpanos did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Piper Sandler Says Financing Concerns for CoreWeave Are Overblown. Not Everyone Is Convinced. Why You Should Buy Meta Stock Before It Touches $1,050 Fermi Has a New Plan for Growing Its Data Center Business. What That Means for FRMI Stock. ‘I Don’t Want You to Contribute to a Trump Account for a Child. Period’: Suze Orman Says Take the Free $1,000 and Your Employer’s $2,500, Then Stop.