

SoFi (SOFI) will release its third-quarter 2026 results on Tuesday, Oct. 27. The event matters to SOFI stock fans because the results could shape the stock's future trajectory.
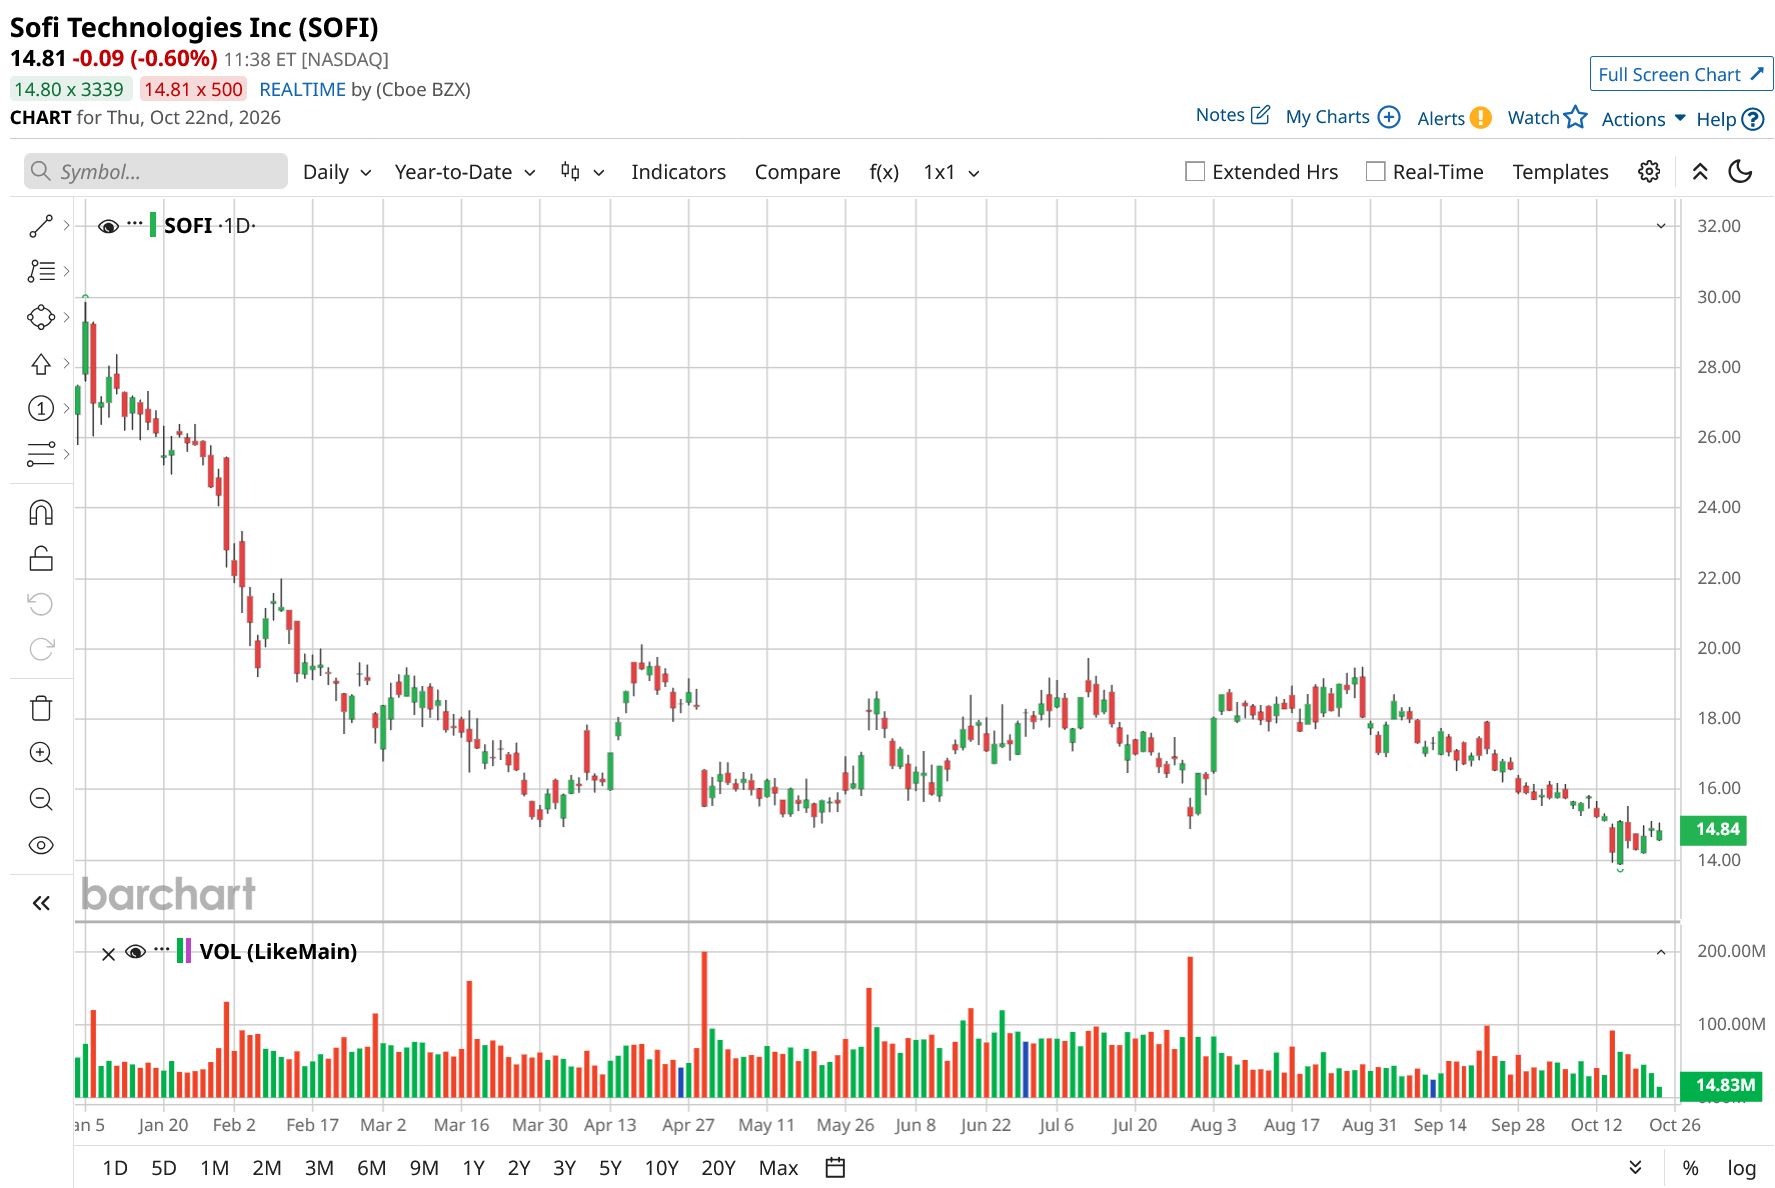
SoFi shares have faced significant selling pressure, falling more than 43% year-to-date (YTD) and trading 54.5% below their 52-week high. Beyond broader market dynamics, a key concern weighing on investor sentiment is the company's evolving revenue composition.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Investors have rewarded SoFi's efforts to diversify its revenue streams and expand fee-based, non-lending operations. A more diversified revenue base reduces SoFi’s reliance on credit-sensitive business and supports more sustainable earnings growth. However, in the recent quarterly results, lending has increasingly outpaced non-lending operations.
Although lending remains a key growth engine for SoFi, it also requires more capital and increases exposure to borrower defaults and shifting credit conditions.
Second-quarter performance brought these concerns into sharper focus, as the lending business contributed significantly to overall revenue.
So, could SoFi's third-quarter results ease concerns about its revenue mix, or will continued reliance on lending remain a headwind for the stock? Let’s take a closer look.
 www.barchart.com
SoFi’s Q3 Outlook
SoFi is positioned to deliver solid revenue and earnings growth in Q3, supported by expanding membership, deeper customer engagement, and a diversified revenue mix. The company’s Q2 results highlighted the strength of its customer acquisition strategy, with membership increasing by 1.1 million to 15.8 million, representing 35% year-over-year (YoY) growth. Product adoption also accelerated, with customers opening a record 2.2 million new products, lifting total product holdings to 24.4 million, up 42% from the prior year.
Notably, SoFi is benefiting from more in-depth relationships with existing customers. As members adopt multiple products across SoFi’s ecosystem, it has greater opportunities to increase revenue per customer while improving the efficiency of its customer acquisition spending. This dynamic could support operating leverage over time, allowing revenue to grow without a proportionate increase in marketing and acquisition costs.
Accelerating cross-selling strengthens this outlook. Existing members accounted for more than 51% of new products opened in Q2, compared with 43% in Q1. This increase suggests SoFi is becoming more effective at monetizing its existing customer base and driving broader adoption across its platform. This trend will likely continue into Q3, strengthening customer retention, improving customer lifetime value, and supporting more sustainable growth.
Revenue diversification will support SoFi’s Q3 growth. Fee-based revenue reached $472 million in Q2, accounting for approximately 39% of total revenue. Higher loan originations, expansion of the loan platform business (LPB), increased interchange income, stronger trading activity, and continued development of the technology platform business supported growth. Continued LPB momentum will support fee-based revenue in Q3.
The LPB's strategic value lies in its capital-light business model. By facilitating loan originations and earning fees without retaining the loans on its balance sheet, SoFi can generate revenue while limiting its capital requirements and exposure to loans held for investment.
Over the longer term, management expects non-lending activities to contribute more than 50% of total revenue, reflecting its focus on diversifying its revenue. However, lending could still be the biggest contributor to its top line in Q3.
In Q3, lending may continue to account for most revenue, supported by solid growth in personal loans, home loans, and student loans.
On the earnings front, SoFi could benefit from stronger revenue, improved customer monetization, and a growing deposit base. Deposits provide a low-cost funding source that supports its bottom line. Overall, analysts expect SoFi to report Q3 earnings of $0.17 per share, up 54.5% YoY.
Analysts Remain Divided on SOFI Stock
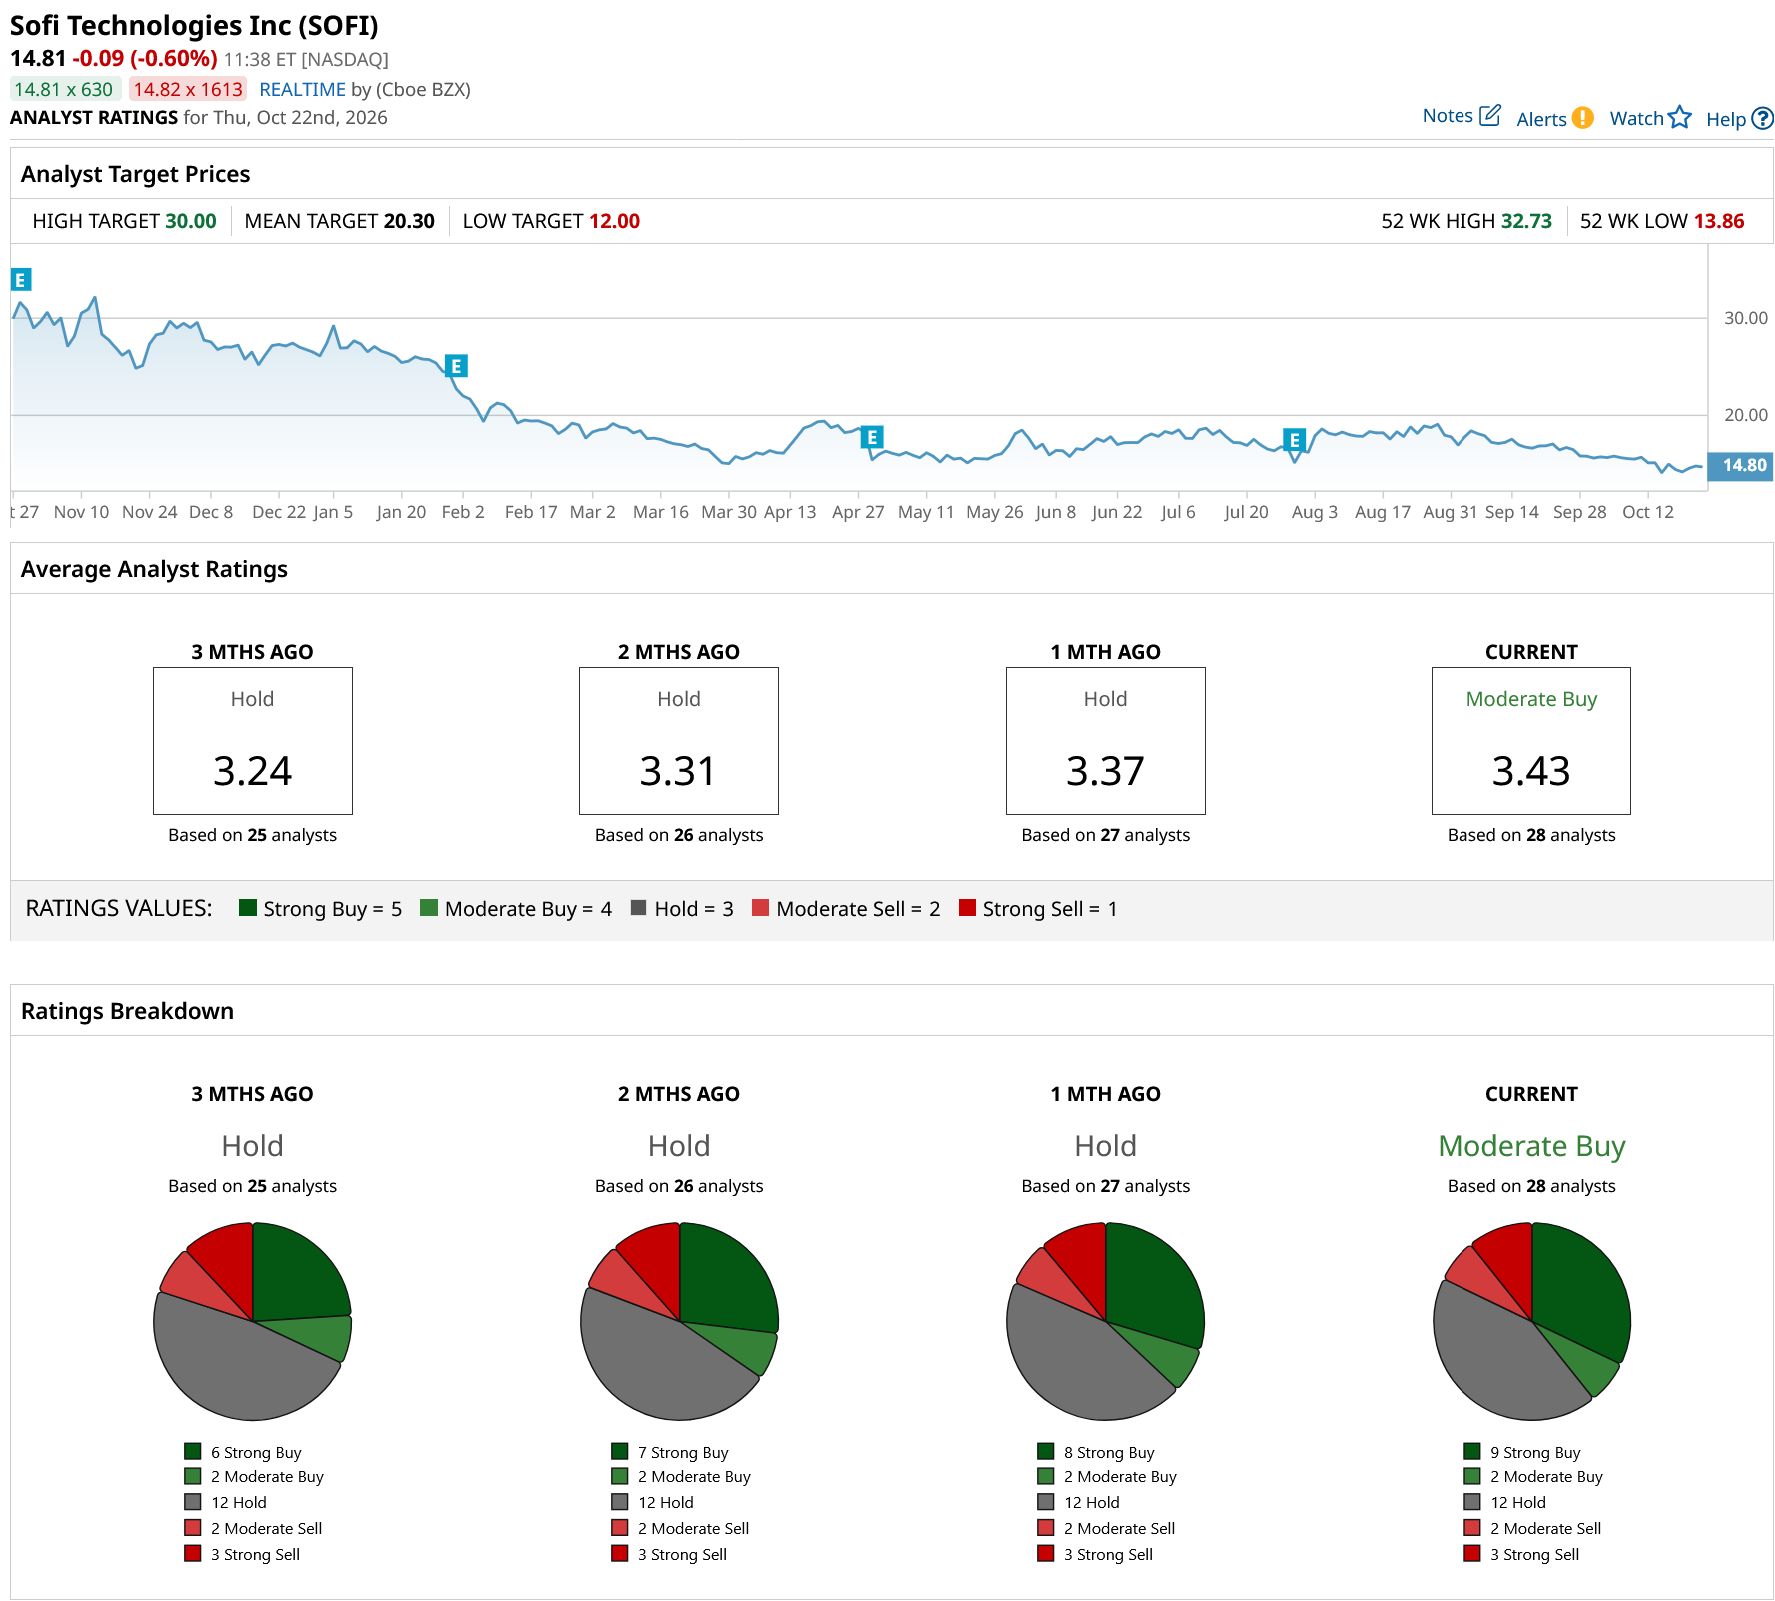
SoFi’s Q3 results will be a key test of whether its revenue diversification efforts pay off and ease concerns about its revenue mix. Strong membership growth, deeper customer engagement, and expanding fee-based revenue could support Q3 performance. However, lending could still drive growth. This explains why analysts are quite divided on SOFI stock ahead of Q3. While the consensus rating is “Moderate Buy,” the majority still give it a “Hold” or “Sell” rating ahead of the Q3 earnings release.
However, the significant decline in SOFI stock and the expected increase in non-lending revenue in the coming quarters make SoFi a compelling long-term pick.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear SoFi Stock Fans, Mark Your Calendar for October 27 Piper Sandler Says Financing Concerns for CoreWeave Are Overblown. Not Everyone Is Convinced. Why You Should Buy Meta Stock Before It Touches $1,050 Fermi Has a New Plan for Growing Its Data Center Business. What That Means for FRMI Stock.