

Ralph Lauren Corporation’s RL wholesale strategy is supporting top-line momentum while the company continues to improve the quality of sales by emphasizing stronger full-price performance and more selective distribution. In the first quarter of fiscal 2027, the wholesale strategy increasingly emphasized quality, with the company benefiting from stronger full-price wholesale trends while accelerating its planned reduction in off-price sales and exits from lower-tier full-price stores.
In the first quarter of fiscal 2027, global wholesale revenues grew 13% in constant currency. This was led by North America wholesale revenues, which increased 22%, supported by strong spring sellout trends, replenishment orders, resumed shipments to a luxury wholesale account and shipment timing from the fourth quarter of fiscal 2026. Approximately 15 percentage points of the increase came from shipment timing and resumed shipments, while management characterized the underlying growth as healthy.
The company is seeing stronger-than-expected trends in its full-price wholesale business, supporting an acceleration of its strategic reduction in off-price sales and exit from lower-tier full-price stores during the back half of the year. These actions align with the company’s broader efforts to elevate its positioning in the wholesale channel and improve quality of sales. As a result, management continues to expect stronger North American wholesale performance in the first half of fiscal 2027, followed by a more pronounced impact from these strategic reductions in the second half. The company expects these reductions to more than offset underlying full-price growth and result in modest North America wholesale growth for fiscal 2027.
Wholesale continues to play an important role in the company’s strategy, particularly through quality wholesale. Management views quality wholesale as an effective avenue for brand discovery and new consumer recruitment. The company sees quality wholesale as a channel that can facilitate brand discovery and help recruit new consumers, particularly within its key-city ecosystems.
Overall, Ralph Lauren’s refined wholesale approach is focused on strengthening the quality of sales while further elevating the brand’s positioning in the channel. Management continues to view quality wholesale as an important part of its key-city strategy, particularly as a means of supporting brand discovery and new consumer recruitment.
The Zacks Rundown for RL
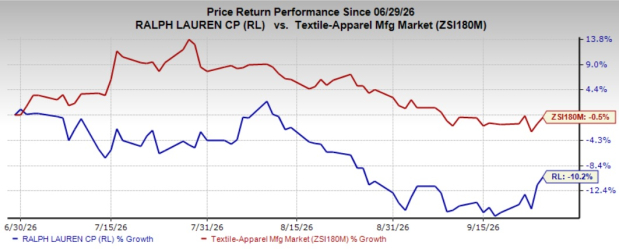
Ralph Lauren’s shares have lost 10.2% in the past three months compared with the industry’s 0.5% decline.
Image Source: Zacks Investment Research
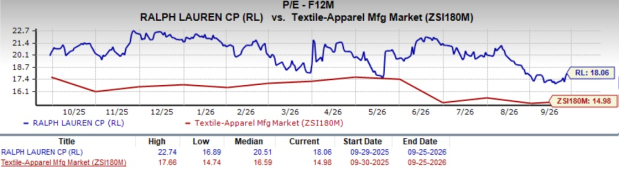
From a valuation standpoint, RL trades at a forward price-to-earnings ratio of 18.06 compared with the industry’s average of 14.98. Ralph Lauren currently carries a Zacks Rank #3 (Hold).
Image Source: Zacks Investment Research
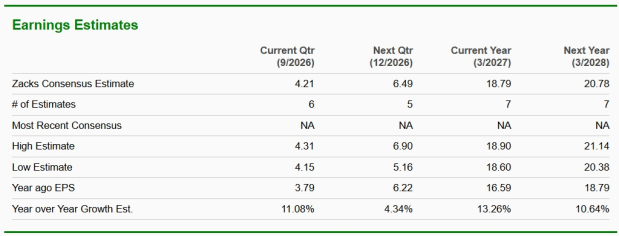
The Zacks Consensus Estimate for RL’s current and next fiscal-year earnings implies a rise of 13.3% and 10.6%, respectively, from the year-ago figures.
Image Source: Zacks Investment Research
Stocks to Consider
Some better-ranked stocks have been discussed below:
Vince Holding Corp. VNCE provides luxury apparel and accessories in the United States and internationally. It operates through Vince Wholesale and Vince Direct-to-Consumer segments. At present, the company carries a Zacks Rank of 1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for VNCE’s current fiscal-year sales and earnings implies growth of 12.7% and 172.7%, respectively, from the year-ago reported figures. VNCE has delivered a trailing four-quarter earnings surprise of 561.4%, on average.
Kontoor Brands, Inc. KTB, a lifestyle apparel company, designs, manufactures, procures, sells and licenses apparel, footwear and accessories, primarily under the Wrangler, Lee and Helly Hansen brands. At present, KTB carries a Zacks Rank of 2 (Buy).
The Zacks Consensus Estimate for KTB’s current fiscal-year sales and earnings implies a decline of 14.3% and 6.1%, respectively, from the year-ago figures. KTB delivered a trailing four-quarter earnings surprise of 21.4%, on average.
Savers Value Village, Inc. SVV, a thrift operator, sells second-hand merchandise in retail stores in the United States, Canada and Australia. SVV currently carries a Zacks Rank of 2.
The Zacks Consensus Estimate for SVV’s current financial-year sales and earnings is expected to rise 6.1% and 6.7%, respectively, from the corresponding year-ago reported figures. SVV delivered a trailing four-quarter negative earnings surprise of 1.6%, on average.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ralph Lauren Corporation (RL): Free Stock Analysis Report
Vince Holding Corp. (VNCE): Free Stock Analysis Report
Kontoor Brands, Inc. (KTB): Free Stock Analysis Report
Savers Value Village, Inc. (SVV): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).