

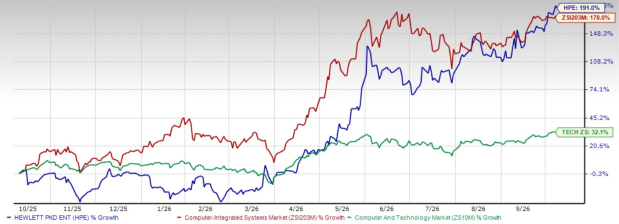
Hewlett Packard Enterprise HPE shares have skyrocketed 191% in the past year, outperforming the Zacks Computer - Integrated Systems industry and Zacks Computer and Technology sector’s appreciation of 178% and 32.1%, respectively.
HPE YTD Performance Chart
Image Source: Zacks Investment Research
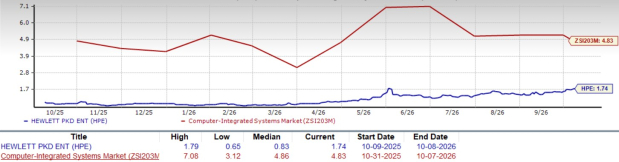
Despite the appreciation in the share price, HPE trades at a discount. From a valuation standpoint, HPE trades at a forward price-to-sales ratio of 1.74, below the industry’s 4.83.
HPE Forward 12-Month (P/S) Valuation Chart
Image Source: Zacks Investment Research
Given these factors, the question arises: Should investors buy, sell or hold HPE stock?
HPE Benefits From Momentum in AI Infrastructure
Hewlett Packard Enterprise is benefiting from a broader shift toward AI infrastructure, networking modernization and hybrid cloud. The company is aligning compute, storage and networking with enterprise inferencing, agentic AI and data-intensive workloads. In the third quarter of fiscal 2026, Cloud & AI revenues reached $9 billion, up 25% year over year, with a 17% operating margin.
HPE’s server revenues rose 35%, while traditional server orders increased 75% as customers favored AI-ready configurations and higher-value systems. HPE’s fourth-quarter fiscal 2026 Cloud & AI revenues are expected to grow 60% to 72%. Hewlett Packard Enterprise is packaging compute, storage, networking and cloud management into AI systems and Private Cloud AI solutions for inferencing and agentic workloads.
In the third quarter of fiscal 2026, HPE’s AI systems orders were $2.4 billion, up more than 30% sequentially, while AI systems backlog rose 14% sequentially to $6.8 billion. Private Cloud AI orders increased triple digits year over year, showing wider adoption of HPE’s on-premises AI factory approach. HPE was also awarded a $3.5 billion inferencing deal with a hyperscaler customer.
Hewlett Packard Enterprise is expanding its hybrid cloud operating model through GreenLake, which lets customers manage infrastructure and software across on-premises and cloud environments with consumption-based economics. In the third quarter of fiscal 2026, GreenLake customers increased 18% year over year to 52,000 from 44,000, while management cited higher net retention as customers broadened usage of software and intelligent cloud services.
HPE Wins Against Competitors With Diverse Portfolio
HPE competes with Super Micro Computer SMCI, Dell Technologies DELL and Cisco CSCO in the AI infrastructure market. However, HPE’s ability to package compute, storage, networking and services into pre-configured solutions can reduce deployment complexity for enterprises and sovereign customers while giving it an edge over its competitors. Super Micro Computer is on track to scale rack production capacity to more than 6,000 AI racks per month by the end of fiscal 2026, including 3,000 direct liquid cooling racks monthly.
Super Micro Computer is already shipping 150kW AI racks in volume and preparing 250kW and 500kW rack solutions to support future high-density AI training and inference workloads. Dell Technologies is a major supplier of servers and storage systems, with a broad customer base across enterprises and cloud providers. Its scale, established distribution and service offerings give it an edge in winning large contracts.
Cisco has also taken $5.3 billion of hyperscaler AI infrastructure orders year to date in fiscal 2026 and raised its full-year order outlook to $9 billion from $5 billion. However, HPE’s ability to package compute, storage, networking and services into pre-configured solutions can reduce deployment complexity for enterprises and sovereign customers. This gives HPE an edge over its competitors.
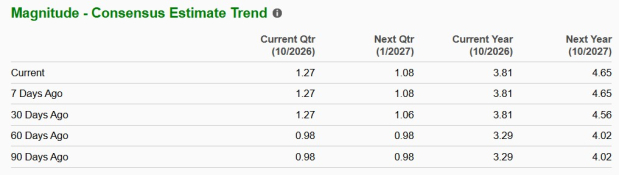
HPE is also able to keep its margin stable. The Zacks Consensus Estimate for HPE’s fiscal 2026 margin suggests year-over-year growth of 97%. Estimates have remained unchanged for the past 30 days.
Image Source: Zacks Investment Research
Conclusion: Buy HPE Stock Now
Hewlett Packard Enterprise’s strong AI infrastructure momentum, expanding AI backlog, growing GreenLake adoption and integrated portfolio support its growth outlook. Despite a sharp share price rally, HPE’s valuation remains attractive relative to industry peers. Given these factors, it’s prudent to accumulate this Zacks Rank #1 (Strong Buy) stock. You can see the complete list of today’s Zacks #1 Rank stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Hewlett Packard Enterprise Company (HPE): Free Stock Analysis Report
Cisco Systems, Inc. (CSCO): Free Stock Analysis Report
Dell Technologies Inc. (DELL): Free Stock Analysis Report
Super Micro Computer, Inc. (SMCI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).