

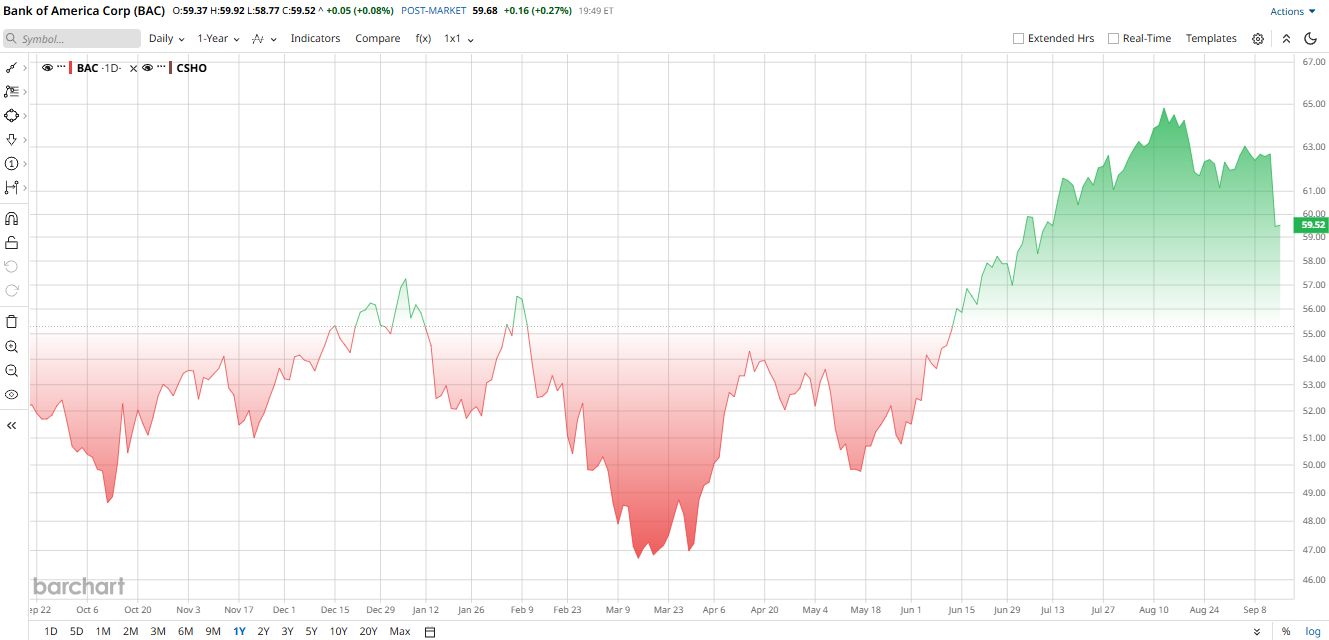
Bank of America (BAC) shares recently suffered their steepest one-day drop since April 2025 after CEO Brian Moynihan warned that third-quarter investment banking fees could fall at least 10% while sales and trading revenue may be flat from a year ago. BAC stock fell 5.1% to $59.47 on Sept. 14, while the S&P 500 banking index dropped 2.7%.
Big banks tend to be cyclical, and this guidance simply shows a slower period for markets. In many ways, the market reaction was “overdone,” as Morgan Stanley noted. The stock trades near fair value on its usual metrics, and the selloff feels like a short-term blip. For long-term investors, Bank of America’s core loan and deposit growth, higher rates driving net interest income, and strong capital levels remain reassuring.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
So, do shares of Bank of America represent a buying opportunity now? I think so — or that the dip is at least worth monitoring, given BAC stock’s strengths.
Bank of America Stock Has Still Delivered in 2026
Bank of America stock is up about 6% year-to-date (YTD) and roughly 13% over the past 52 weeks. The company has shown stronger net interest income (NII), loan growth, and recovering trading and investment banking activity. The latest pullback came after management’s cautious Q3 outlook.
BAC stock trades at about 13.6 times earnings versus about 12 times for the sector median. Its price-to-book (P/B) ratio is about 1.5 times compared with 1.3 times for the sector median. The stock therefore carries a premium on both measures.
 www.barchart.com
The Guidance Shock Could Be Temporary
Moynihan expects Q3 investment banking fees of $1.6 billion to $1.8 billion, down from about $2 billion a year earlier. Sales and trading revenue is expected near $5.4 billion, roughly flat year-over-year (YOY).
Still, management said the deal pipeline remains strong, and consumer spending is healthy. Bank of America also expects full-year net interest income growth at the upper end of its 6% to 8% range. That could cushion weaker fee income.
JPMorgan expects mid- to high-teen growth in Q3 investment banking and markets revenue. That suggests some of Bank of America’s weakness may be company-specific rather than a broad collapse in deal activity.
Q2 Showed Strong Underlying Growth
Bank of America’s July quarter was strong. Revenue for the second quarter rose 15% year-over-year (YOY) to $31.6 billion. Net income increased 27% to $9.1 billion, while adjusted EPS climbed 34% to $1.21.
Global Banking reported $2 billion of net income, helped by investment banking fees that rose 50%. Global Markets posted $2.6 billion of net income, with sales and trading revenue up 33% to $7.1 billion.
Net interest income increased 9% to $16 billion. Average deposits rose more than 2% to $2.02 trillion, while average loans climbed 8% to $1.22 trillion. Cash and cash equivalents were about $229.7 billion in Q2 2026.
CFO Alastair Borthwick said that the quarter delivered “strong revenue growth across every business segment.” Management raised its full-year NII expectations to the upper end of 6% to 8% and expects 300 to 400 basis points of operating leverage.
Bank of America is also investing beyond traditional banking. In August, the firm launched a $250 billion critical infrastructure finance initiative covering digital, energy, and power projects.
Looking ahead, analysts expect EPS of about $4.67 in fiscal 2026, representing 23% YOY growth, followed by EPS of $5.27 in fiscal 2027, representing 13% YOY growth.
Analysts Still See Upside for BAC Stock
Morgan Stanley recently kept a $67 price target on BAC stock and said the recent reaction was “overdone” relative to Bank of America's earnings estimate changes. Wells Fargo maintained its $69 target and said weaker near-term capital markets activity could be offset by higher rates and a steeper yield curve. Meanwhile, Goldman Sachs lowered its target to $76 from $79 on Sept. 16.
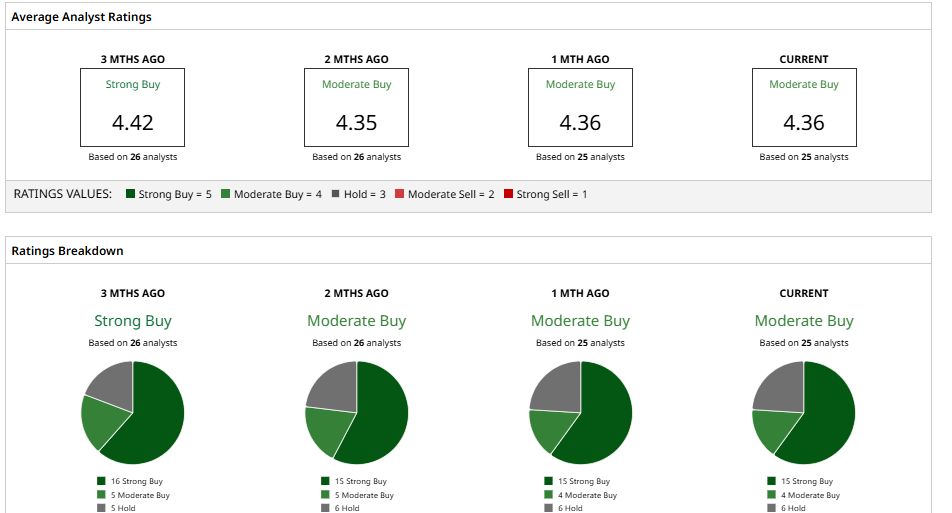
Overall, Wall Street has a consensus “Moderate Buy” rating on BAC stock. The mean price target of $67.08 implies potential upside of about 15% from current levels.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
As Meta Launches New Meta One Subscription, Here’s How You Should Play META Stock Bank of America Stock Just Suffered Its Worst Drop Since April 2025. Here’s Why. LCID Stock Surges as Lucid Unveils New European Robotaxi Partnership A $2.4 Billion Reason Why Generac Stock Is Up Today