

ASML (ASML) shares fell about 6% in a single trading session, a sharp decline for a company this size. The trigger came from a rather unexpected place: Anthropic’s Dario Amodei called for the AI industry to slow the pace of model development. Shortly after, Sam Altman of OpenAI and Elon Musk of xAI (SPCX) backed it too. That warning sent chip equipment stocks lower, and ASML was among the hardest hit. The reason lies in what the company does. ASML builds the machines that make advanced chips, and it’s the only firm in the world that makes the most cutting-edge ones. So every major chipmaker that wants to build the chips behind AI has to buy from ASML.
Why the Fear Hit ASML First
ASML sits one step further from AI than the chipmakers do. It gets paid when companies like Taiwan Semiconductor (TSM) decide to build new factories. That decision rests on how much AI growth they expect years later. So ASML lives on future expectations rather than today’s chip sales. When tech leaders talk about slowing down, those future growth bets are the first thing investors reconsider. The worry reaches ASML's future orders before it shows up in real demand.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
This was the second hit for the stock in less than one week. Just a few days earlier, Morgan Stanley trimmed its price target on ASML from EUR 1,930 to EUR 1,700. The firm cited softer China demand and margin concerns as the reasons for the cut.
I have also previously covered how Taiwan Semi was able to produce the latest node chips without requiring ASML's High-NA EUV machines. The stock has been pressured for some time, and the moat is facing more threats than ever.
While these factors have made investors cautious, the company’s actual business remains strong. ASML beat on bookings last quarter and raised its full-year outlook. As I cover later, most analysts still see big upside from here. The selloff, for now, is about fear rather than facts.
About ASML Stock
ASML Holding is the world’s leading supplier of advanced lithography machines used to manufacture semiconductor chips. It helps chipmakers produce increasingly powerful and efficient chips. It also provides extreme ultraviolet lithography systems and deep ultraviolet machines, as well as metrology and inspection tools that help customers measure, monitor, and improve chip production quality. The company serves as a major manufacturer worldwide and plays a critical role in the global semiconductor supply chain. Founded in 1984, the company is headquartered in Veldhoven, the Netherlands.
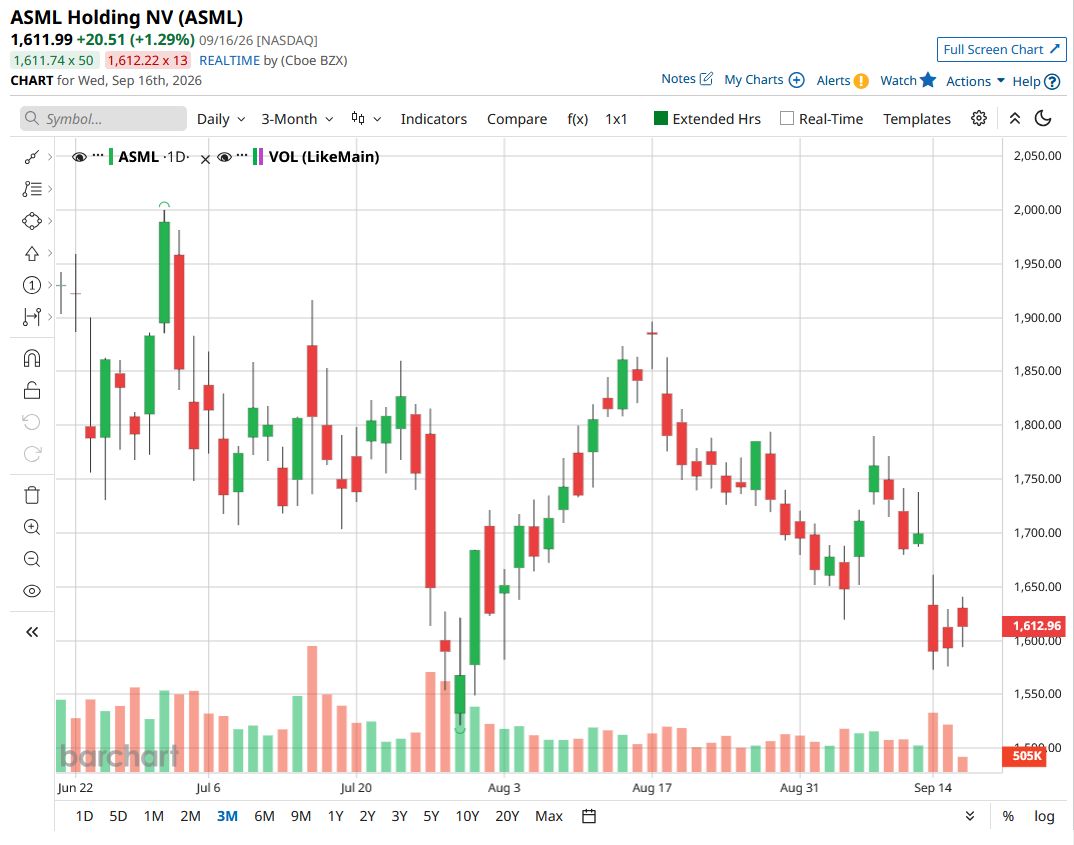
Over the past year, ASML stock has surged 87%. In contrast, the iShares Semiconductor ETF (SOXX) gained approximately 93% during the same period. The trend has continued this year as well, with the stock up 52% on a year-to-date (YTD) basis, while the iShares Semiconductor ETF rose 72%. As the company is the sole supplier of EUV lithography systems, investors remain optimistic about its long-term growth outlook.
 www.barchart.com
ASML’s valuation looks fair rather than stretched. The forward GAAP price-to-earnings (P/E) of 38.01x sits roughly in line with its 5-year average of 37.32x. So despite the gigantic run over the past year, the stock is barely trading at a premium to its history. The forward price-to-sales (P/S) ratio of 13.26x does not have a meaningful 5-year average to compare against. The EPS outlook is where ASML stands out. Analysts expect growth of 49% in 2026, 35% in 2027, 31% in 2028, and 19% in 2029. That is rapid growth for a company already worth over $650 billion.
The balance sheet is exceptional too. ASML holds $8.63 billion in cash against $2.26 billion in debt, leaving it net cash positive by more than $6 billion. That gives it room to keep investing through any slowdown. For a company growing this fast with hardly any debt, a valuation in line with its history looks reasonable.
ASML's Outlook Hike Highlights Growing Visibility Into Semiconductor Spending
ASML Holding reported its second-quarter fiscal 2026 earnings on July 15. Net system sales were EUR 6.6 billion, which included EUR 3.8 billion from EUV system sales and EUR 2.8 billion from non-EUV system sales. The earnings per share came in at EUR 7.59, while free cash flow was EUR 1.3 billion. The strong quarterly results were driven primarily by higher-than-expected Installed Base Management sales. The company’s R&D expenses came in at EUR 1.3 billion, and SG&A expenses came in at EUR 0.3 billion for the quarter. ASML noted higher technology and IT transformation costs in Q2, primarily in R&D.
Looking forward, management updated full-year 2026 guidance and now expects total net sales between EUR 43 billion and EUR 45 billion, with a gross margin between 54% and 56%. For the third quarter of fiscal 2026, the company guided net sales to be between EUR 11 billion and EUR 12 billion. CEO Christophe Fouquet said spending on AI infrastructure and advances in AI technology are increasing demand for advanced chips used in computing and memory. He added that customers are expanding their production capacity faster than expected, giving the company greater confidence in future demand.
What Do Analysts Expect For ASML Stock?
On Sept. 8, Bank of America Securities analyst Didier Scemama reiterated a “Buy” rating on ASML and did not assign any price target. Earlier, JPMorgan raised the firm’s price target from $2200 to $2400 and kept an “Overweight” rating. The upward price target revision came after the company’s second-quarter earnings.
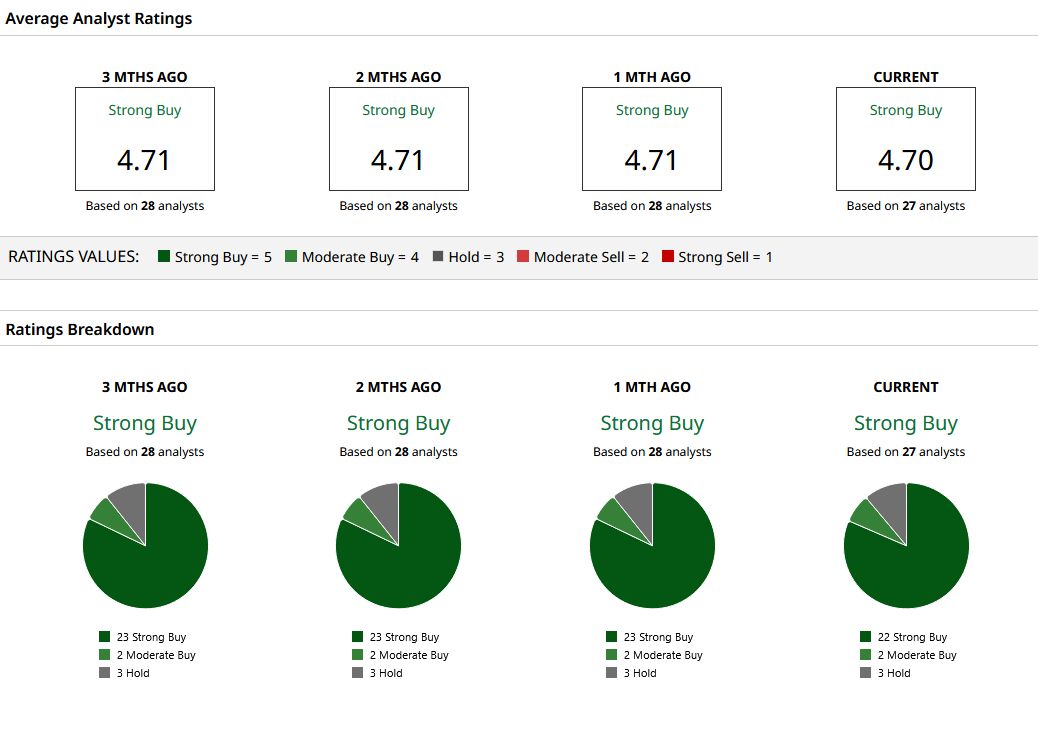
With 27 Wall Street analysts with coverage, ASML stock has a consensus “Strong Buy” rating. Out of these, 22 analysts have a “Strong Buy” rating, two have a “Moderate Buy” rating, and three have a “Hold” rating. The mean target price of $2,350.75 further implies a 47% upside from the current share price. The high price target of $2,859 shows investor confidence in the company’s long-term prospects.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Amodei, Altman, and Musk Called for an AI Slowdown. Here’s Why It’s a Warning Sign for ASML Shareholders. Before You Conclude the AI Era Won’t End Like the Dot-Com Era Did, Check Out These 2 Charts 1 Year Into the Microsoft Deal, IREN Is Delivering and a Rally May Follow Soon Is This A $20 Million Reason to Buy Infleqtion Stock Now?