

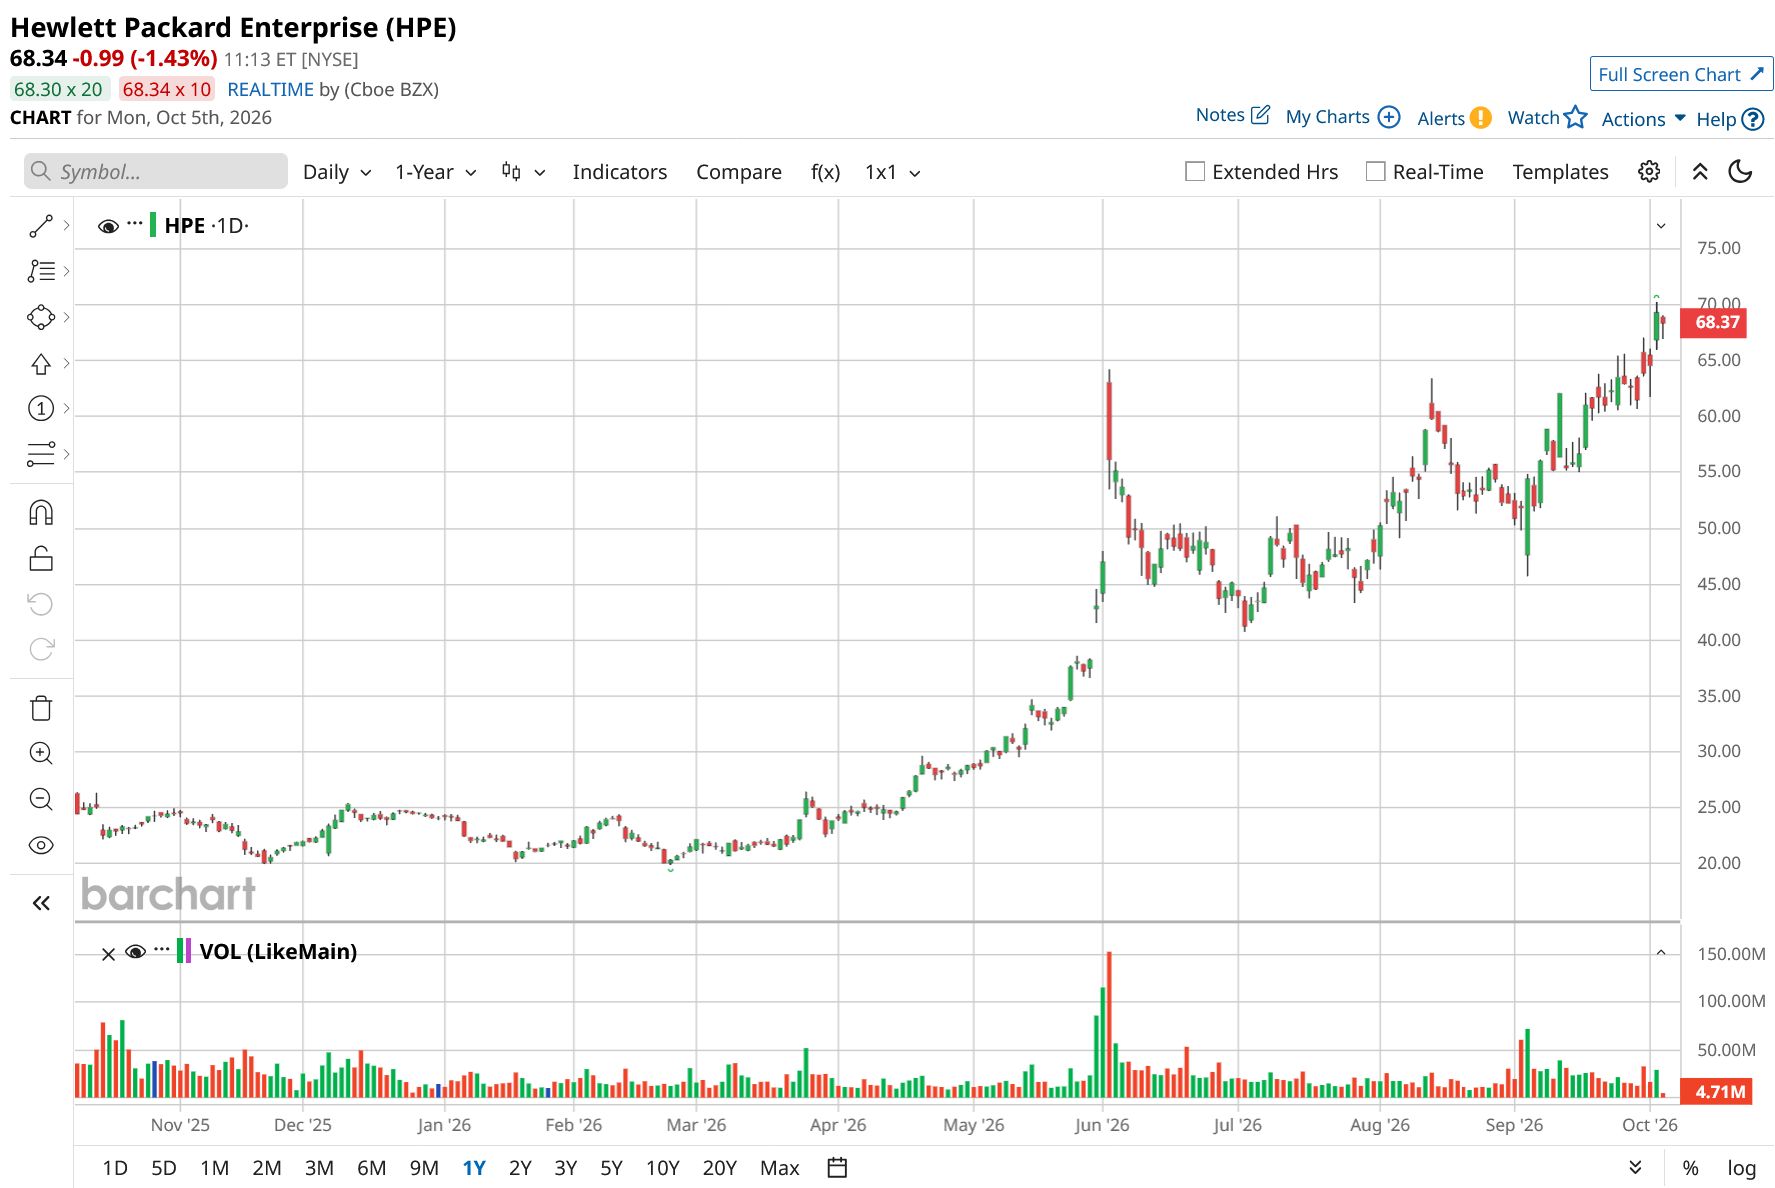
Hewlett Packard Enterprise (HPE) has delivered exceptional gains, with shares rising about 185% year-to-date (YTD). Despite this sharp rally, HPE’s outlook remains solid, supporting the bullish case.
A major driver behind HPE’s recent performance is the growing demand for AI infrastructure. Companies are investing heavily in the servers, storage, and networking equipment needed to build and run AI applications. This trend is also moving beyond the initial wave of AI training as businesses increasingly focus on AI inference and agentic AI, which could create another source of sustained infrastructure demand.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
HPE’s order momentum is encouraging. Orders continue to run ahead of revenue, suggesting customer demand remains strong. As HPE converts these orders into revenue, it could support stronger financial performance in the quarters ahead.
Further, AI spending is spreading across a wider range of industries and regions. Demand is no longer limited to a small group of large technology companies, implying the need for reliable computing, storage, and networking infrastructure should continue to grow. This supports the bull case for HPE stock despite the significant rally.
 www.barchart.com
HPE Delivered a Strong Q3
Hewlett Packard Enterprise delivered a strong fiscal Q3 performance. Its top line hit $12.2 billion, up 34%, while normalized orders increased 42%, indicating that demand is strengthening faster than reported revenue and creating a favorable foundation for future growth.
Networking has been a key catalyst for HPE. Segment revenue rose 10% on a normalized basis to $2.9 billion, while orders expanded 36%, suggesting strong potential for revenue acceleration as supply constraints ease and the backlog converts.
AI-related networking orders reached a record $700 million, more than doubling year over year, with cumulative orders of $2.2 billion already exceeding HPE's previous FY2026 target. Management consequently raised its target to $2.5–$3 billion. Demand remains strong in data center switching and routing, campus and branch infrastructure, and AI-oriented networking.
Looking ahead, HPE has more than doubled networking purchase commitments sequentially to improve capacity and shorten lead times. If execution improves, the substantial order backlog could translate into stronger top-line growth and operating leverage.
The Cloud and AI segment remains the primary growth avenue. Q3 revenue increased 25% to $9 billion. Within the segment, server revenue grew 35%, supported by higher average selling prices and demand. Importantly, AI systems orders increased more than 30% sequentially to $2.4 billion, while the AI backlog reached a record level. HPE expects AI systems revenue to improve in Q4 as backlog conversion accelerates.
Upbeat Outlook Supports Upside
Hewlett Packard Enterprise is poised to deliver solid growth ahead as the broader opportunity extends beyond conventional AI training. Increasing enterprise adoption of inference and agentic AI could stimulate sustained demand for servers, networking, and storage.
HPE’s upgraded guidance further strengthens the investment case. The company expects Q4 revenue of $13.9–$14.8 billion, including networking growth of 11–13% and Cloud and AI growth of 60–72%. FY2026 revenue growth is now projected at 34–37%, compared with the previous 29–33% outlook. Networking growth is expected at 73–74%, while adjusted EPS guidance has been raised to $3.75–$3.85 from $3.35–$3.45.
More importantly, strong demand, a sizable backlog, and large deals signed after quarter-end have led management to raise its FY2027 framework. Consolidated revenue growth is now expected at 13–17%, compared with the earlier 8–12% forecast. Networking is projected to grow 14–17%, while Cloud and AI revenue is expected to increase 14–18%.
Overall, HPE’s outlook points to improving growth visibility, strong AI-driven demand, and meaningful backlog support. Higher bookings, capacity investments, and raised earnings expectations will likely power its stock higher.
Load Up on HPE Stock
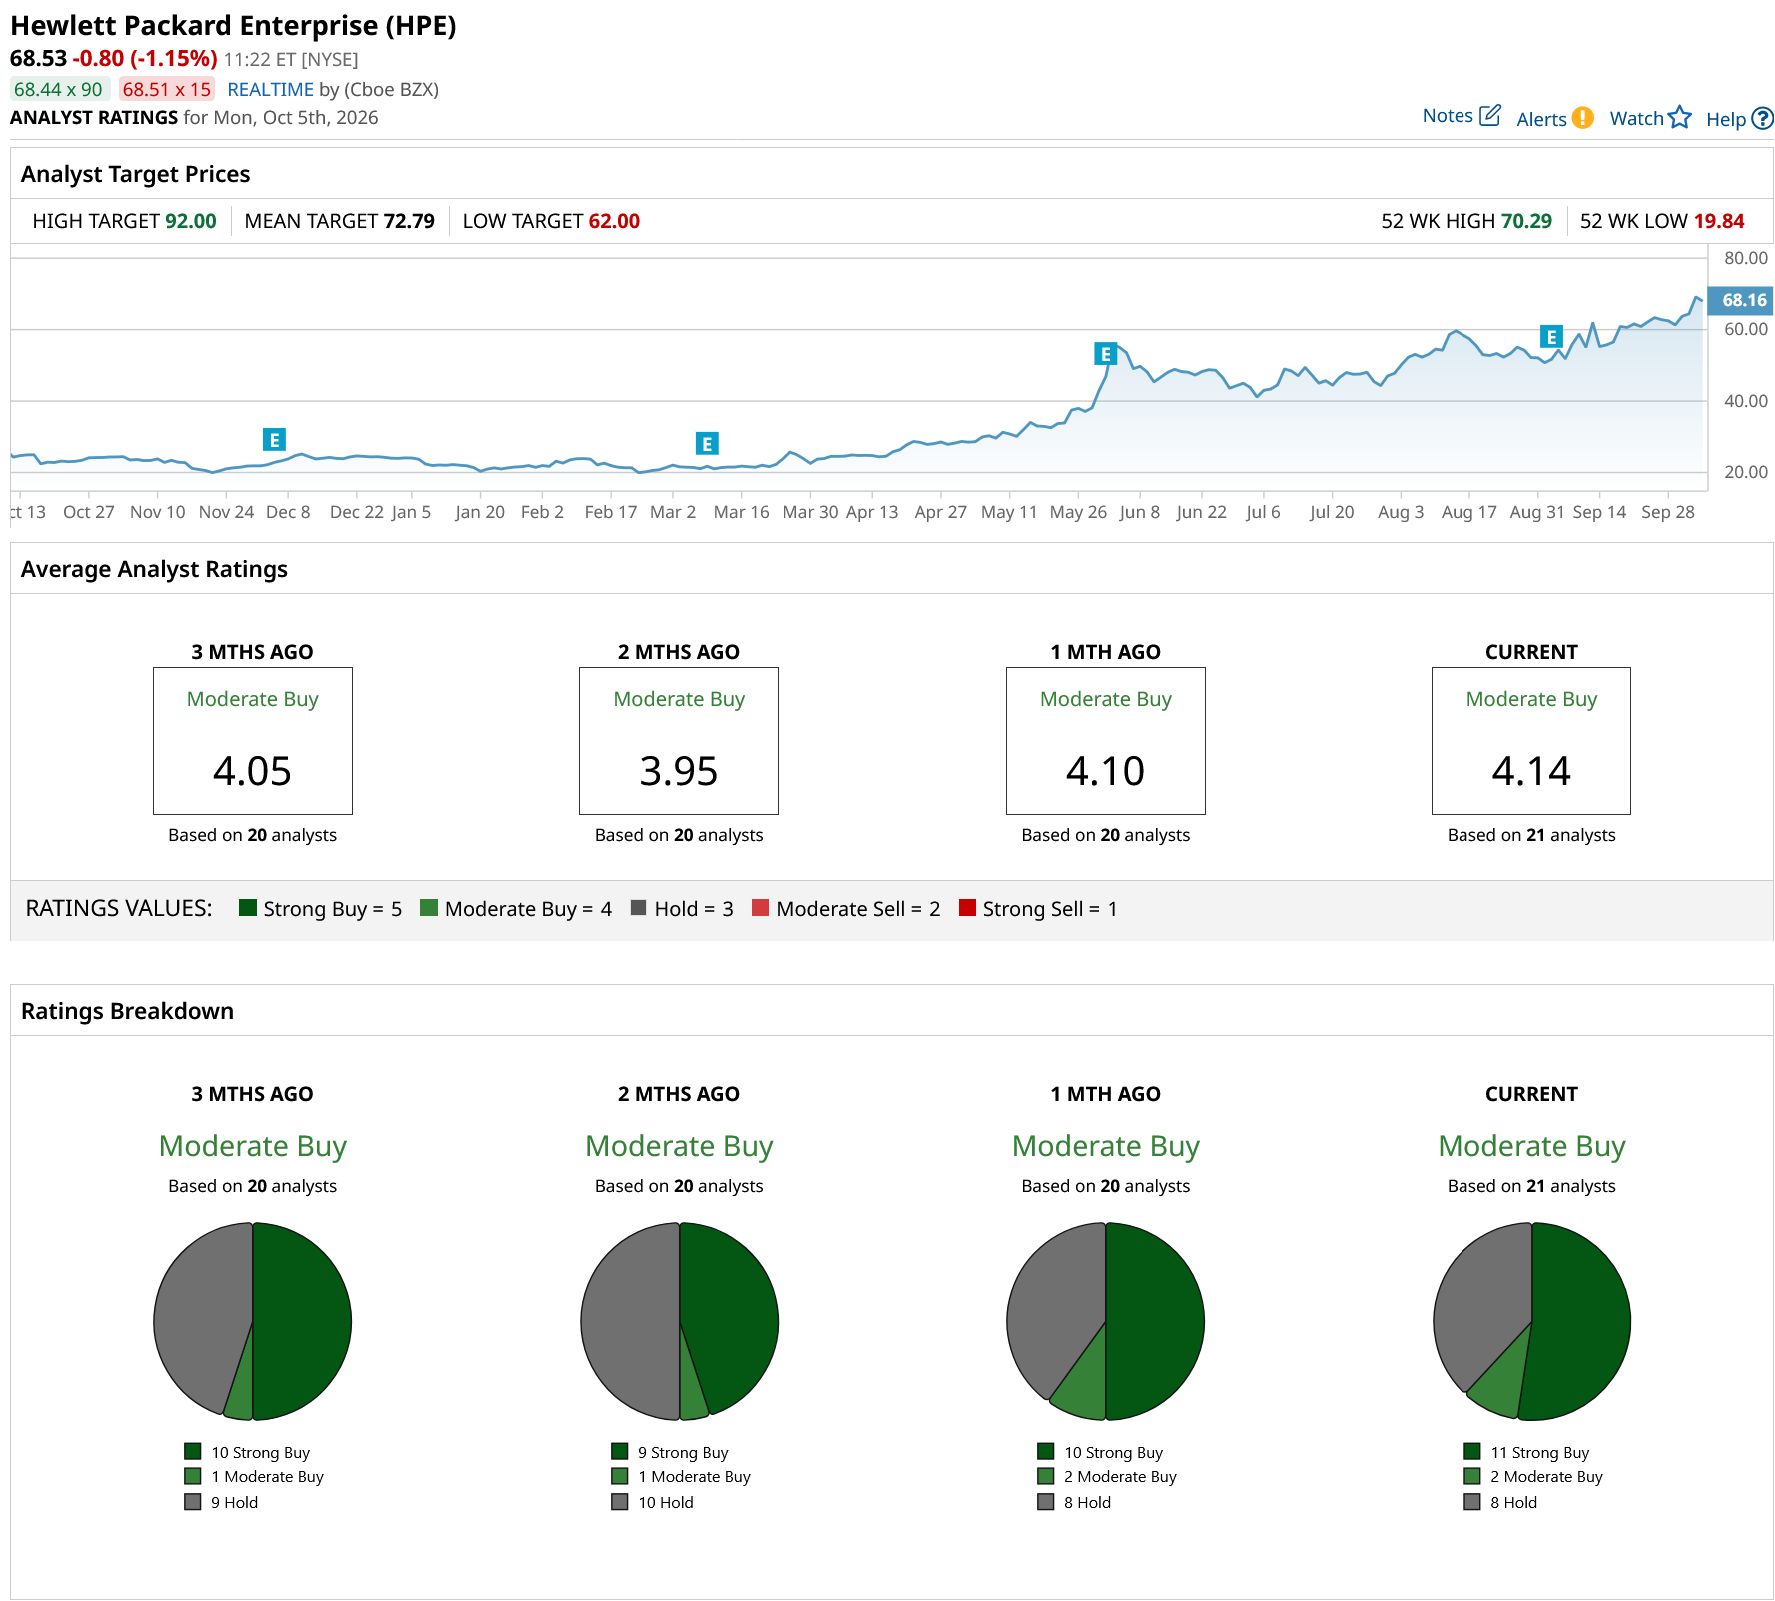
HPE stock's sharp YTD rally has raised valuation concerns, while supply constraints and near-term margin pressure keep analysts cautiously optimistic, reflected in a “Moderate Buy” consensus.
Still, strong order growth, record AI demand, a growing backlog, and upgraded FY2026 and FY2027 outlooks support the bullish case. Expanding AI spending into inference and agentic AI could further extend the infrastructure cycle, particularly in servers and networking, suggesting HPE’s rally has further room to run.
 www.barchart.com
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Amazon Wants to Offload its Nvidia Chips – And Why It Could Be Good News for AMZN Stock Why It’s Time to Load Up on HPE Stock Now 20 Planet Labs Satellites Reached Orbit. What Comes Next for PL Stock. Bank of America Put a $60 Price Target on IonQ. The Quantum Bet Is Picking Up Speed.