

San Jose, California-based PayPal Holdings, Inc. (PYPL) operates a technology platform that enables digital payments on behalf of merchants and consumers. Valued at $47 billion by market cap, the company offers online payment solutions worldwide. The fintech giant is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Oct. 27.
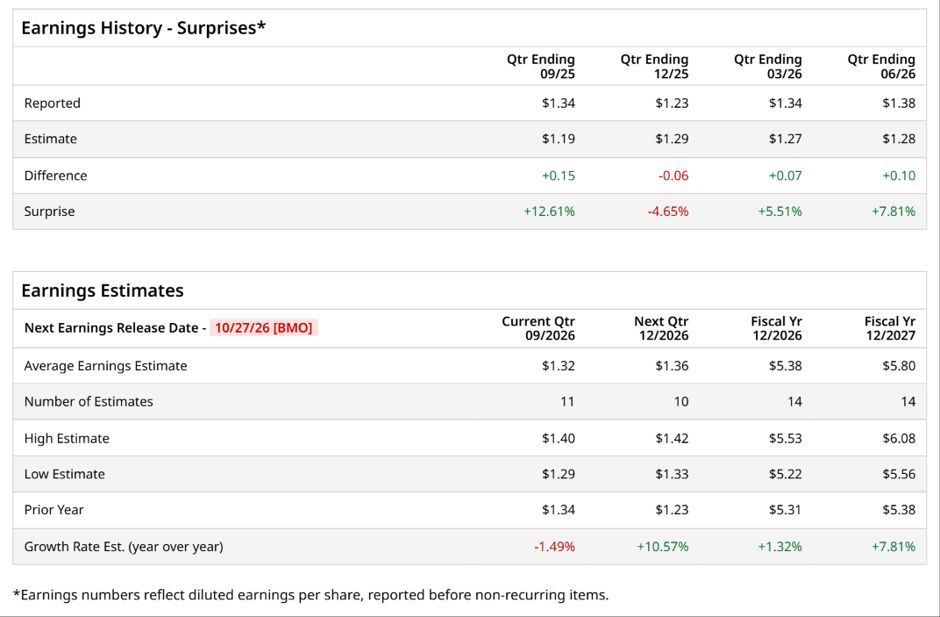
Ahead of the event, analysts expect PayPal Holdings to report a profit of $1.32 per share on a diluted basis, down 1.5% from $1.34 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect PayPal Holdings to report EPS of $5.38, up 1.3% from $5.31 in fiscal 2025. Its EPS is expected to rise 7.8% year over year to $5.80 in fiscal 2027.
 www.barchart.com
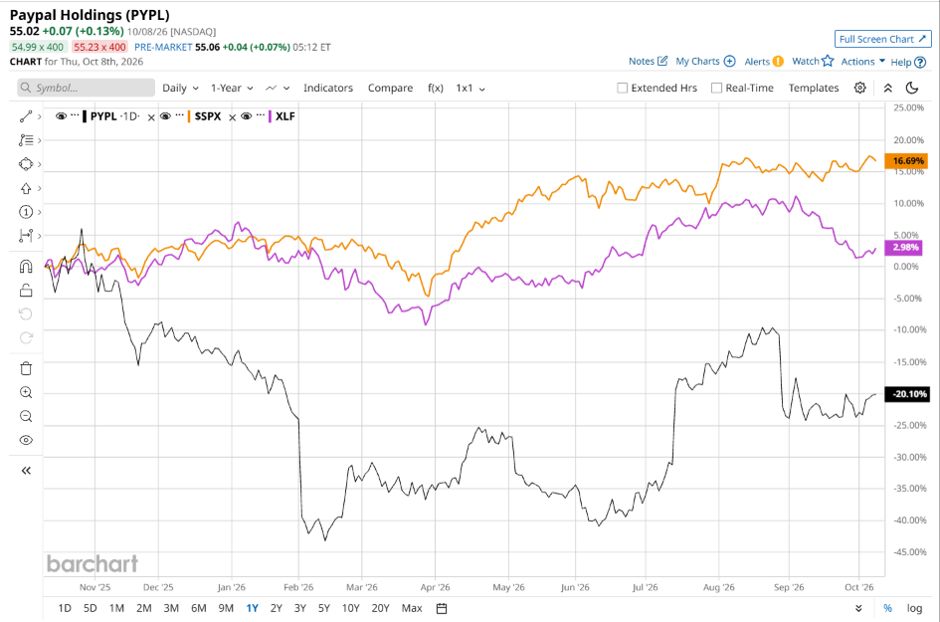
PYPL stock has notably underperformed the S&P 500 Index’s ($SPX) 15% gains over the past 52 weeks, with shares down 27.7% during this period. Similarly, it underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) 1.4% returns over the same time frame.
 www.barchart.com
PYPL has underperformed the broader market primarily due to intense competition from tech giants like Apple Inc.’s (AAPL) Apple Pay and Alphabet Inc.’s (GOOG) Google Pay, alongside a margin-squeezing product mix shift where growth is driven more by lower-margin unbranded processing rather than its highly profitable core branded checkout. This margin compression, paired with decelerating single-digit revenue growth, active account stagnation, and leadership transitions, has led Wall Street to re-evaluate PYPL as a mature payment processor rather than a high-growth tech platform.
On Jul. 28, PYPL shares closed up more than 4% after reporting its Q2 results. Its revenue stood at $8.7 billion, up 4.8% year over year. The company’s adjusted EPS declined 1.4% from the year-ago quarter to $1.38.
Analysts’ consensus opinion on PYPL stock is cautious, with a “Hold” rating overall. Out of 46 analysts covering the stock, four advise a “Strong Buy” rating, two suggest a “Moderate Buy,” 36 give a “Hold,” one advocates a “Moderate Sell,” and three recommend a “Strong Sell.” PYPL’s average analyst price target is $55.89, indicating a potential upside of 1.6% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Arista Networks Stock Is Expensive, But Don’t Count It Out Just Yet How to Play AMD Stock as It Continues to Explore a Foundry Partnership With a Korean Tech Giant With a Yield Fast Approaching 5%, Nike Says Its Dividend Is the ‘Top Priority’ Lucid Stock Might Have Bottomed, But Only Speculators Should Bet on LCID Here