

Taiwan Semiconductor Manufacturing (TSM) stock investors have one date coming that they should circle on the calendar.
On Oct. 15, after the U.S. market closes, that is when TSMC will report its third-quarter 2026 results. The setup is already getting investors attention because the company’s recent quarter has exceeded expectations, the uptick in AI customers' demand is evident, and management is expecting another solid revenue surge. The Oct. 15 report may thus be the next big sign of success in the journey of the AI semiconductor boom.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
TSMC’s prior quarter results were outstanding. Revenue surged to $40.20 billion, beating the roughly $39.94 billion consensus estimate, while ADR EPS of $4.31 topped the $3.80 Wall Street estimate. In short, sales increased 33.7% year-over-year (YoY), while diluted EPS jumped 77.4%.
AI Now Drives Two-Thirds of TSMC’s Revenue
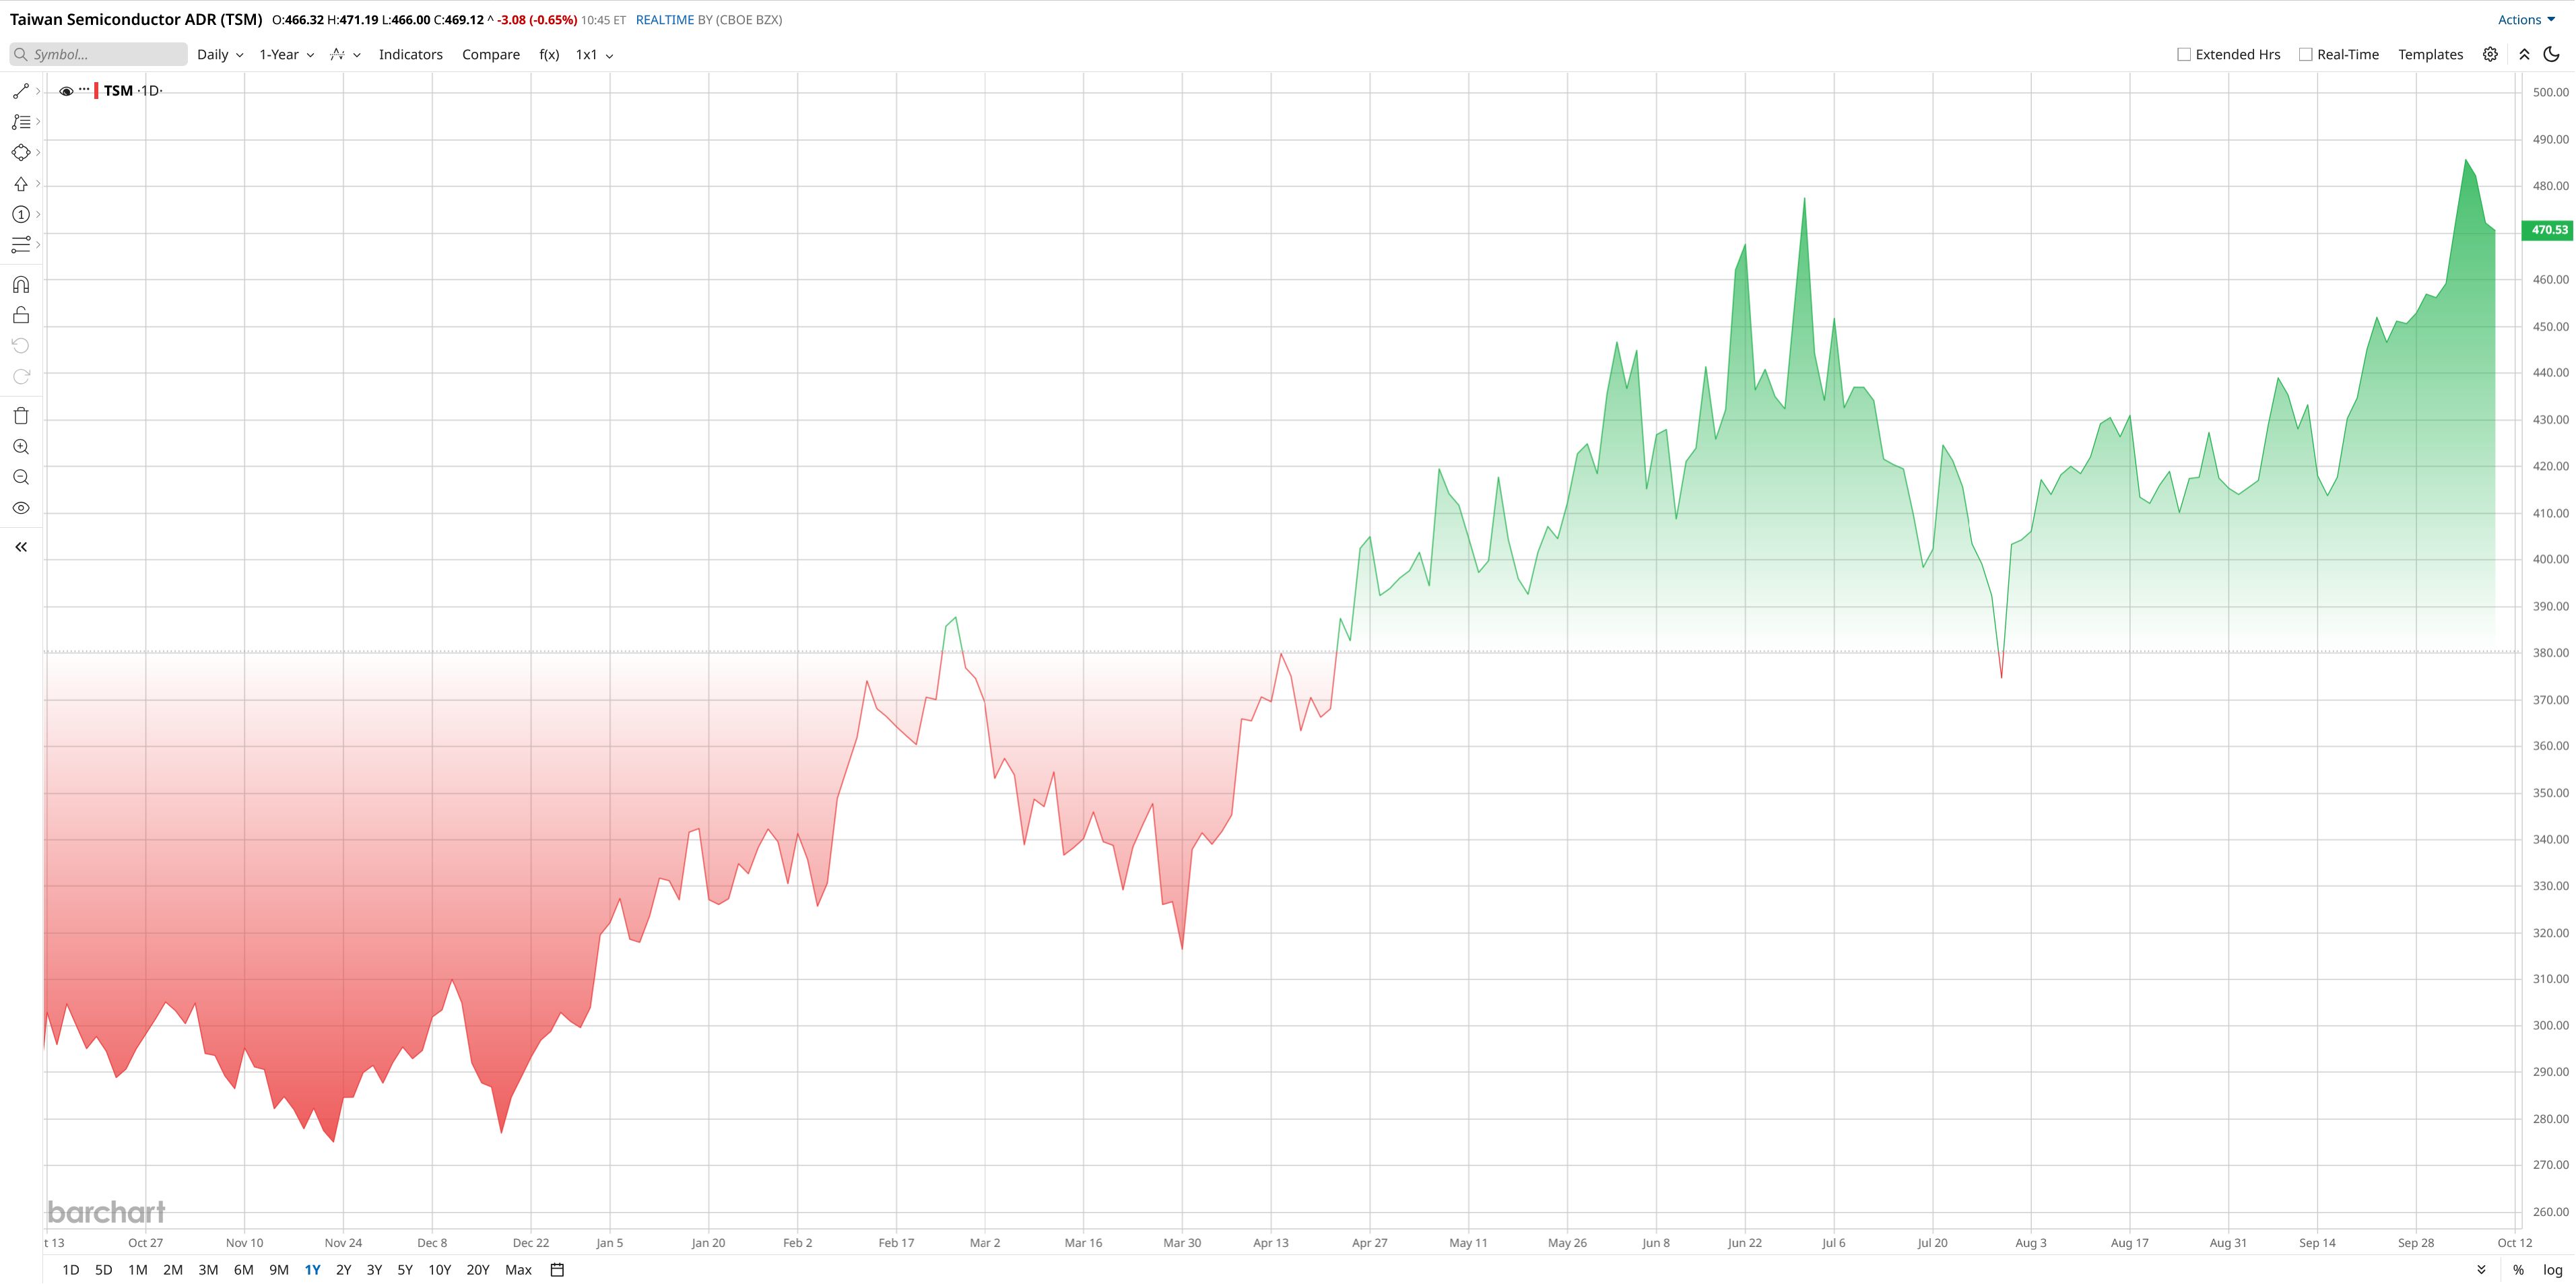
As the AI infrastructure trade continues, TSM stock has been trending upward. Shares of TSMC were flying high from the early days of the slump in 2026 and rose to 54% year-to-date (YTD). The rally shows growing demand for advanced chips, particularly from high-performance computing customers.
The numbers show just how important AI has become to the business. High-performance computing accounted for 66% of TSMC’s second-quarter revenue, up from 61% in the first quarter and 60% a year earlier. That makes the company one of the clearest ways to benefit from AI spending without betting on a single chip designer.
But please keep in mind there are risks, though. Investors are watching the cost of expanding capacity, the impact of overseas fabs on margins, and whether AI spending can remain as strong as it has been. That is why Oct. 15 earnings matter so much, which could give a clear answer.
After the bull rally, TSMC's stock has become expensive, but its valuation remains supported by rapid earnings growth. Current data put the trailing price-to-earnings (P/E) at about 34 times and the forward P/E near 21.4 times, which is quite above the sector median level. However, the PEG ratio is around 0.86, suggesting the valuation is not excessive relative to expected growth.
That can be justified because TSMC is investing heavily while simultaneously expanding profitability. The company generated a 67.7% gross margin in the second quarter and a nearly 60% operating margin, showing why investors are willing to pay a premium for its manufacturing capabilities.
 www.barchart.com
Oct. 15 Could Reset the Stock
TSMC’s Oct. 15 earnings report is more than another quarterly update. It is a chance to see whether the company can keep turning soaring AI demand into higher production, revenue, and profits.
Wall Street expects third-quarter adjusted EPS of about $4.45 per ADR and revenue of roughly $45.36 billion. Those numbers would represent another major year-over-year increase. More importantly, investors will listen for updates on 2-nanometer production, advanced packaging, customer demand, and capacity expansion.
TSMC guided for a third-quarter revenue of $44.6 billion to $45.8 billion and a gross margin of 65% to 67%. The company also raised its 2026 capital spending plan to $60 billion to $64 billion, with roughly 70% to 80% going toward advanced process technologies.
That is the bull case for the stock. If TSMC raises expectations again, shares could have more room to run. If management sounds more cautious, the market could react quickly after such a large 2026 gain.
TSMC Is Spending Big Beyond Taiwan
TSMC is also aggressively working on acquiring manufacturing facilities in the United States. It was announced in July that it intends to nearly double its planned investment in Arizona to $265 billion after committing an additional $100 billion. The expansion involves advanced packaging and research structures, and the extra fabs will be for 2-nanometer and more cutting-edge technologies.
Investment in that could lessen the geographical dispersion and move TSMC closer to major U.S. customers. In September, Reuters also reported that the firm was considering an investment in Texas but had yet to make a definite decision.
Wall Street Remains Bullish on TSM Stock
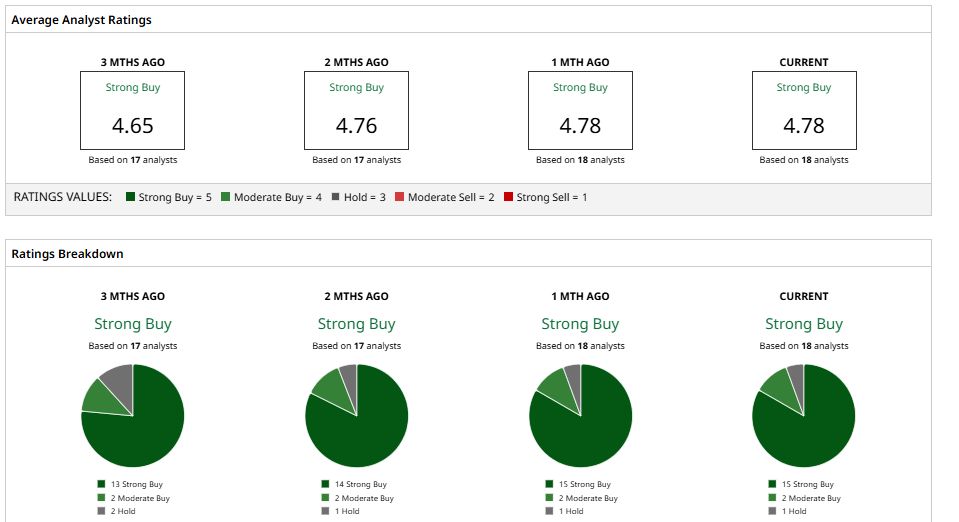
Analysts remain highly optimistic heading into Oct. 15. According to current Barchart data, 18 analysts give TSM stock a consensus “Strong Buy” rating, with an average target of $517, about 10% above the Oct. 7 close.
Separately, Stifel has a “Buy” rating with a $515 target, while Bernstein carries a “Buy” rating and a $554 target. Barclays recently raised its target to $665 from $650 and kept an “Overweight” rating.
The message from Wall Street is simply bullish. The investment community has already seen positive results and is more than happy with the growth delivered by TSMC. It's a moment Taiwan Semi stock enthusiasts will not want to overlook as it becomes the next big milestone on Oct. 15.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Taiwan Semi Stock Fans, Mark Your Calendars for October 15 SpaceX’s Terafab Probably Won’t Deliver Very High Profits, Despite Taiwan Semiconductor’s Limited Role Micron’s Taiwan Union Authorized a Strike Over a Bonus Dispute. What This Means for MU Stock. AMD Stock Is Set to Benefit From Both Physical and Agentic AI