

For decades, the F-35 has defined Lockheed Martin (LMT). Now, its order book tells a different story. At the end of June, the company’s Missiles and Fire Control (MFC) unit held $87.9 billion in backlog, nearly double its level at the start of the year. That’s well above the $54.4 billion in Aeronautics, which is the segment that builds the F-35 jet.
Lockheed Martin’s latest product launch shows it plans to build on that lead. Let's take a closer look.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Lockheed Martin Has a Missile for Every Threat
On Oct. 9, Lockheed introduced PAC-3 Edge, a faster and longer-range Patriot interceptor designed to stop hypersonic missiles. The U.S. Army has moved it into the next phase of its Future Interceptor program, with testing set for 2027.
What stands out to me is how this interceptor fits with Lockheed’s other Patriot missiles. On the second-quarter earnings call in July, CEO Jim Taiclet said that cheaper PAC-3 interceptors are needed for drones, cruise missiles, and shorter-range ballistic threats. Lockheed already offers that in its lower-cost PAC-3 ACE. With Edge at the top and ACE at the bottom, Lockheed can offer a Patriot missile at nearly every price point and threat level. That makes it harder for a rival to take market share.
The numbers show why this matters. Missiles and Fire Control sales rose 19% to $4.1 billion in Q2, driven largely by PAC-3 and THAAD production increases. MFC is also Lockheed’s most profitable segment with a 14.5% operating margin. A $35 billion multiyear THAAD contract signed in the quarter drove much of the backlog jump.
TD Cowen recently trimmed its price target slightly for LMT stock and kept a “Hold” rating, but it still expects missile framework deals to strengthen the company's defense backlog. Lockheed will report Q3 results on Oct. 22, and I’ll be watching whether that missile momentum keeps building.
About LMT Stock
Lockheed Martin is one of the world’s largest aerospace and defense companies. It designs, builds, and supports military aircraft, missiles, helicopters, satellites, space systems, and other advanced defense technologies for the U.S. government and allied countries around the world. Lockheed created the ultra-high-altitude U-2 and the hypersonic SR-71 Blackbird, which are among the fastest planes ever built. Headquartered in Bethesda, Maryland, the company is best-known for producing advanced military and aerospace technology used in national defense and security.
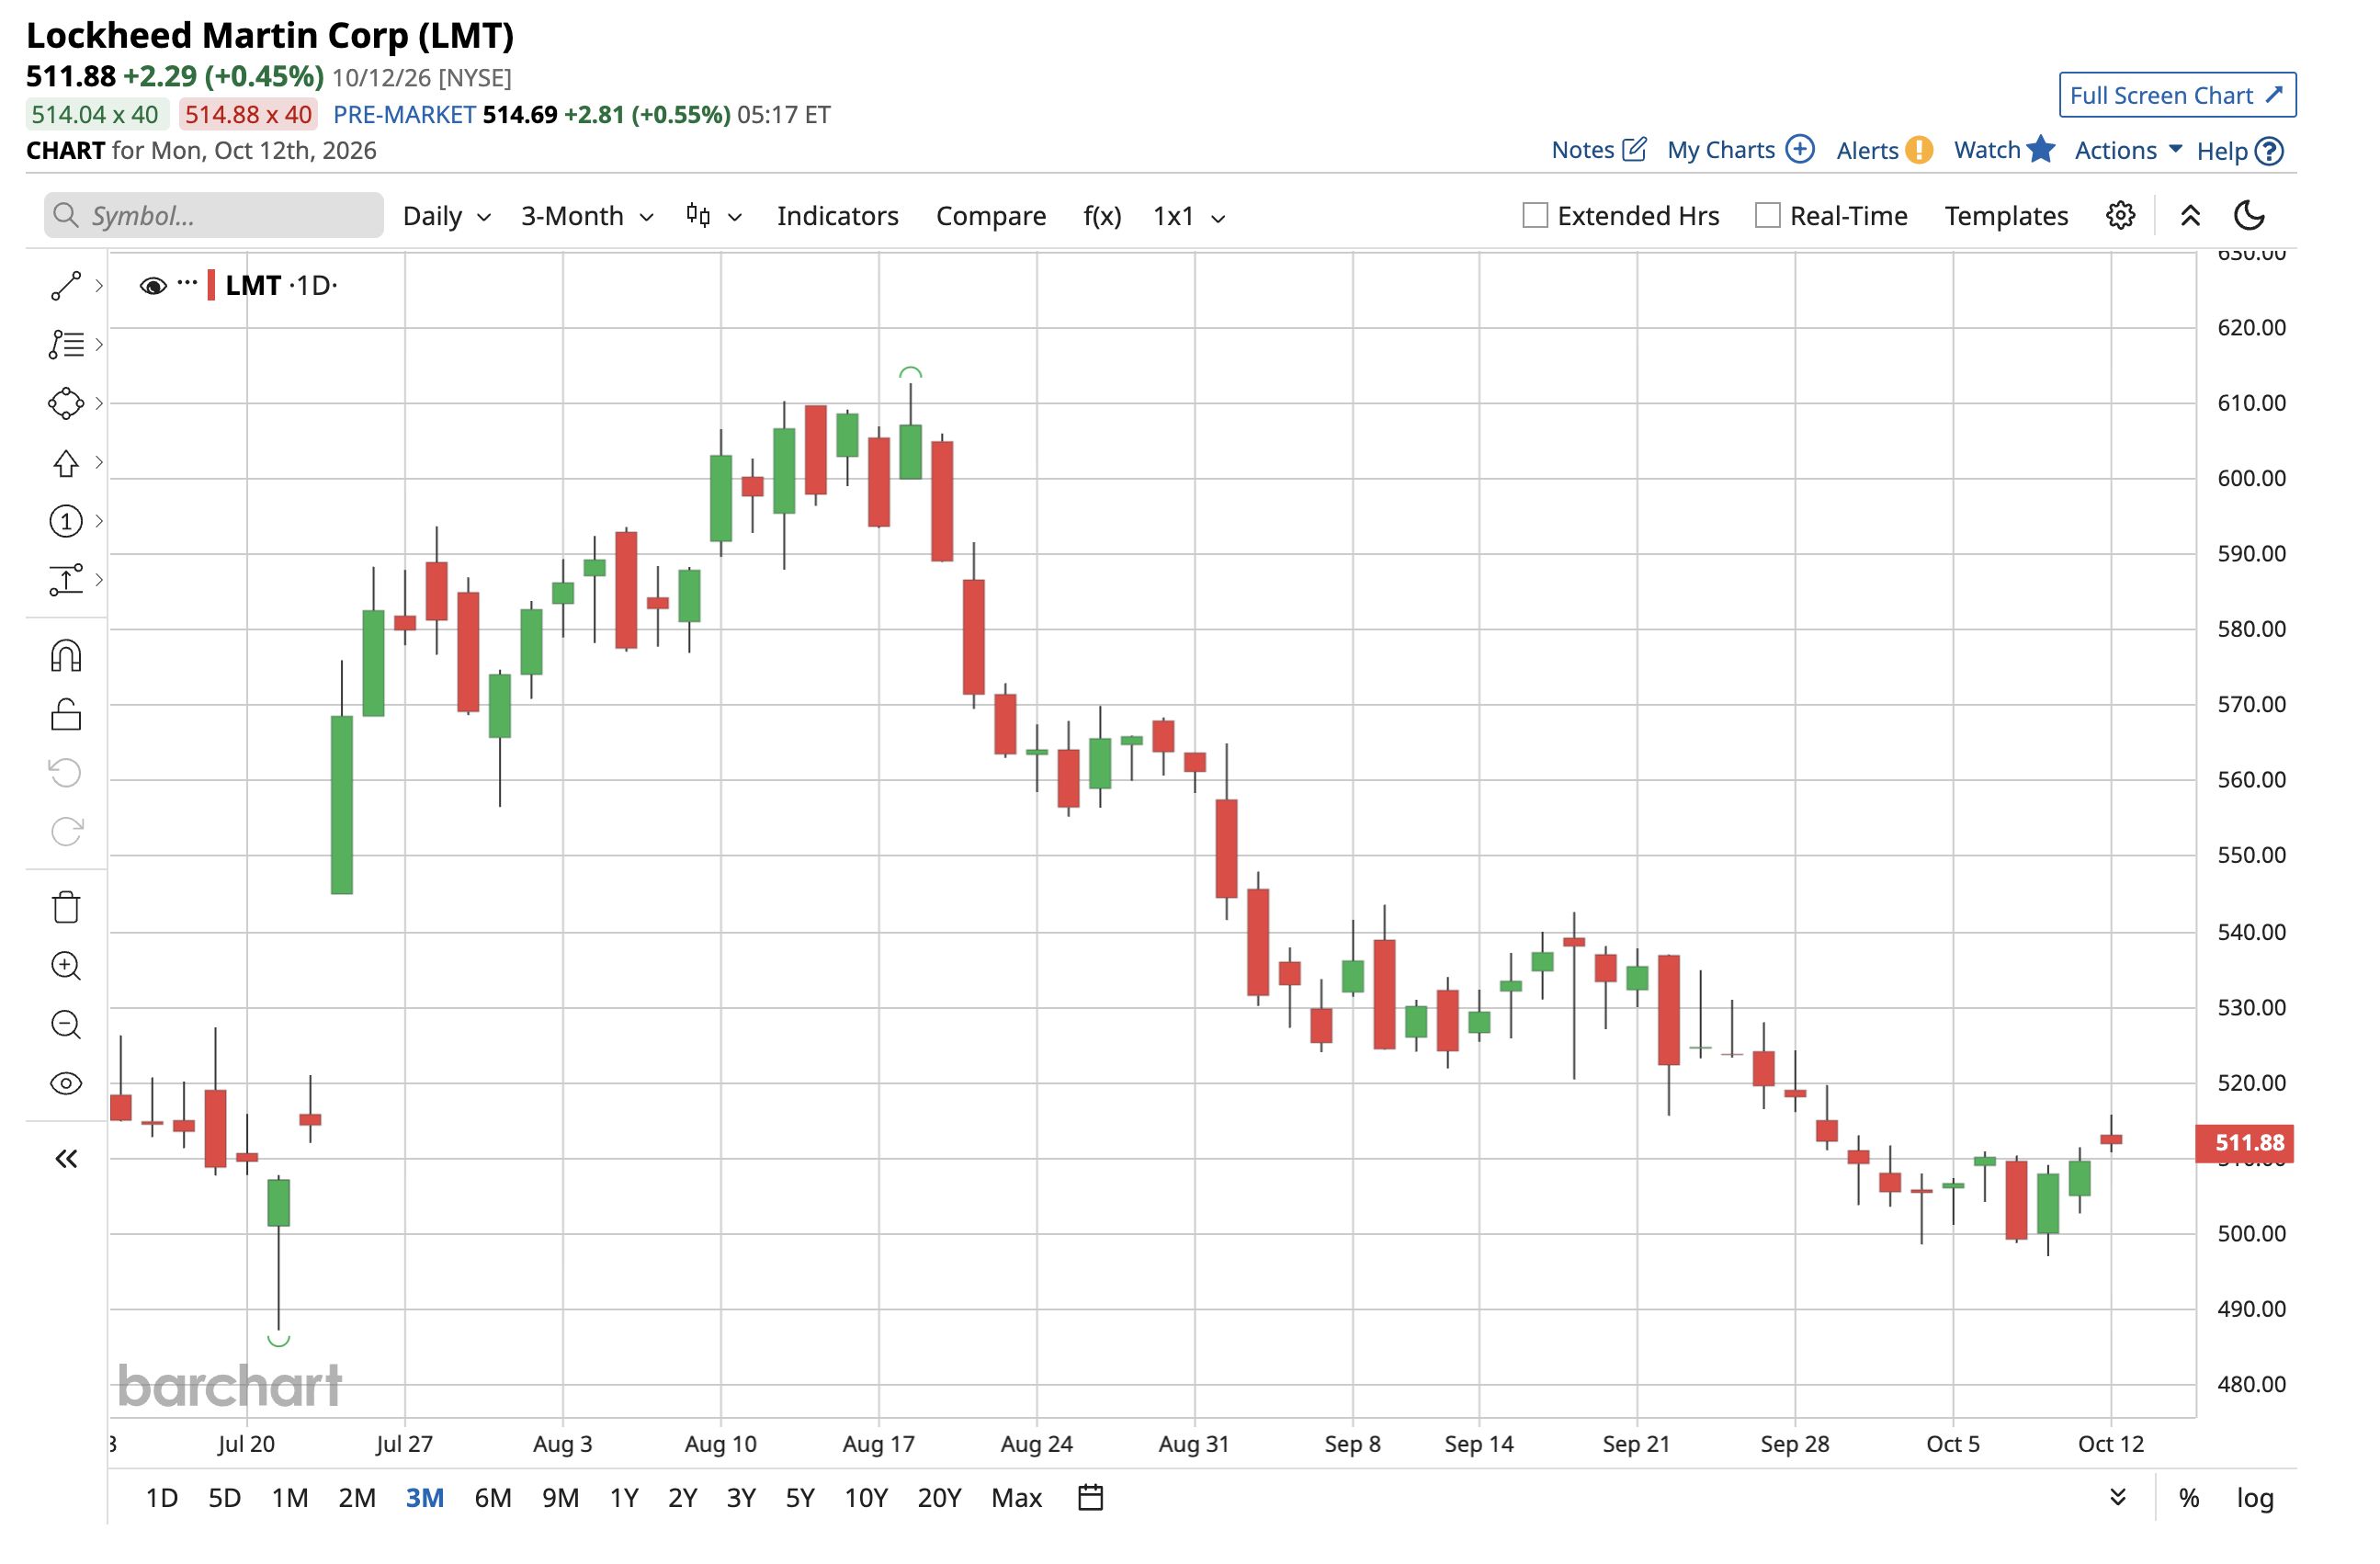
Over the past year, LMT stock has climbed 12%, outperforming the iShares U.S. Aerospace & Defense ETF’s (ITA) climb of 1.3% during the same period. The trend has continued for shares this year, with the stock up 14% year-to-date (YTD) versus the ITA's drop of nearly 3%. LMT stock has been fairly volatile, climbing from roughly $517 at the start of July to as high as $613 by mid-August before falling again. Shares now trade near the $552 mark.
 www.barchart.com
Lockheed Martin stock trades below its historical norms on both key measures. The forward price-to-earnings (P/E) ratio of 17.1 times sits just below its five-year average, while the price-to-sales (P/S) ratio of 1.6 times is also slightly below its norm.
Analysts see EPS rising about 7% in fiscal 2026 and 8% in fiscal 2027. Total debt of $20.5 billion against $3.8 billion in cash leaves about $16.7 billion in net debt. However, Lockheed’s raised free cash flow guidance of $7 billion to $7.2 billion can comfortably support that.
The company's overall growth looks modest, but if missile demand keeps building, today's multiples could prove cheap in hindsight.
What Do Analysts Expect for LMT Stock?
TD Cowen recently lowered its price target on LMT stock from $600 to $570 while keeping a “Hold” rating. The firm reportedly adjusted its targets for aerospace and defense companies ahead of their respective Q3 earnings reports. In addition, Barclays recently initiated coverage of LMT stock with an “Equal-Weight” rating and a $554 price target.
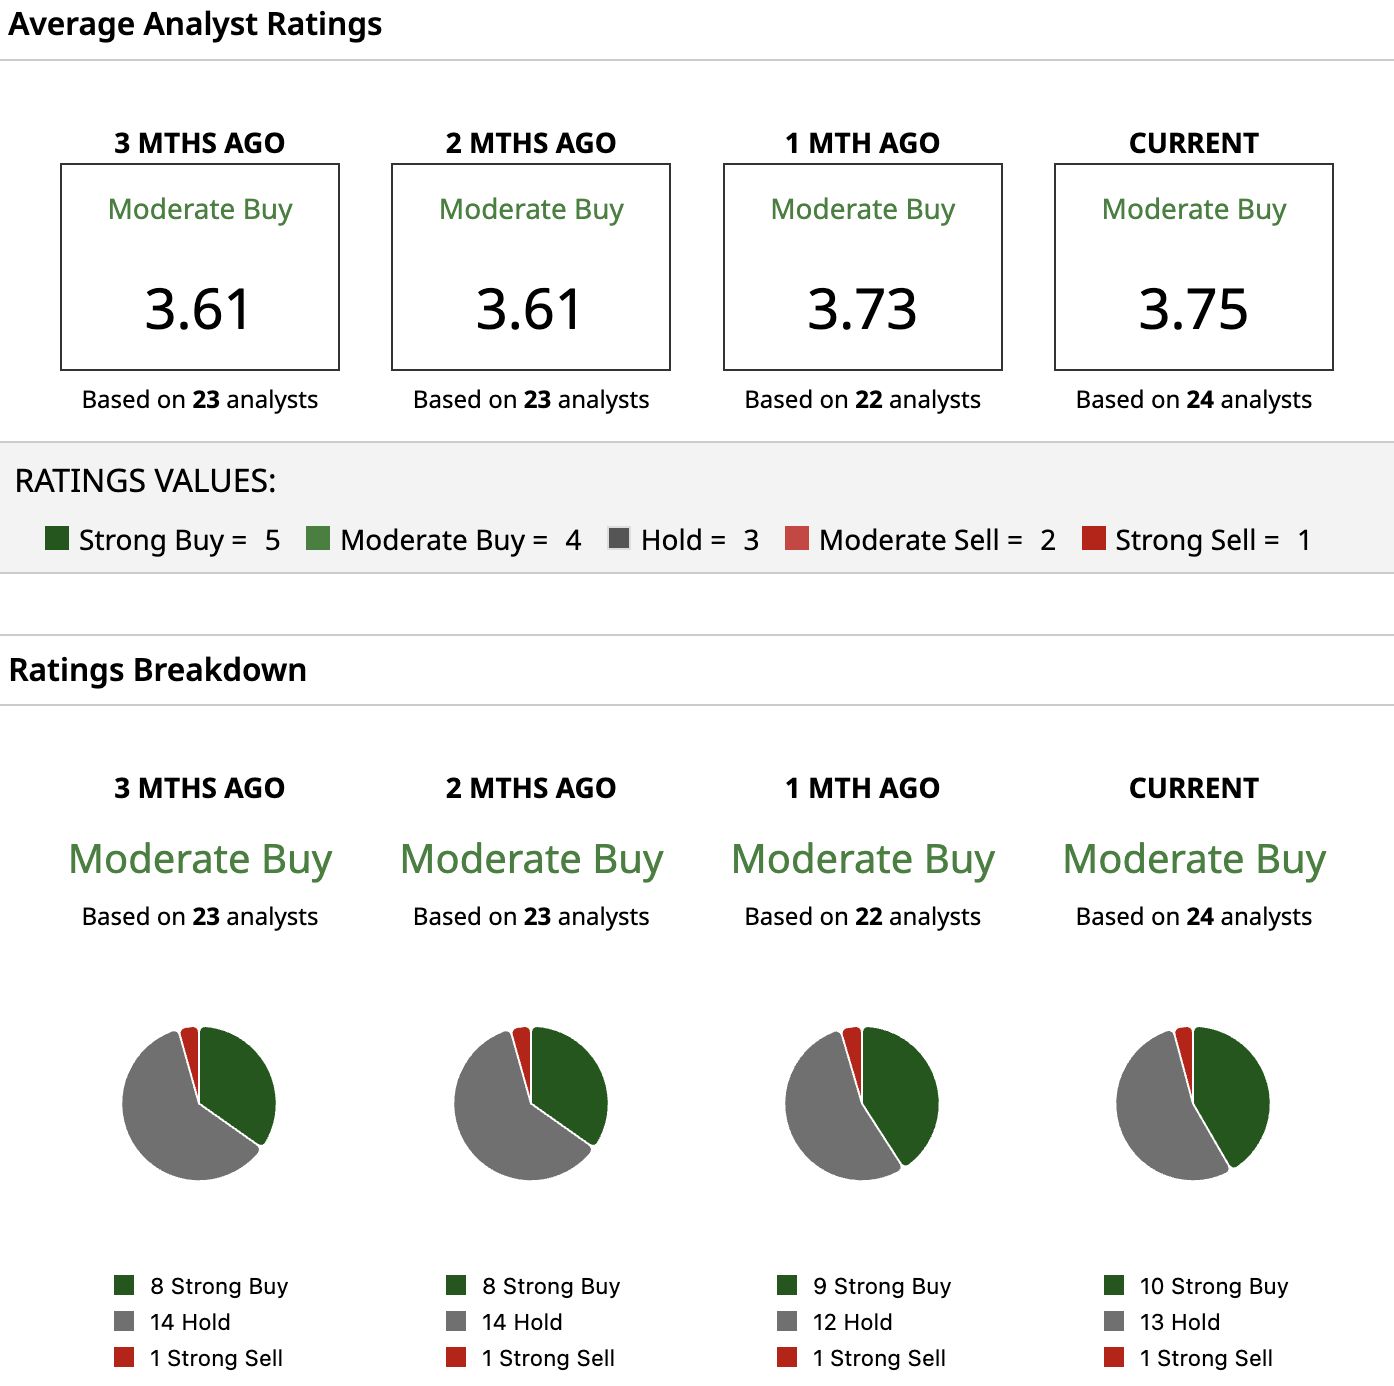
Based on 24 analysts covering the stock, Lockheed Martin holds a consensus “Moderate Buy” rating on Wall Street. The mean price target of $626.65 reflects potential upside of 14% from current levels. The low price target of $486 sits below current levels, while the high price target of $775 implies additional potential upside of 40% from here.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Lockheed Martin's $88 Billion Missile Backlog Could Be a Reason to Buy Before October 22 Applied Materials Just Opened a $5 Billion R&D Center. What That Actually Means for AMAT Stock. PEP Stock Alert: KFC Just Dealt PepsiCo a Blow With New Coca-Cola Deal What Were Markets Telling Us at Friday's Close?