

Milford, Massachusetts-based Waters Corporation (WAT) is a leading analytical instruments and life sciences technology company that develops, manufactures, and services laboratory equipment, software, and consumables used in pharmaceutical research, drug development, clinical diagnostics, and food and environmental safety testing. With a market cap of $42.9 billion, the company specializes in liquid chromatography, mass spectrometry, thermal analysis, and rheometry technologies that help scientists identify chemical compounds, measure material properties, and assess product quality.
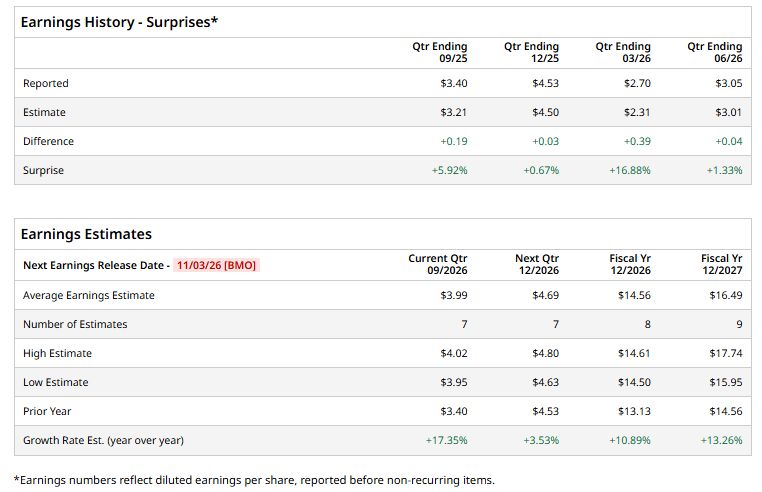
The global analytical instrumentation leader is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Nov. 3. Ahead of the event, analysts expect WAT to report a profit of $3.99 per share on a diluted basis, up 17.4% from $3.40 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the current year, analysts expect WAT to report EPS of $14.56, up 10.9% from $13.13 in fiscal 2025. Its EPS is expected to rise 13.3% year over year to $16.49 in fiscal 2027.
 www.barchart.com
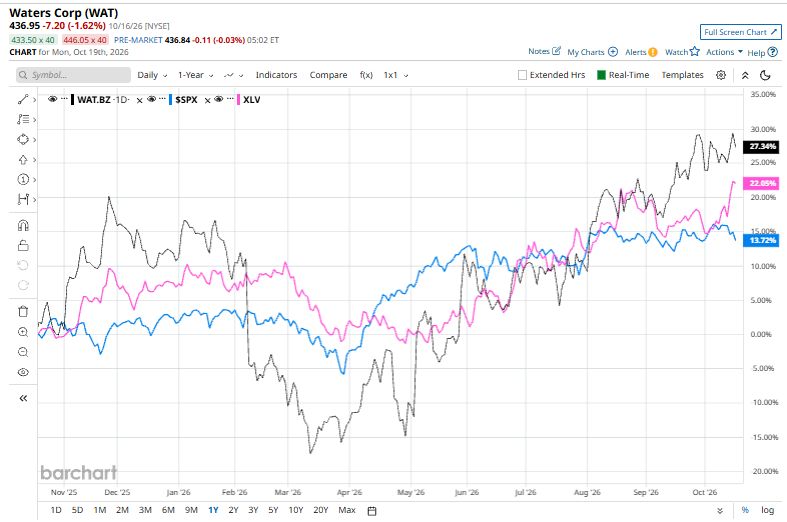
WAT stock has outperformed the S&P 500 Index’s ($SPX) 15.5% gains over the past 52 weeks, with shares up 30.5% during this period. Similarly, it underperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 24.2% returns over the same time frame.
 www.barchart.com
Waters Corporation has outpaced the broader market over the past year, supported by expectations of accelerating demand and robust revenue growth. The company’s strong free cash flow generation provides financial flexibility to reinvest in growth opportunities, while its high returns on capital reflect efficient management and the ability to pursue profitable business ventures.
Analysts’ consensus opinion on WAT stock is reasonably bullish, with a “Strong Buy” rating overall. Out of 23 analysts covering the stock, 16 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” and six give a “Hold.” WAT’s average analyst price target is $465.65, indicating a potential upside of 6.6% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Taiwan’s President Called on Micron and Workers to Negotiate Ahead of a Possible Strike. Here’s What to Know. Rocket Lab's Biggest Technological Advantage Is Fast Becoming Its Biggest Problem Venture Global Stock Just Secured a Data Center Win. How to Play It Here. SanDisk Stock Is Caught in the China Chip Selloff. Here’s What Investors Are Missing.