

Super Micro Computer (SMCI) is entering a new chapter in its financial leadership as the AI server producer has appointed Mark Long as its new senior vice president and Chief Financial Officer, effective Oct. 15. Long, a former CFO and Chief Strategy Officer at Western Digital Corporation (WDC), replaces David Weigand after Supermicro spent nearly two years searching for a new finance chief amid heightened scrutiny of its accounting, governance, and internal controls.
The appointment comes at a critical time for Supermicro, which continues to benefit from strong demand for artificial intelligence (AI) infrastructure but is also working to rebuild investor confidence following a series of governance and export-control controversies.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The company is seeing steady top-line growth, underscoring the strength of its AI opportunity. So, will Long’s appointment improve financial execution and transparency while allowing Supermicro to capitalize on surging AI data center spending?
About Super Micro Stock
Super Micro Computer is a San Jose, California-based technology company that designs, develops, and manufactures application-optimized servers, storage, and networking solutions for AI, cloud computing, enterprise, and other demanding workloads. The company has built a broad portfolio spanning GPU-optimized servers, rack-scale systems, storage platforms, motherboards, and liquid-cooling technologies, positioning it as a key infrastructure supplier benefiting from growing AI data center spending. It has a market cap of $20.8 billion.
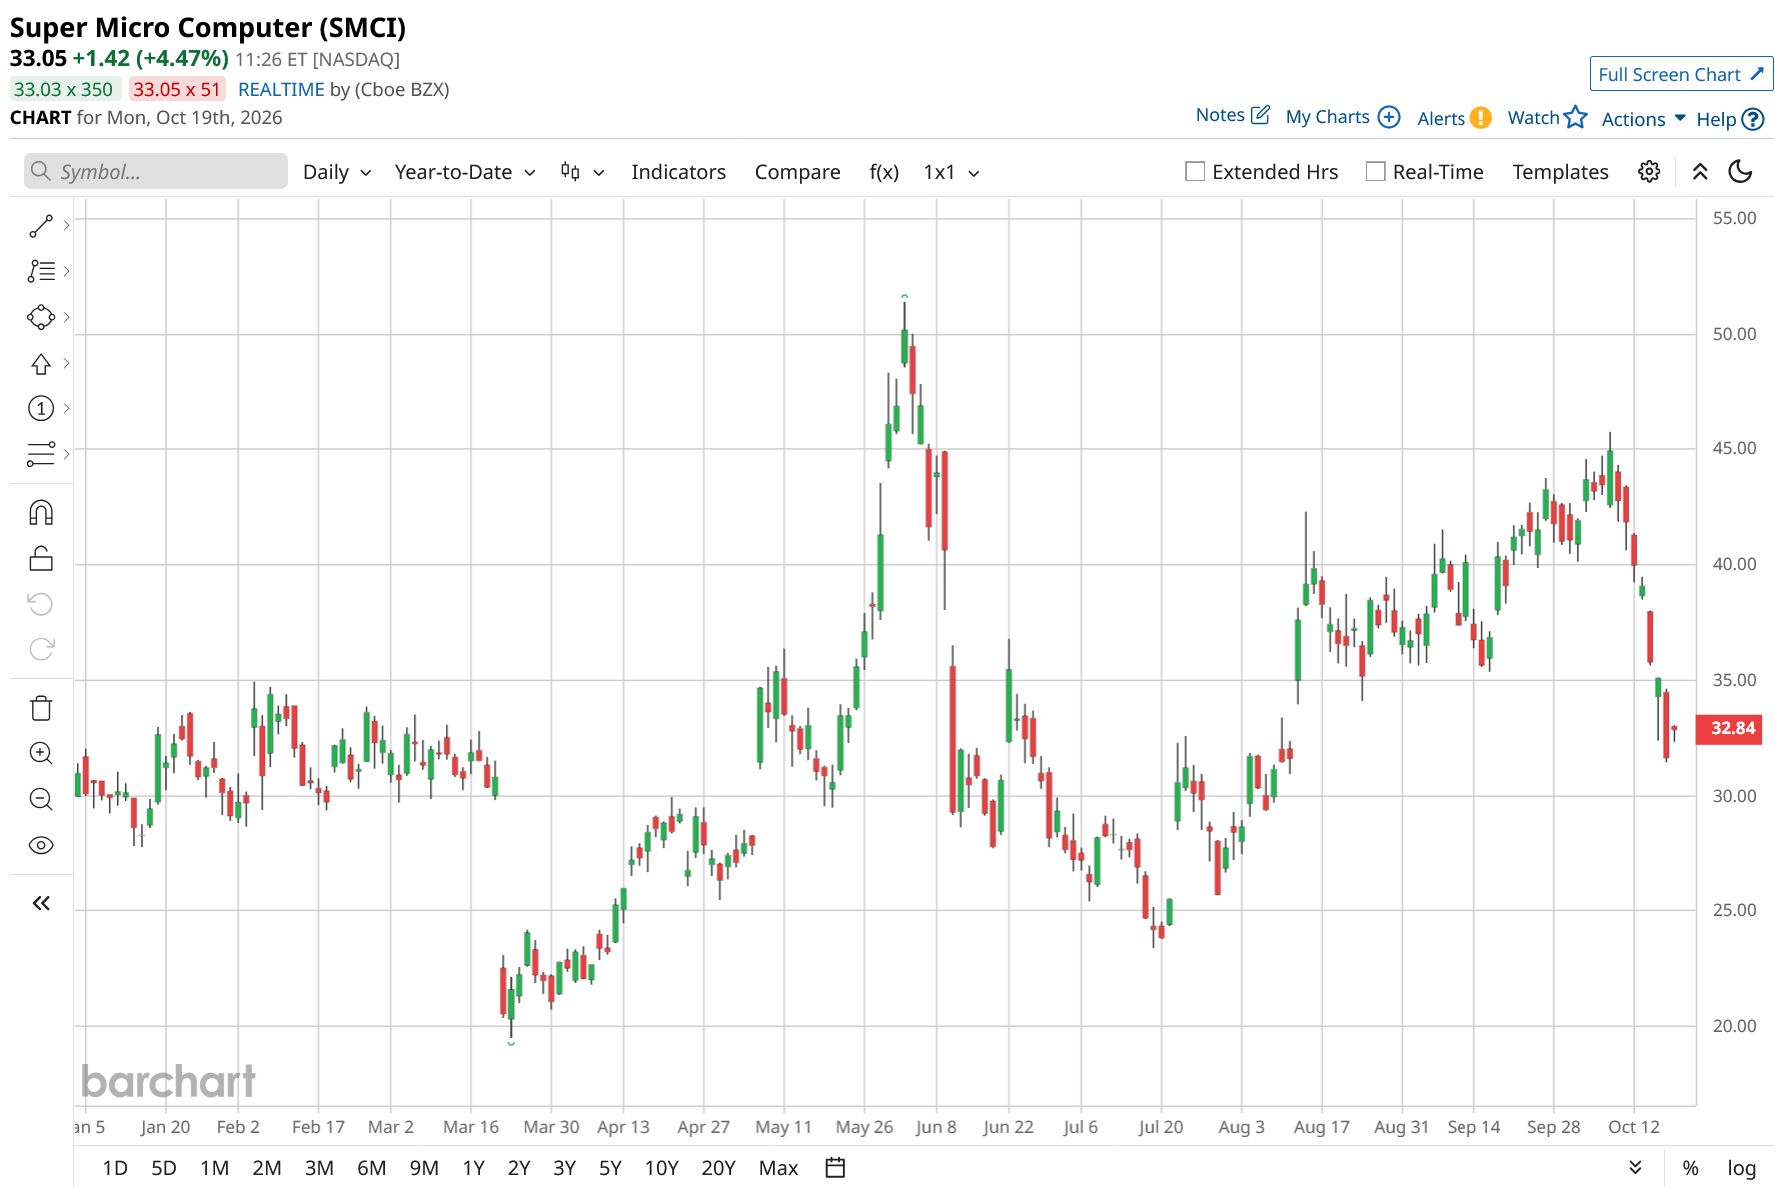
SMCI stock has come under significant pressure in recent trading, despite remaining modestly higher on a year-to-date (YTD) basis. Shares are down 37% over the past year but still up 8.1% year-to-date (YTD), reflecting the stock’s sharp volatility as investors weigh the company’s strong AI-server growth opportunity against concerns about execution, cash generation, and regulatory risks.
The pressure has intensified in recent sessions, with SMCI slumping 18% over the past five trading days, including a 9.9% plunge in the latest session on Oct. 16, when shares closed at $31.63.
The latest selloff comes amid broader weakness in AI and semiconductor stocks as investors have become more cautious about the sustainability and profitability of massive AI infrastructure spending. Plus, the appointment of Mark Long as CFO, following nearly two years of searching for a permanent finance chief, highlights the company’s effort to strengthen financial oversight and execution after earlier concerns about accounting, governance and internal controls, but legal and export-control issues involving former employees and contractors have continued to weigh on investor sentiment.
These concerns have overshadowed Supermicro’s strong AI demand outlook, leaving SMCI investors focused on whether the company can convert its substantial AI opportunity into sustainable earnings and cash flow.
In terms of valuation, SMCI stock is priced at 8.91 times forward earnings and 0.59 times sales, trading at a discount compared to the sector peers.
 www.barchart.com
Financials Show a Positive Picture
SMCI reported its fourth-quarter and full fiscal year 2026 financial results on Aug. 11, for the fiscal year ended June 30. The company delivered a major acceleration in its fourth-quarter performance, with net sales rising 91.4% year-over-year (YoY) to $11.1 billion.
Gross profit surged 257% to $1.9 billion, while gross margin expanded sharply to 17.5% from 9.5% in Q4 FY2025. Non-GAAP gross margin was 17.6%, versus 9.6% a year earlier. Operating income jumped 551.5% to $1.5 billion, while net income increased 503.7% to $1.2 billion. Its non-GAAP EPS increased to $1.70 from $0.41. The company also generated $747 million in operating cash flow during the quarter.
For the full fiscal year, Supermicro’s results also showed substantial growth. Fiscal 2026 net sales increased 77.7% to $39.1 billion. Gross profit climbed 74% YoY to $4.2 billion, although full-year gross margin slipped to 10.8% from 11.1%. Operating expenses increased 23.8% to $1.5 billion, while operating income more than doubled, rising 121.1% to $2.77 billion from $1.3 billion.
On a non-GAAP basis, net income attributable to common stockholders increased to $2.5 billion from $1.3 billion, and non-GAAP EPS rose 76.2% to $3.63.
Despite the strong earnings growth, cash flow remained an important concern. Supermicro’s rapid expansion required significant investment, resulting in substantial operating cash consumption earlier in the year. The company nevertheless ended fiscal 2026 with $7.5 billion of cash and cash equivalents, while total bank debt and convertible notes stood at $8.7 billion.
Furthermore, for the first quarter of fiscal 2027, Supermicro expects revenue of $14.5 billion to $15.5 billion and non-GAAP EPS of $1.01 to $1.10. For the full fiscal year 2027, management expects revenue of $65 billion to $72 billion. The outlook is supported by more than $60 billion in new orders generated during Q4 and a record backlog entering the new fiscal year. Management also said that a richer enterprise customer mix and wider adoption of its Data Center Building Block Solutions architecture should help improve profitability.
Analysts project EPS to rise by 20.9% to around $3.94 for fiscal 2027, while the consensus estimate of $4.90 for fiscal 2028 indicates a rise by 24.4%.
What Do Analysts Expect for SMCI Stock?
This month, Bernstein analyst Mark Newman reiterated a “Hold” rating on SMCI stock while maintaining a $42 price target, as Bernstein remains cautious on the stock’s risk-reward profile despite its significant AI infrastructure opportunity. Supermicro continues to benefit from strong demand for AI servers and data center infrastructure, but investors are also weighing execution, profitability, governance, and competitive risks.
Furthermore, Citigroup maintained its “Neutral” rating on Supermicro but raised its price target to $45 from $39.
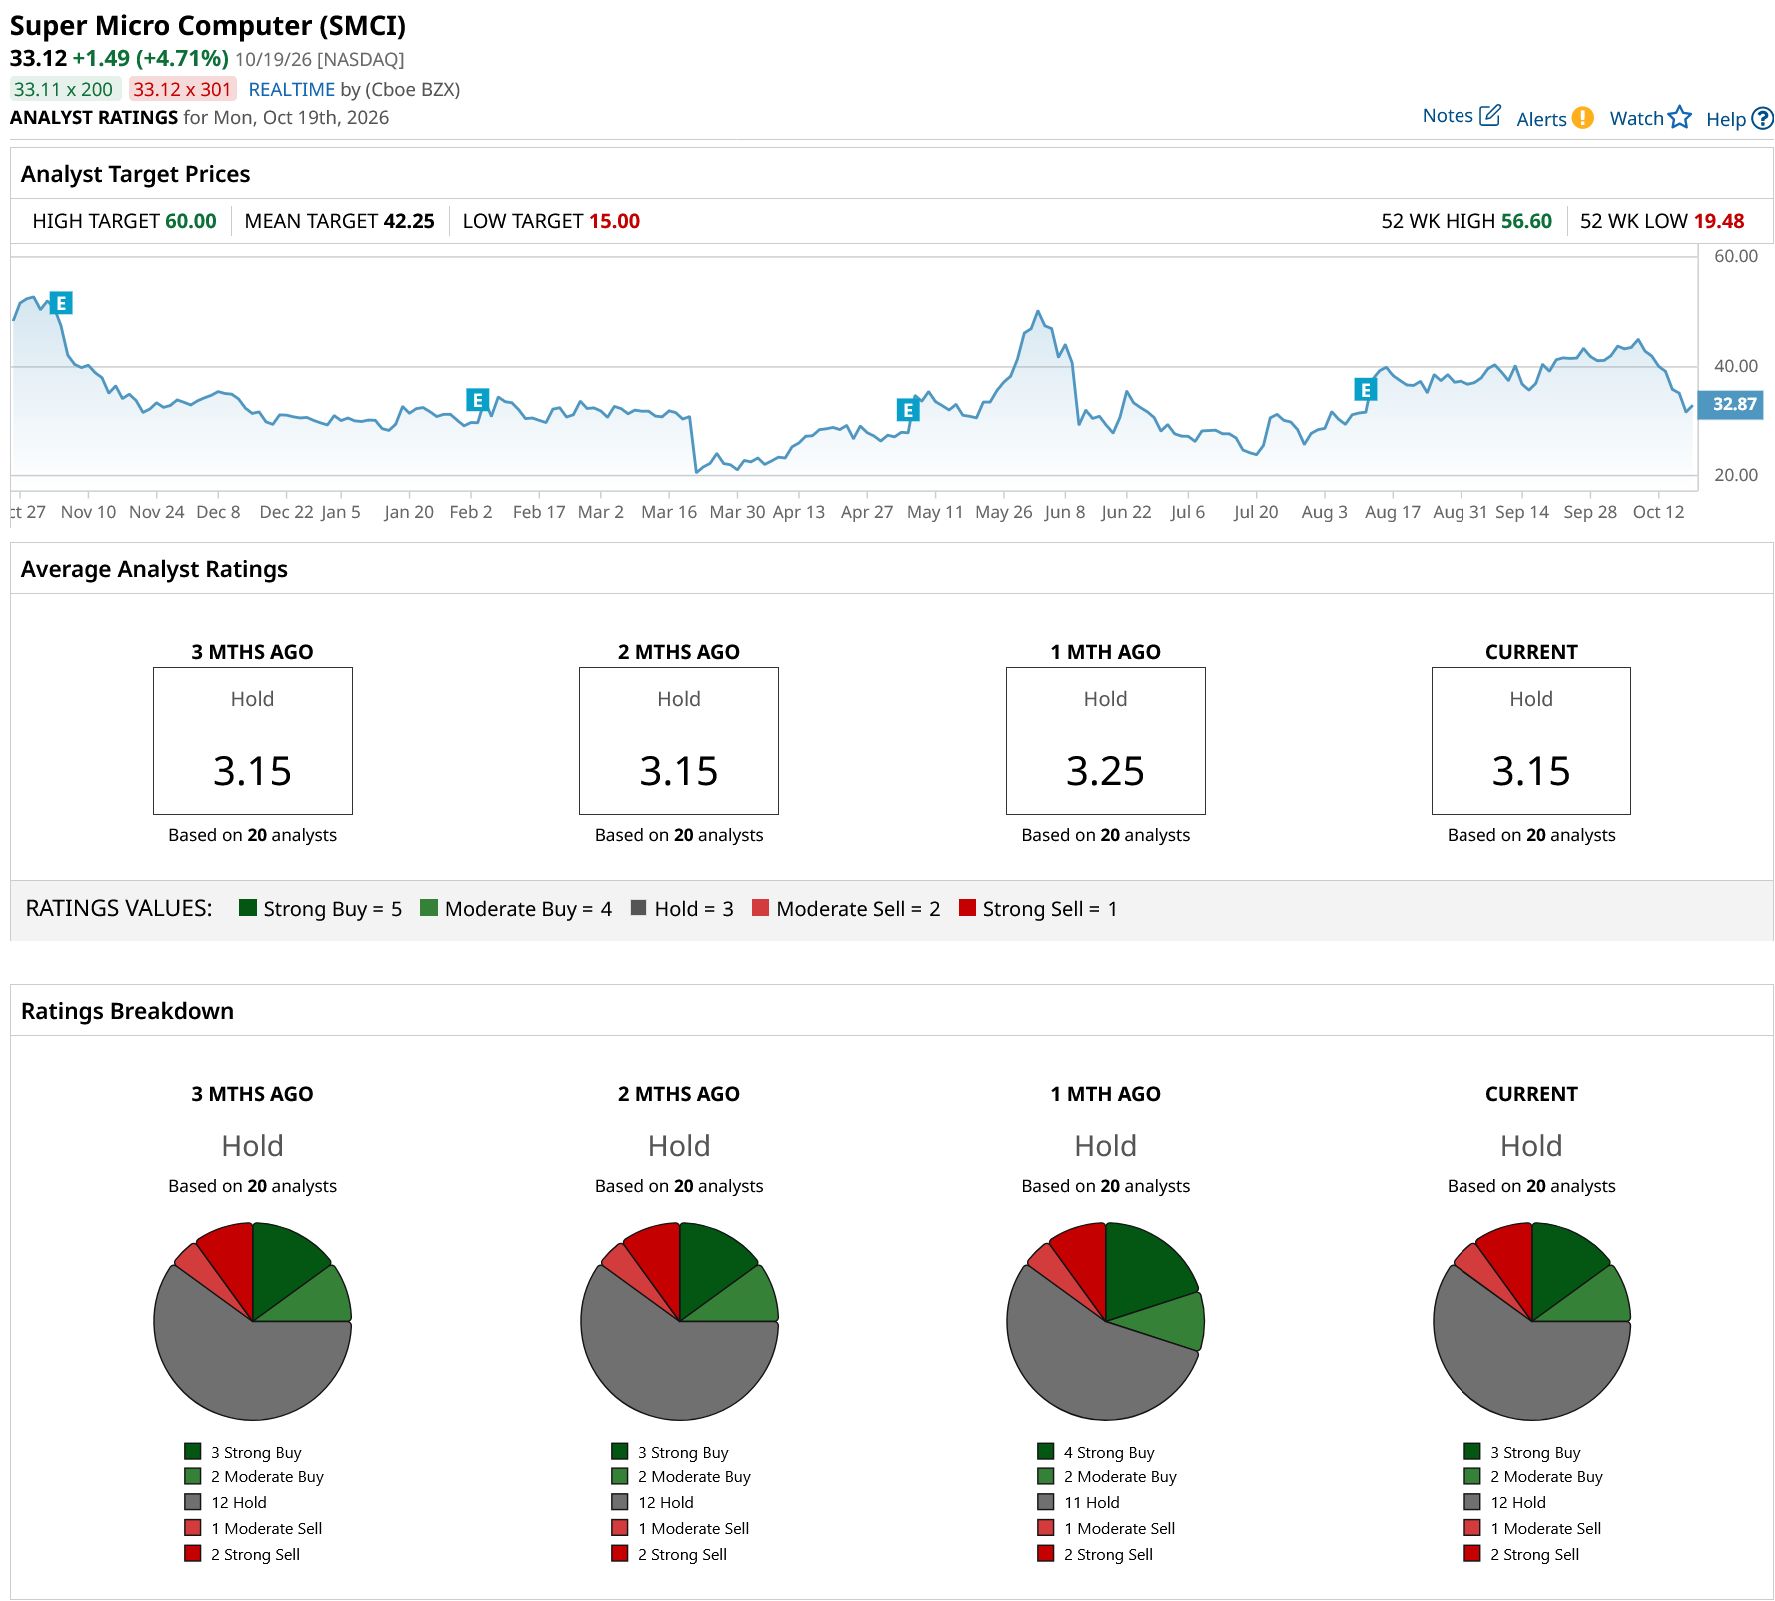
SMCI stock has a consensus “Hold” rating overall, signaling caution. Out of 20 analysts covering the tech stock, three recommend a “Strong Buy,” two give a “Moderate Buy,” 12 analysts stay cautious with a “Hold” rating, one offers a “Moderate Sell,” and two have a “Strong Sell” rating.
The average analyst price target for SMCI is $42.25, indicating a potential upside of 28%. The Street-high target price of $60 suggests that the stock could rally as much as 81%.
 www.barchart.com
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Freshworks Stock Has Strong Momentum at New 52-Week Highs, But There’s 1 Reason for Caution Elon Musk Is Coming for Your Phone Bill. Here's What Has to Go Right First. Super Micro Is Getting a New CFO. What That Means for SMCI Stock. Jamie Dimon Just Listed 5 Market Risks Hiding 'Under the Surface.' JPMorgan Is Already Feeling The Heat.