

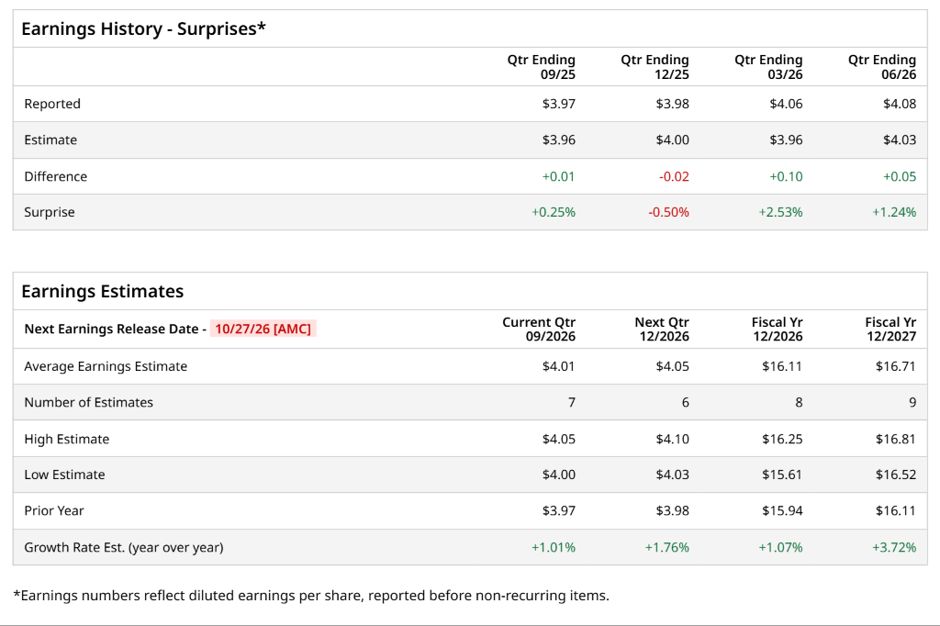
San Mateo, California-based Essex Property Trust, Inc. (ESS) acquires, develops, redevelops, and manages multifamily residential properties in selected West Coast markets. With a market cap of $17.6 billion, the company has ownership interests in 256 apartment communities comprising over 62,000 apartment homes with an additional property in active development. The fully integrated REIT is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Tuesday, Oct. 27.
Ahead of the event, analysts expect Essex Property Trust to report an FFO of $4.01 per share on a diluted basis, up 1% from $3.97 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Essex Property Trust to report FFO of $16.11 per share, up 1.1% from $15.94 in fiscal 2025. Its FFO is expected to rise 3.7% year over year to $16.71 per share in fiscal 2027.
 www.barchart.com
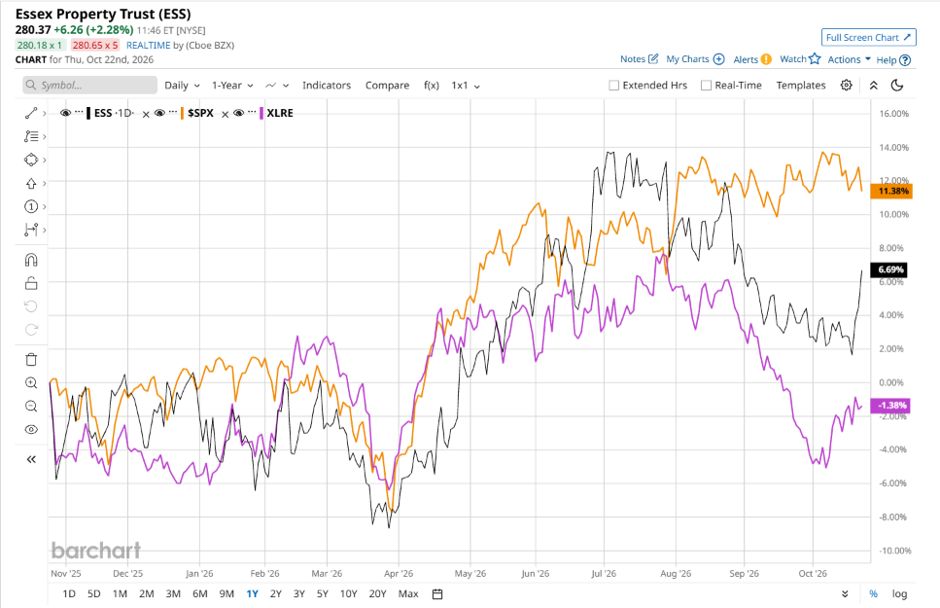
ESS stock has underperformed the S&P 500 Index’s ($SPX) 15.2% gains over the past 52 weeks, with shares up 5.9% during this period. However, it outperformed the State Street Real Estate Select Sector SPDR ETF’s (XLRE) marginal losses over the same time frame.
 www.barchart.com
ESS has lagged behind the broader equity market primarily due to elevated interest rates that weighed on REIT valuations, alongside pockets of earnings volatility driven by softer new lease spreads. While the company operates primarily in West Coast tech-heavy residential markets, broad macroeconomic cooling, tech sector layoffs, and elevated supply in select sub-markets tempered rent growth. Additionally, sticky operating expenses, specifically rising property taxes, utility costs, and insurance expenses, compressed profit margins, leading to a cautious investor sentiment despite solid overall occupancy and improving underlying West Coast rental demand.
On Jul. 29, ESS reported its Q2 results, and its shares fell over 5% in the following trading session. Its FFO of $4.08 per share surpassed Wall Street expectations of $4.03 per share. The company’s revenue was $489 million, topping Wall Street forecasts of $487.3 million. ESS expects full-year FFO in the range of $16.03 to $16.25 per share.
Analysts’ consensus opinion on ESS stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 26 analysts covering the stock, seven advise a “Strong Buy” rating, two suggest a “Moderate Buy,” 15 give a “Hold,” and two recommend a “Strong Sell.” ESS’ average analyst price target is $295.63, indicating a potential upside of 6% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Ahead of Infosys Earnings, Here's What Barchart Data Says Comes Next for INFY Stock This Company Helps Others Raise Revenue and Profits. It’s Taking a Dose of Its Own Medicine. How to Play SLNH Stock as Soluna Scores a Major Data Center Win Ahead of Western Digital Earnings, Here's What Barchart Data Says Comes Next for WDC Stock