

Fidelity National Information Services, Inc. (FIS) is a global financial technology company headquartered in Jacksonville, Florida, that provides software and technology solutions to banks, financial institutions, businesses, and capital markets firms. Valued at a market cap of $19.4 billion, its offerings include core banking systems, digital banking platforms, payment processing, lending, risk management, treasury management, and investment operations software.
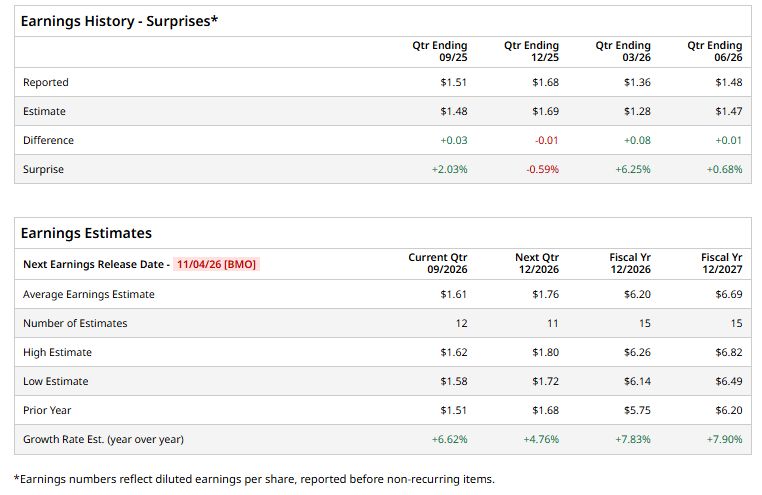
FIS is expected to release its Q3 2026 earnings before the market opens on Wednesday, Nov. 4. Ahead of the event, analysts expect the company’s EPS to be $1.61 on a diluted basis, up 6.6% from $1.51 in the year-ago quarter. The company has met or exceeded Wall Street’s EPS estimates in three of its last four quarters, while missing on one occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts project the company’s EPS to be $6.20, up 7.8% from $5.75 in fiscal 2025. Moreover, its EPS is expected to rise by roughly 7.9% year over year to $6.69 in fiscal 2027.
 www.barchart.com
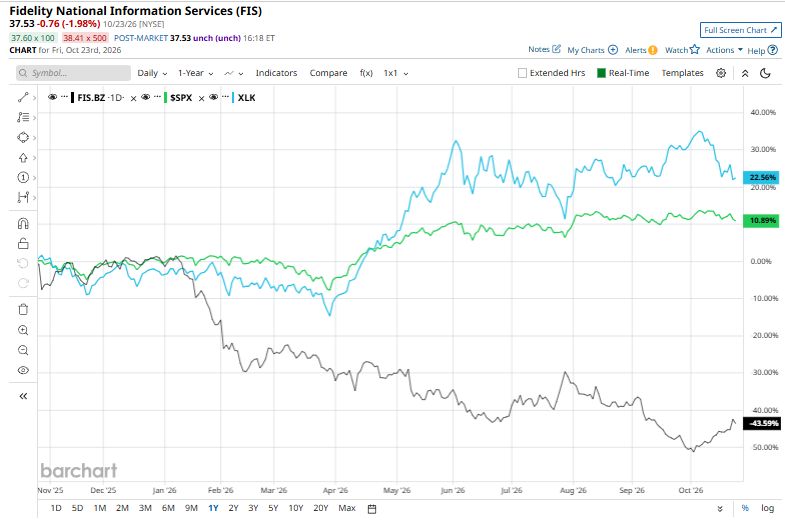
FIS stock has declined 44.4% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 13.1% rise and the State Street Technology Select Sector SPDR ETF’s (XLK) 26.8% rise during the same time frame.
 www.barchart.com
Fidelity National Information Services has lagged the broader market over the past year amid investor concerns about its growth trajectory, competitive pressures in financial technology, and the pace of its business transformation. The company has been working to streamline operations and improve profitability, but questions about revenue growth and execution have weighed on investor sentiment.
Analysts are moderately bullish about FIS, with the stock having a “Moderate Buy” rating overall. Among the 31 analysts covering the stock, 11 are recommending a “Strong Buy,” three suggest a “Moderate Buy,” 16 suggest a “Hold,” and one suggests a “Strong Sell.” FIS’ average analyst price target is $46.19, indicating an upside of 23.1% from the current price levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
A $1.3 Billion Reason to Buy Amkor Stock Marvell’s Road to $90B: The 3 Moves Behind the Boldest Target in AI Chips Dear SoFi Stock Fans, Mark Your Calendar for October 27 Piper Sandler Says Financing Concerns for CoreWeave Are Overblown. Not Everyone Is Convinced.