

Verisk Analytics, Inc. (VRSK) is a data analytics and technology company headquartered in Jersey City, New Jersey, that primarily serves the global insurance industry. Valued at a market cap of $25.5 billion, the company offers underwriting solutions, including forms, rules, and loss-cost services, such as policy language, prospective loss costs, policy writing, and other services.
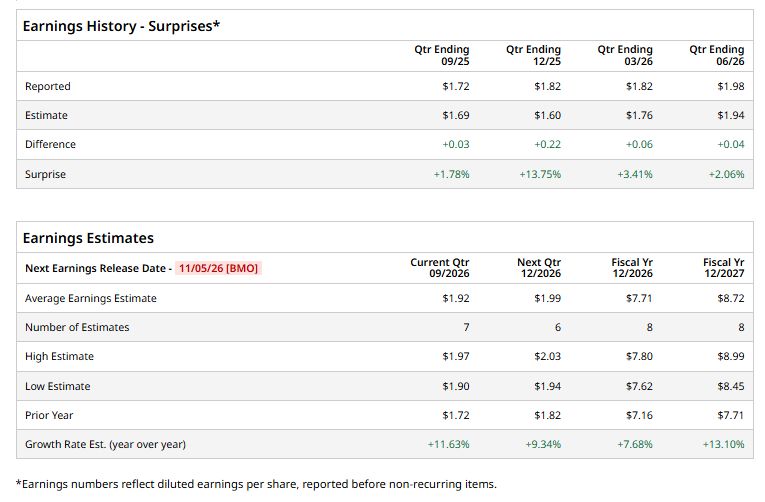
VRSK is expected to release its Q3 2026 earnings on Thursday, Nov. 5, before the market opens. Ahead of the event, analysts expect the company’s EPS to be $1.92 on a diluted basis, up 11.6% from $1.72 in the year-ago quarter. The company has exceeded Wall Street’s EPS estimates in all of its last four quarters.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts project the company’s EPS to be $7.71, up 7.7% from $7.16 in fiscal 2025. Moreover, its EPS is expected to rise by roughly 13.1% year over year to $8.72 in fiscal 2027.
 www.barchart.com
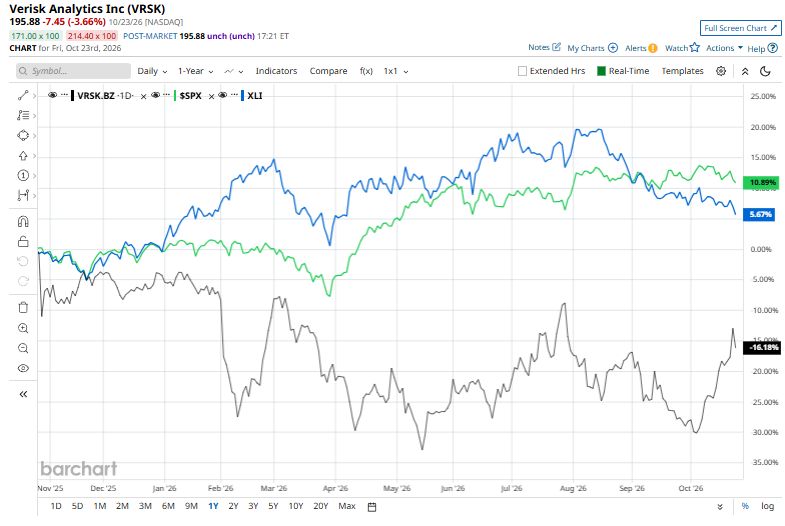
Verisk’s shares have declined 16.6% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 13.1% rise and the State Street Industrials Select Sector SPDR ETF’s (XLI) 6.4% return during the same time frame.
 www.barchart.com
Verisk Analytics has trailed the broader market over the past year amid concerns about its modest revenue growth and slowing earnings momentum. The company’s revenue grew at an annual rate of just 1.7% over the past five years, falling short of business services industry benchmarks, while its EPS increased by only 8% annually over the past two years, lagging behind peers and raising questions about its ability to accelerate growth.
Analysts are moderately bullish on VRSK, with a “Moderate Buy” rating overall. Among the 20 analysts covering the stock, ten are recommending a “Strong Buy,” one recommends a “Moderate Buy,” and nine suggest a “Hold.” VRSK’s average analyst price target is $227.89, indicating an upside of 16.3% from the current price levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
A $1.3 Billion Reason to Buy Amkor Stock Marvell’s Road to $90B: The 3 Moves Behind the Boldest Target in AI Chips Dear SoFi Stock Fans, Mark Your Calendar for October 27 Piper Sandler Says Financing Concerns for CoreWeave Are Overblown. Not Everyone Is Convinced.