

Insulet Corporation (PODD), headquartered in Acton, Massachusetts, operates as an innovative medical device company. Valued at $10.4 billion by market cap, the company develops, manufactures, and sells insulin delivery systems for people with insulin-dependent diabetes. The insulin infusion systems maker is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Wednesday, Nov. 4.
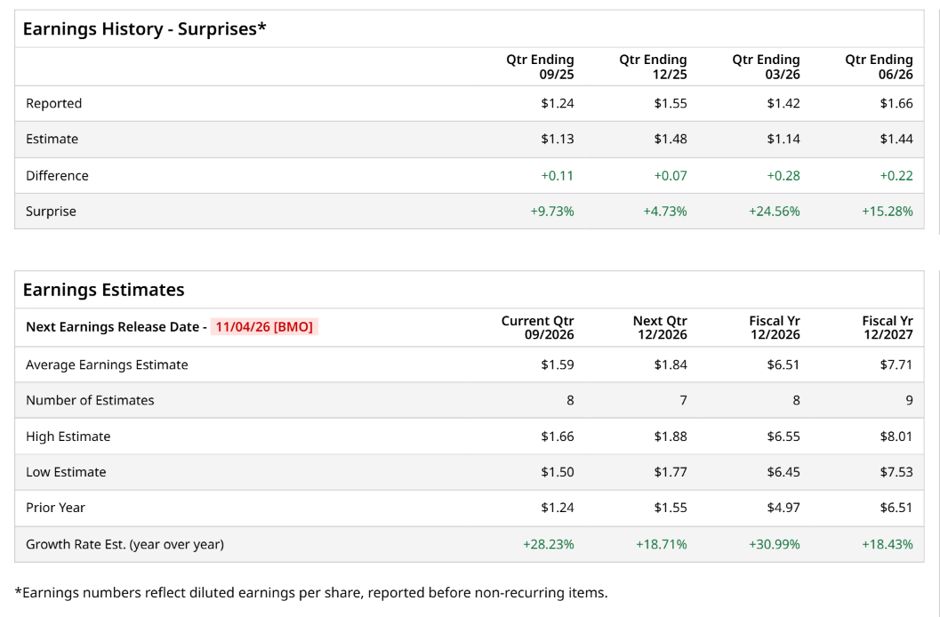
Ahead of the event, analysts expect Insulet to report a profit of $1.59 per share on a diluted basis, up 28.2% from $1.24 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Insulet to report EPS of $6.51, up 31% from $4.97 in fiscal 2025. Its EPS is expected to rise 18.4% year over year to $7.71 in fiscal 2027.
 www.barchart.com
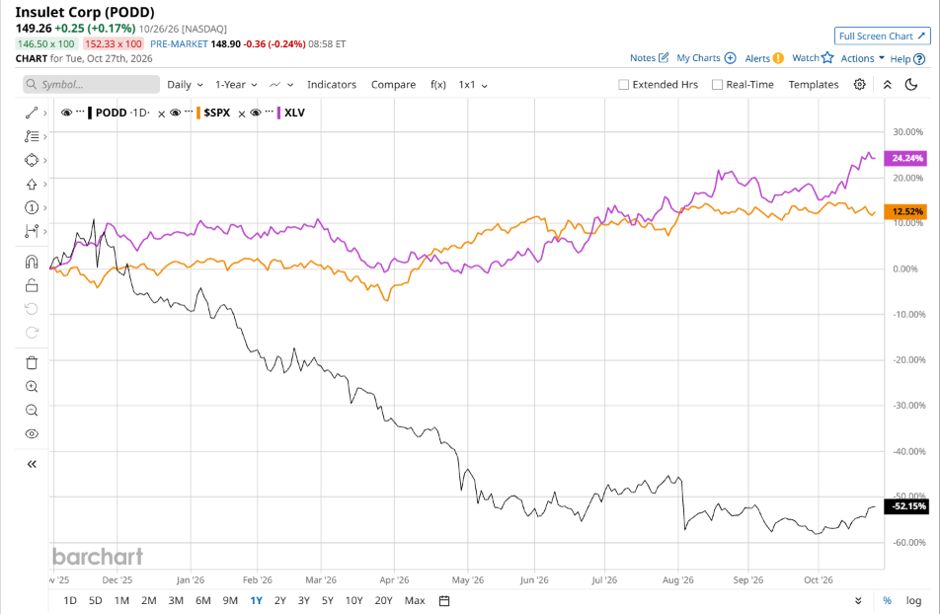
PODD stock has considerably underperformed the S&P 500 Index’s ($SPX) 13% gains over the past 52 weeks, with shares down 54.3% during this period. Similarly, it notably underperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 22.8% returns over the same time frame.
 www.barchart.com
PODD underperformed as market sentiment was weighed down by commercial friction in its Type 2 diabetes segment, key adoption concerns, and intensifying competition. While top-line growth remained solid via its Omnipod 5 system, investors reacted sharply to lower-than-expected retention rates among new Type 2 users during their first 90 days of therapy, forcing a reevaluation of patient onboarding and commercial support models. Compounding these retention hiccups, broader macro anxiety over GLP-1 adoption dampening long-term insulin demand and aggressive pressure from rival automated insulin delivery providers dampened investor enthusiasm, offsetting management's progress in expanding U.S. insurance coverage and stabilizing pricing.
On Aug. 5, PODD shares nosedived over 20% after reporting its Q2 results. Its adjusted EPS of $1.66 beat Wall Street expectations of $1.44. The company’s revenue was $801.7 million, topping Wall Street forecasts of $786.8 million.
Analysts’ consensus opinion on PODD stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 27 analysts covering the stock, 13 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” and 12 give a “Hold.” PODD’s average analyst price target is $166.08, indicating a potential upside of 11.3% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Let’s Be Like the Amish and Let’s Only Use Al for Certain Things’ — Bill Gates Says He’ll Leave It to the Younger Generation to Figure Out in the Next 20 Years Dear eBay Stock Fans, Mark Your Calendars for October 28 Snowflake’s P/E Is 62% Below Its Average. Smart Money Is Lending It Billions At 0% Interest. How to Manage Your Portfolio in a Volatile Market, Protect Your Nest Egg, and Profit from the Turmoil