

With a market cap of $97 billion, Duke Energy Corporation (DUK) is one of the largest energy holding companies in the United States, providing electricity and natural gas to millions of customers across the Southeast and Midwest. The company operates through its Electric Utilities and Infrastructure and Gas Utilities and Infrastructure segments, along with a growing Commercial Renewables portfolio.
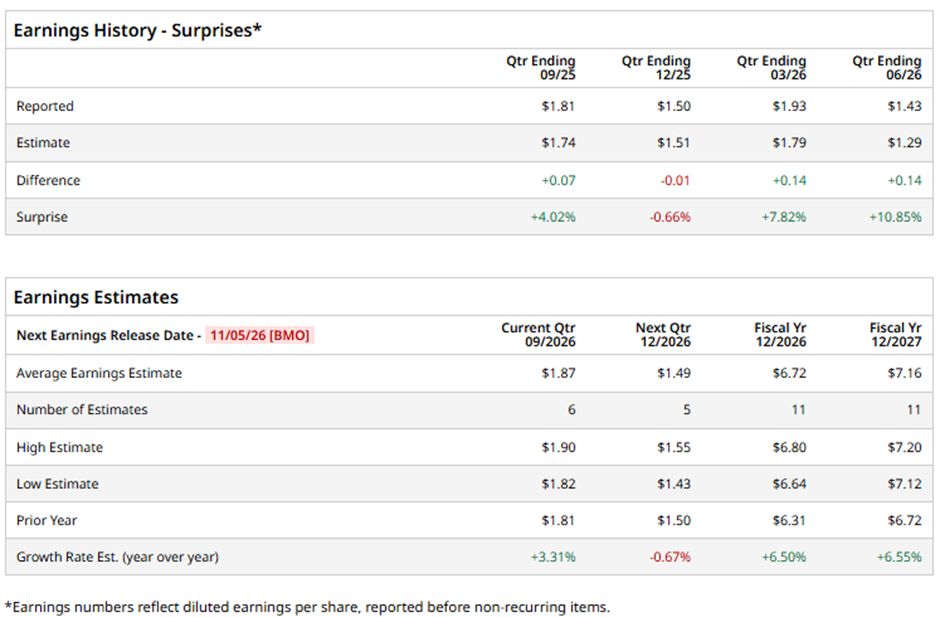
Based in Charlotte, North Carolina, the company is slated to announce its fiscal Q3 2026 results before the market opens on Thursday, Nov. 5. Ahead of this event, analysts expect Duke Energy to report an adjusted EPS of $1.87 per share, a rise of 3.3% from $1.81 in the year‑ago quarter. It has exceeded Wall Street's earnings expectations in three of the past four quarters while missing on another occasion.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts predict the electric utility to post adjusted EPS of $6.72, up 6.5% from $6.31 in fiscal 2025. Moreover, adjusted EPS is expected to grow 6.6% year-over-year to $7.16 in fiscal 2027.
 www.barchart.com
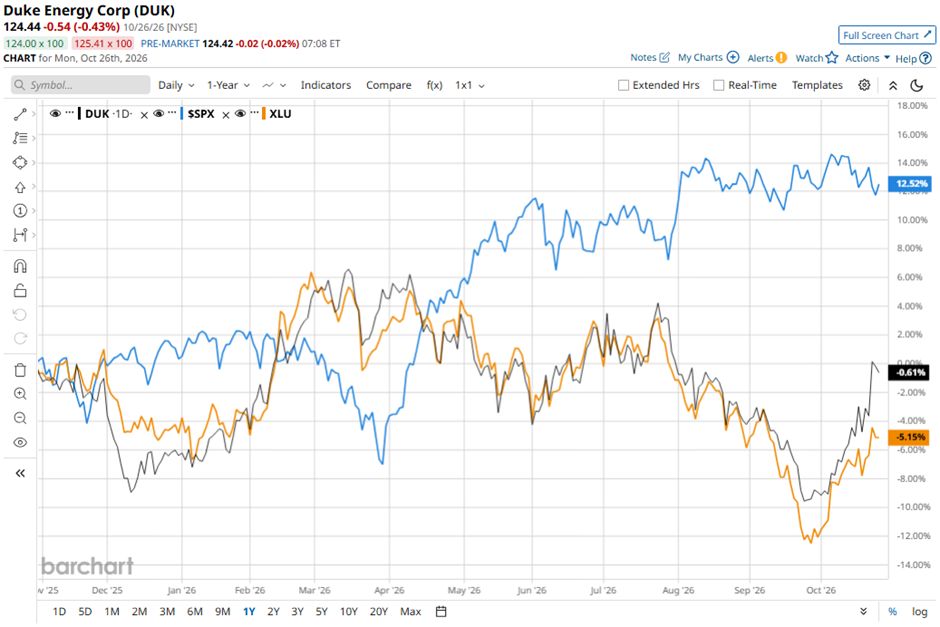
Shares of Duke Energy have fallen 2.3% over the past 52 weeks, lagging behind the broader S&P 500 Index's ($SPX) 13% return. However, the stock has shown a less pronounced decline than the State Street Utilities Select Sector SPDR ETF's (XLU) 6.9% decrease over the same period.
 www.barchart.com
Duke Energy reported Q2 2026 results on Aug. 4, with better-than-expected adjusted EPS of $1.43, as higher electricity demand and recovering returns on infrastructure investments offset rising costs. Its electric utilities segment’s quarterly profit increased to $1.27 billion and signed data-center electricity service agreements reached 7.8 GW, supporting expectations for continued power-demand growth.
The company also reaffirmed its 2026 adjusted EPS guidance of $6.44 - $6.80 and secured six additional gas turbines, bringing its total to 26, although interest expense rose 6.6% to $957 million and further generation and transmission needs could add $5 billion - $10 billion to its five-year capital plan.
Analysts' consensus view on DUK stock remains cautiously optimistic, with a "Moderate Buy" rating overall. Out of 24 analysts covering the stock, 11 recommend a "Strong Buy," one "Moderate Buy," and 12 "Holds." The average analyst price target of $131.67, indicating a potential upside of 5.8% from the current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Let’s Be Like the Amish and Let’s Only Use Al for Certain Things’ — Bill Gates Says He’ll Leave It to the Younger Generation to Figure Out in the Next 20 Years Dear eBay Stock Fans, Mark Your Calendars for October 28 Snowflake’s P/E Is 62% Below Its Average. Smart Money Is Lending It Billions At 0% Interest. How to Manage Your Portfolio in a Volatile Market, Protect Your Nest Egg, and Profit from the Turmoil