

TransDigm Group Incorporated (TDG) is a leading global aerospace company that designs, produces, and supplies highly engineered components for nearly every commercial and military aircraft in service today. Its extensive portfolio spans aircraft engine and ignition systems, mechanical and electrical controls, pumps and valves, batteries, cockpit displays, communication systems, safety restraints, and specialized cabin interiors.
The company also provides advanced testing equipment and services, along with cargo handling systems and other mission-critical aerospace solutions, making it an integral supplier to the global aviation and defense industries. With a market capitalization of approximately $62.47 billion, TransDigm is gearing up to report its fiscal 2026 fourth-quarter results soon, with Wall Street anticipating another solid earnings performance.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
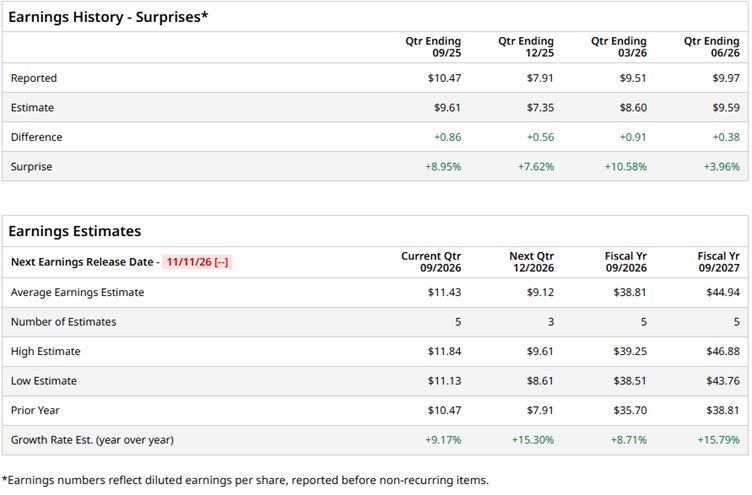
Analysts expect quarterly earnings to climb 9.2% year over year to $11.43 per share. TransDigm also boasts an impressive earnings track record, having surpassed Wall Street’s EPS estimates in each of the past four quarters. Looking ahead, analysts project earnings per share to rise 8.7% year over year to $38.81 in fiscal 2026, followed by a further 15.8% jump to $44.94 in fiscal 2027.
 www.barchart.com
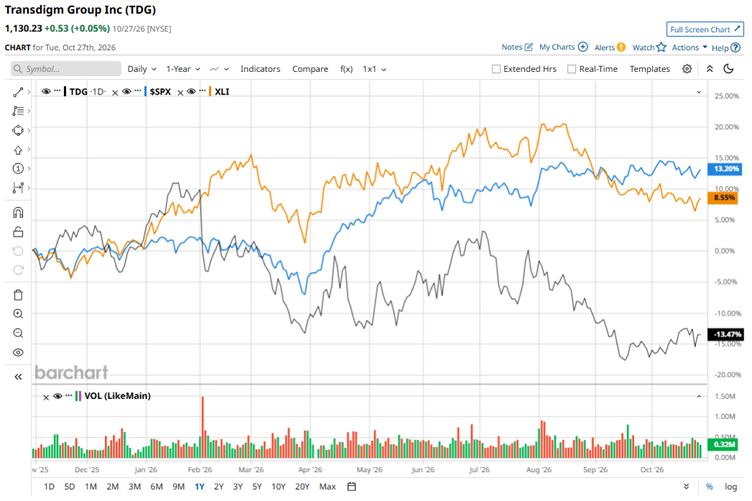
TransDigm Group has struggled to keep pace with the broader market, with its shares falling 16.6% over the past year. In contrast, the S&P 500 Index ($SPX) has advanced 12.3%, while the State Street Industrial Select Sector SPDR ETF (XLI) has gained 7.8% over the same period, highlighting TDG’s recent underperformance against both the broader market and its industrial peers.
 www.barchart.com
TransDigm Group’s stock has faced pressure over the past year, weighed down by concerns over its substantial debt load, rich valuation, and expectations surrounding acquisitions and margins. However, the company’s fiscal Q3 results, reported in early August, offered a strong counterpoint, with robust double-digit growth in both revenue and adjusted earnings.
Net sales surged 23% year over year to $2.74 billion, comfortably topping Wall Street’s $2.67 billion estimate, while its EBITDA As Defined margin remained impressive at 52.8%. Adjusted EPS climbed 13% from the prior year, also surpassing consensus expectations. Strong demand across commercial original equipment manufacturing (OEM) and aftermarket channels, coupled with continued resilience in defense, powered the solid performance.
As TransDigm Group approaches its fourth-quarter earnings release, Wall Street sees room for further upside, maintaining a consensus “Moderate Buy” rating on the stock. Among the 21 analysts covering TDG, 10 recommend a “Strong Buy,” while the remaining 11 assign a “Hold” rating. With an average price target of $1,406.22, analysts are signaling potential upside of approximately 24.4% from current levels.
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dan Ives Sees an Imminent SpaceX-Tesla Merger. The Biggest Win Would be in AI Data Centers. Dell Max Pain Points to a Price of $480 by November 20th Nasdaq Futures Climb as SK Hynix Adds Fuel to Chip Rally; Fed Decision and Big Tech Earnings in Focus This Defense Stock Just Raised Its Dividend by More Than 2%