

CVS Health Corporation (CVS), headquartered in Woonsocket, Rhode Island, provides health solutions including health care and retail pharmacy services. With a market cap of $115.5 billion, the company offers prescription medications, beauty, personal care, cosmetics, and health care products, as well as pharmacy benefit management (PBM), disease management, and administrative services.
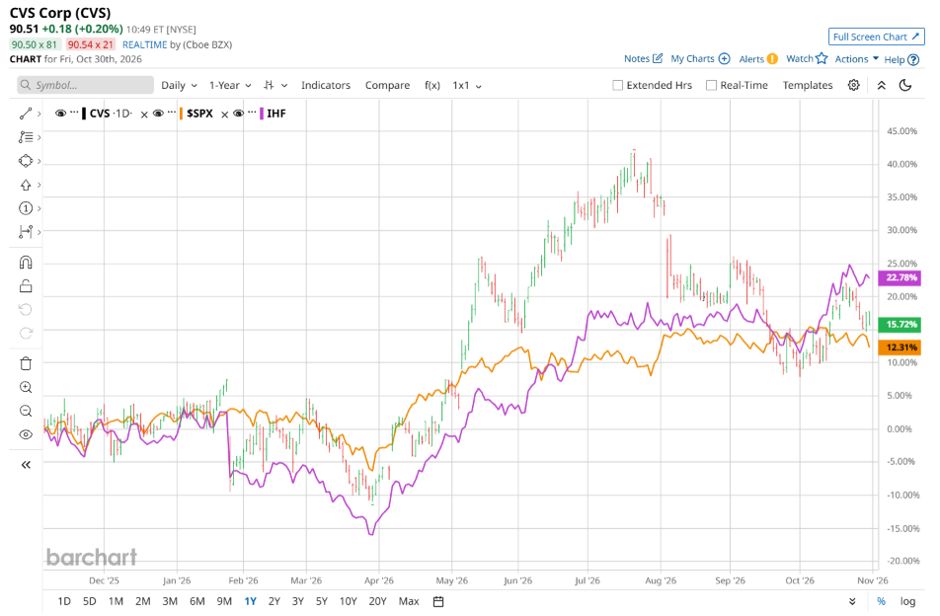
Shares of this pharmacy giant have outperformed the broader market over the past year. CVS has gained 18.3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12%. In 2026, CVS stock is up 14.3%, surpassing the SPX’s 11.4% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Narrowing the focus, CVS’ underperformance is apparent compared to the iShares U.S. Healthcare Providers ETF (IHF). The exchange-traded fund has gained about 23.7% over the past year. Moreover, the ETF’s 25.5% gains on a YTD basis outshine the stock’s returns over the same time frame.
 www.barchart.com
CVS’ mixed performance reflects a balancing act between near-term headwinds and operational catalysts. On the one hand, investor sentiment has been pressured by weaker client retention, regulatory headwinds facing its Caremark pharmacy benefit manager (PBM), and broader macroeconomic uncertainties. On the other hand, the company has found strength through improving operating performance at Aetna, which is driven by lower medical costs and a favorable drug mix, alongside consecutive earnings beats, a raised 2026 earnings outlook, and the nationwide rollout of its 2026–27 flu vaccines and expanded clinical services to capture seasonal demand.
For the current fiscal year, ending in December, analysts expect CVS’ EPS to grow 18.8% to $8.02 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
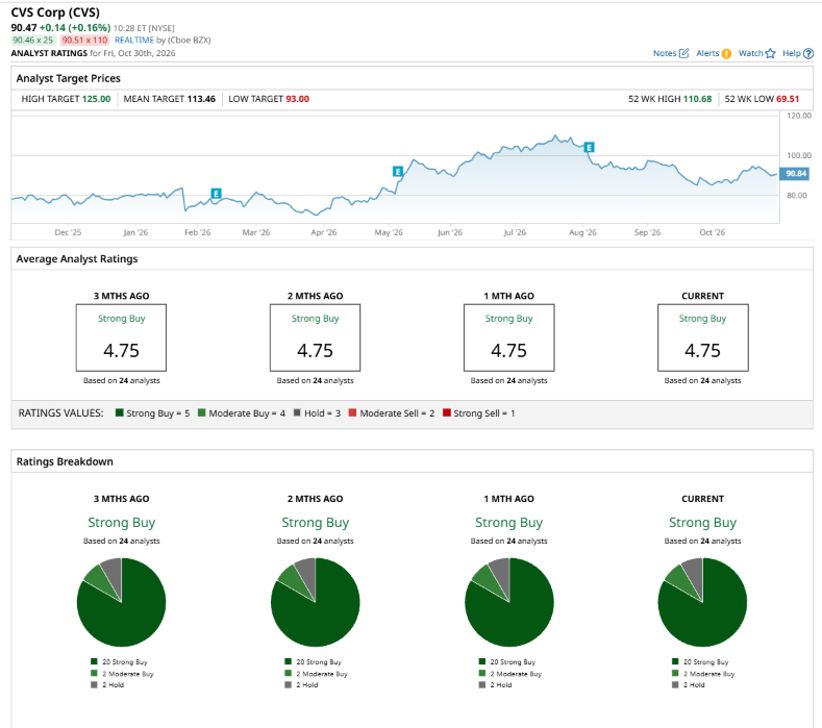
Among the 24 analysts covering CVS stock, the consensus is a “Strong Buy.” That’s based on 20 “Strong Buy” ratings, two “Moderate Buys,” and two “Holds.”
 www.barchart.com
The configuration has been consistent over the past three months.
On Oct. 13, Bank of America Corporation (BAC) analyst Allen Lutz maintained a “Buy” rating on CVS and set a price target of $110, implying a potential upside of 21.6% from current levels.
The mean price target of $113.46 represents a 25.4% premium to CVS’ current price levels. The Street-high price target of $125 suggests a notable upside potential of 38.2%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Ahead of Palantir Earnings, Here's What Barchart Data Says Comes Next for PLTR Stock SpaceX's IPO Offers a Warning for Anthropic Investors. Here's My Best Advice. Investors Beware — This ‘Faker’s Dozen’ of Instagram-Famous ETFs is Just Going for Likes and Followers Why Constellation Energy Is Becoming a Bigger Part of the AI Trade