

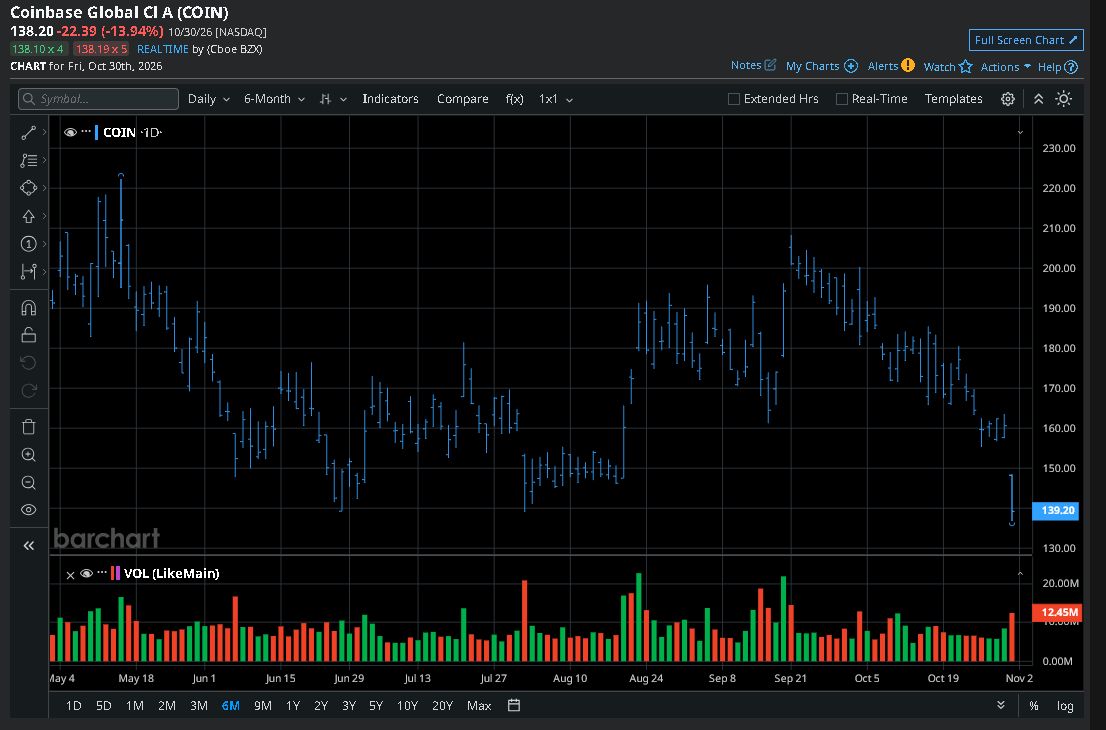
Coinbase (COIN) shares closed down 10.6% on Friday as the company’s Q3 earnings made several Wall Street analysts reduce their price targets for 2027.
Adding to pressure is weakness in Bitcoin (BTCUSD) which slipped to about $77,000 following reports of a $6.3 billion hack – the largest in crypto history – at peer Binance.
Join 200K+ Subscribers: Find out why the midday Barchart Brief newsletter is a must-read for thousands daily.
Following the post-earnings decline, Coinbase stock is down over 35% versus the start of this year.
 www.barchart.com
What Made Analysts Trim Their Price Targets on COIN Stock?
While Coinbase’s revenue came in slightly shy of expectations at $1.21 billion, its Q3 earnings per share (EPS) of $2.51 landed miles ahead of the $0.08 consensus.
But the headline beat offered limited reassurance about the company’s near-term trajectory.
The bigger concern was what comes next. Barclays said the revenue run-rate entering its financial fourth quarter was weakening while projected costs exceeded expectations, prompting substantial reductions to COIN’s near-term adjusted EBITDA estimates.
For investors, that matters because softer activity can constrain trading fees while higher spending absorbs more income – leaving Coinbase needing stronger volumes or faster growth elsewhere to protect its profitability.
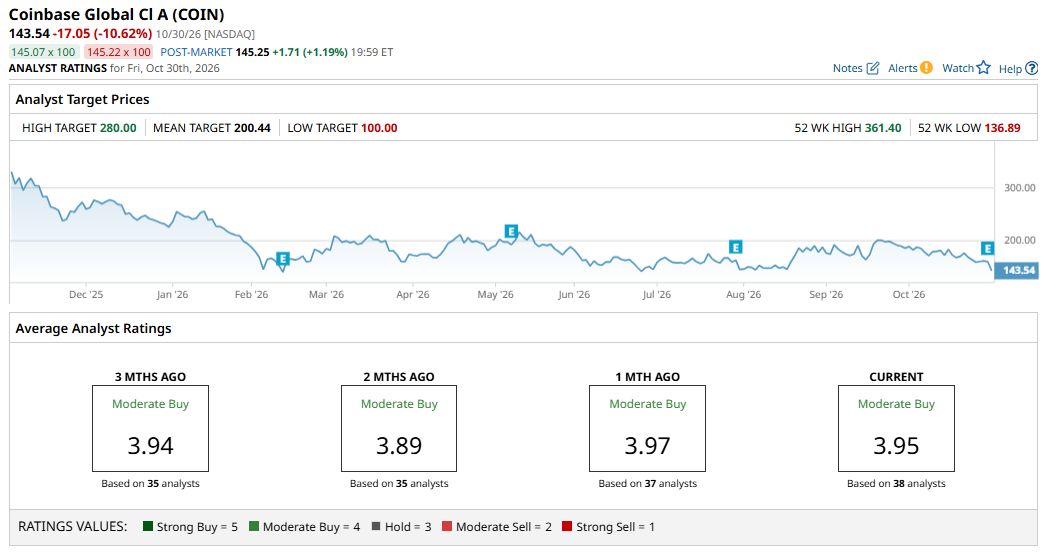
Barclays lowered its price target on COIN shares to $120, indicating potential downside of another 14% from here.
Are Coinbase Shares Worth Buying on the Post-Earnings Dip?
Other Wall Street firms that reduced their price targets on Coinbase shares on Friday include Needham, JPMorgan, and Rosenblatt Securities. Unlike Barclays, however, these three still rate the company at “Buy.”
The contrasting ratings suggest analysts haven’t necessarily abandoned the investment case.
In fact, Rosenblatt said new products like predictions markets cushioned spot-trading weakness – adding the Q3 print actually delivered evidence that the crypto giant’s “Everything Exchange” strategy is working.
That said, the distinction is between diversification and acceleration.
Prediction markets, derivatives, and USDC can broaden Coinbase’s revenue base, but investors still need evidence that these businesses can offset subdued trading demand while supporting earnings growth as expenses climb.
Coinbase Remains ‘Buy’-Rated Among Wall Street Firms
Investors should note, however, that Wall Street hasn’t thrown in the towel on COIN stock yet.
The consensus rating on Coinbase Global still sits at “Moderate Buy,” with the mean price target of about $200 indicating potential upside of a whopping 40% from here.
 www.barchart.com
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Wall Street Analysts Are Slashing Price Targets on Coinbase Stock. Here’s Why. Micron vs. SanDisk: China's DRAM Scare Hit Both Stocks, but 1 Is the Better Buy Option Volatility and Earnings Report For Nov 2-6 U.S. Stock Futures Climb as Oil Slumps; Midterm Elections and Jobs Data in Focus