

Alphabet (GOOG) is spending big on artificial intelligence (AI), and it’s likely to spend a lot more. In fact, the Google parent expects to spend between $195 billion and $205 billion on infrastructure and other capital projects in 2026. For 2027, the company also warned that spending will rise significantly.
Bank of America analysts believe that Alphabet's 2027 capital expenditures could surge to about $300 billion. While the firm recently kept a “Buy” rating on Alphabet stock with a $430 price target, analysts are concerned about whether Google’s AI and cloud business can pay the bills.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
That concern is easy to understand. Alphabet is putting billions of dollars into the computers, equipment, and data centers needed to run AI. But shareholders want to know when those investments will leave the company with more money.
 www.barchart.com
Alphabet Is Spending More Cash Than It Brings In
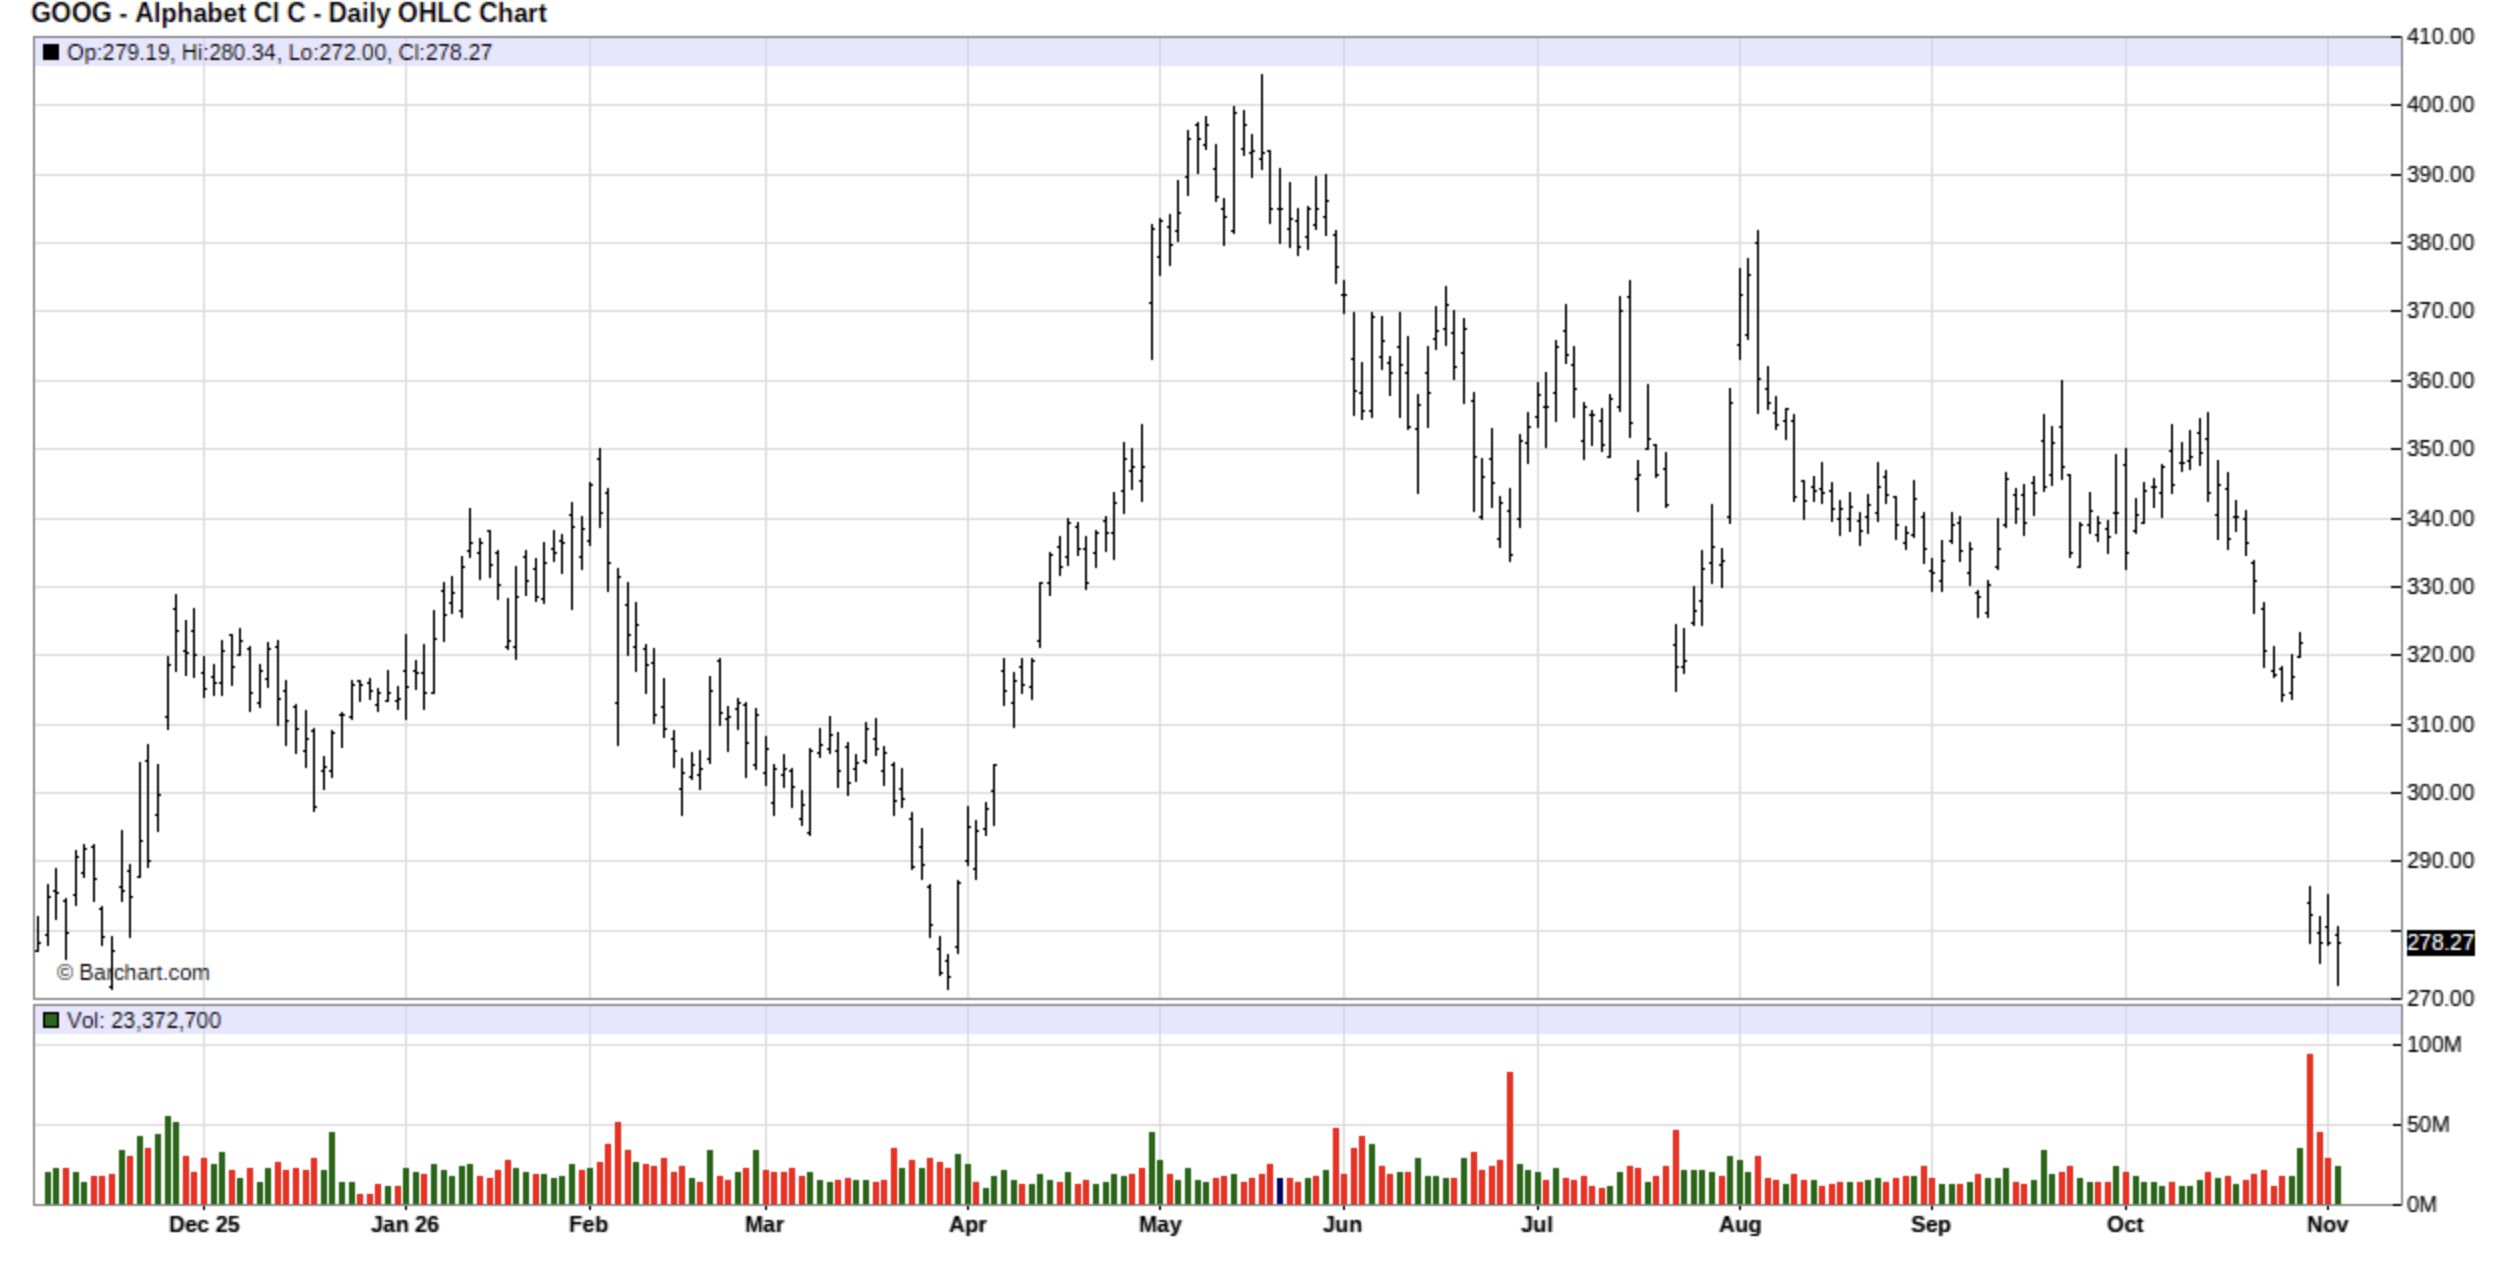
Here is the clearest example of why investors are concerned. Alphabet generated operating cash flow of $42.3 billion during the third quarter of fiscal 2026. But it spent $51.4 billion on capital projects. That left the company with free cash flow of about -$9.1 billion in Q3. With that being negative, it’s not so attractive to shareholders looking for dividends, buybacks, debt paybacks, or even future investments. Now that spending will increase, there’s far less attraction to the stock.
When investors buy shares of a company, they are paying for a piece of that company’s future earnings and cash. If Alphabet keeps spending more, there may be less cash left over in the near term. That can make investors less willing to pay a high price for GOOG stock. Plus, we have to remember that building a data center costs money way before it starts serving customers. Alphabet needs those customers to eventually bring in enough business to justify the investment.
There are also ongoing expenses. Servers need electricity. Buildings need maintenance. Equipment eventually needs replacing. In other words, today’s purchases can affect reported profits for years. That is why investors want more than promises about the future of AI. They want evidence that the extra spending will produce enough additional income — and right now, they can’t get that.
Google Search Is Going Through a Costly Change
How Google makes money from AI searches is another issue. Traditional Google searches often display ads with links. Those ads have helped build Alphabet’s business. But that’s now an issue with AI, which can help answer user questions directly through longer conversations. Unfortunately, according to Alphabet, AI Mode also earns the company less ad revenue from AI searches, although the firm is working to expand ads in AI programs.
Fortunately, Alphabet’s AI investments are helping one major business grow. Google Cloud revenue jumped 103% year-over-year (YOY) to $30.7 billion In Q3. The company said demand for its AI infrastructure and services helped drive that increase.
That gives investors a reason to remain interested. If businesses continue buying Google’s cloud and AI services, the new infrastructure could support years of growth. For GOOG stock shareholders, that is the key issue to watch. A bigger AI budget could be worthwhile if Alphabet produces stronger financial results. But if spending keeps climbing faster than the cash coming in, GOOG stock could struggle. Of course, we’ll learn more when the company releases Q4 numbers in the new year.
What Do Analysts Say About GOOG Stock?
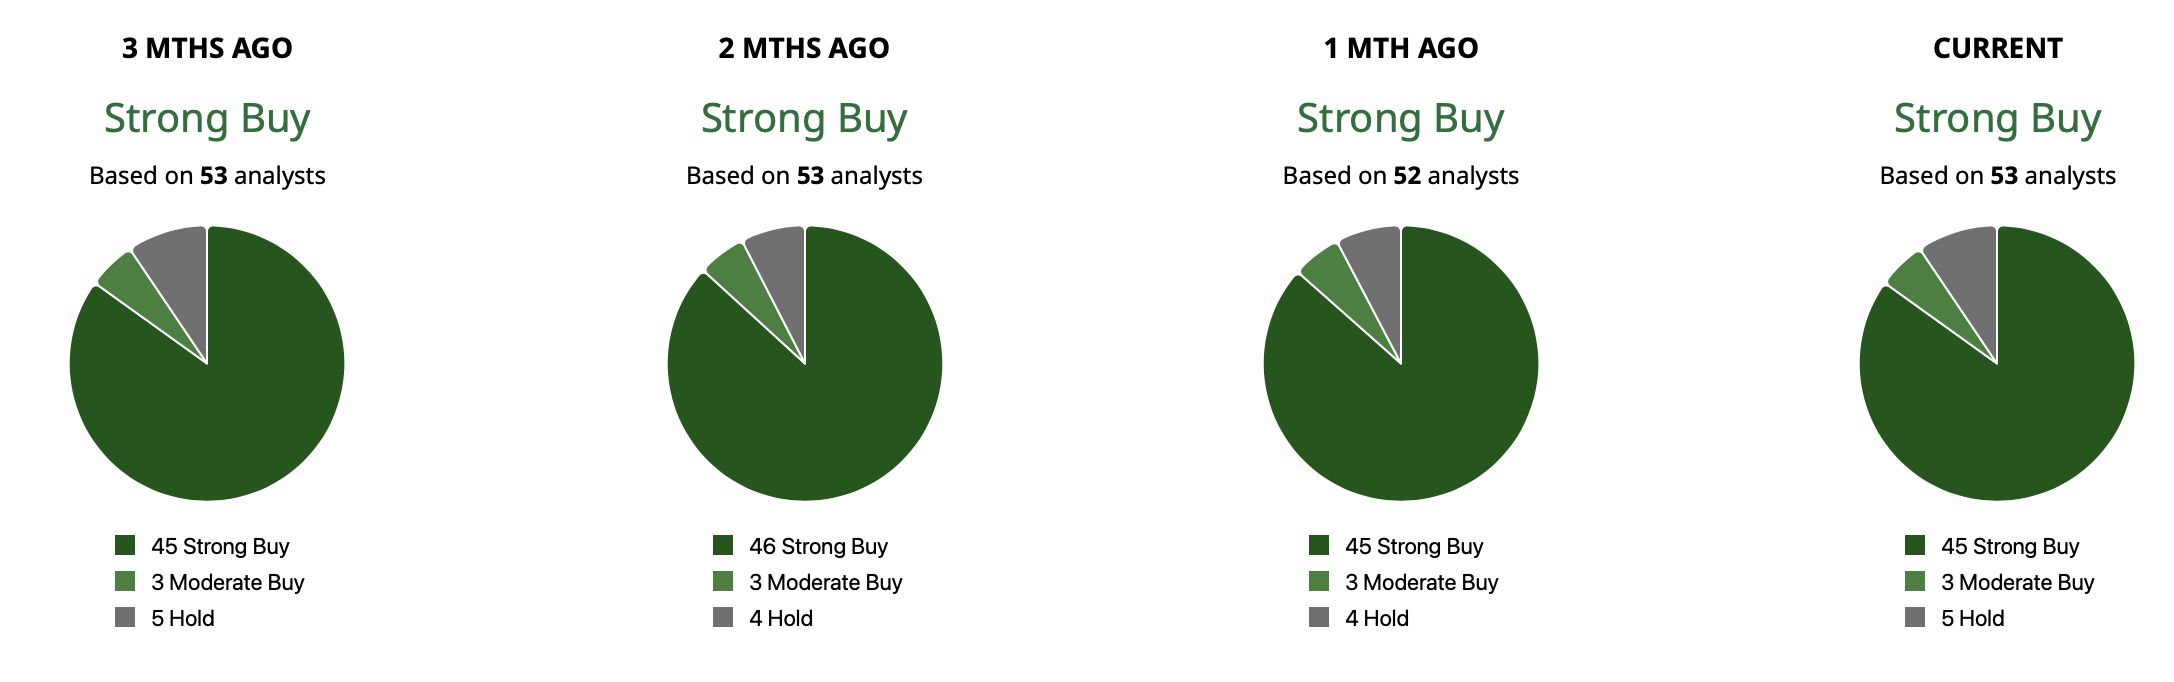
Overall, Alphabet stock has a consensus “Strong Buy” rating on Wall Street. Of the 53 analysts covering GOOG stock, 45 have a “Strong Buy” rating, three have a “Moderate Buy” rating, and five have a “Hold” rating. The mean target price of $404.21 implies potential upside of 43% from current levels. Meanwhile, the high price target of $515 implies potential upside of roughly 83% from here.
Alphabet’s AI spending could pay off over time. But it’s understandable that shareholders want more than another promise of future growth. They want to see that the money going out today will eventually leave the business and their investment in better shape. That makes the next few earnings reports especially important. Investors will be watching whether cloud growth and AI advertising bring in enough additional cash to ease the pressure from spending. Alphabet doesn’t have to prove that every dollar was well spent overnight. But it does need to give shareholders a clearer reason to be patient.
 www.barchart.com
On the date of publication, Ian Cooper did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
This Could be a Major Problem for Alphabet Investors Uber Technologies Delivers Strong FCF - What's the Best UBER Play? Apple Flagged Supply Constraints and Rising Memory Costs Ahead of Its December Quarter. Here’s What to Know. Dan Ives Remains Bullish on Palantir Despite Sector Weakness. What This Means for PLTR Stock.