

Saint Paul, Minnesota-based 3M Company (MMM) provides diversified technology services, conducting operations in electronics, telecommunications, industrial, consumer and office, health care, safety, and other markets. Valued at $97 billion by market cap, the company businesses share technologies, manufacturing operations, marketing channels, and other resources.
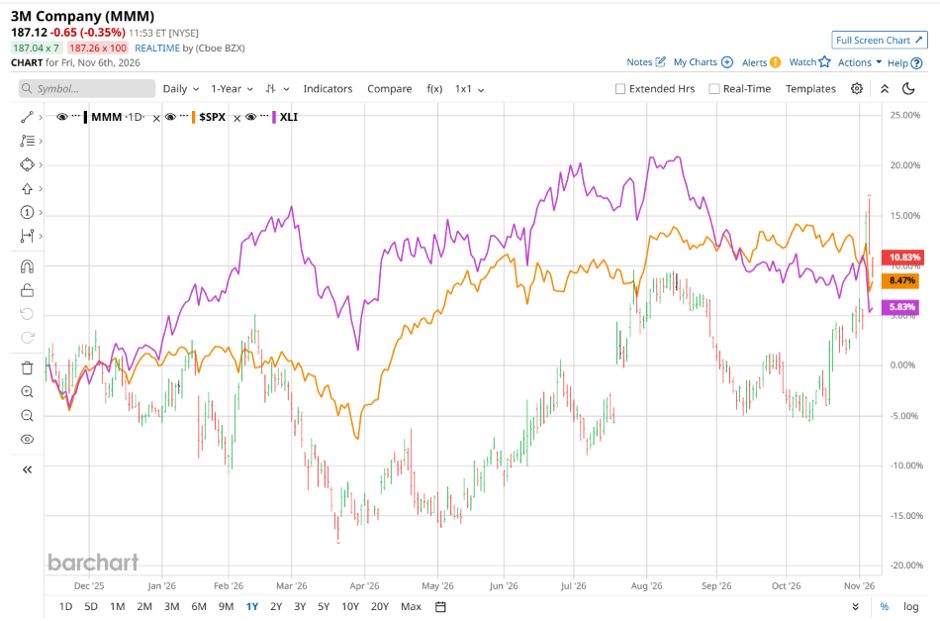
Shares of this conglomerate giant have outperformed the broader market over the past year. MMM has gained 13.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 8.2%. In 2026, MMM stock is up 16.1%, surpassing the SPX’s 7.4% gains on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Zooming in further, MMM’s outperformance is also apparent compared to the State Street Industrial Select Sector SPDR ETF (XLI). The exchange-traded fund has gained about 6.7% over the past year. Moreover, MMM’s double-digit returns on a YTD basis outshine the ETF’s 5% gains over the same time frame.
 www.barchart.com
3M’s outperformance highlighted by Q3 revenue coming in at $6.58 billion (close to analyst estimates of $6.60 billion) and an adjusted EPS of $2.46 (beating expectations of $2.39), was driven by disciplined pricing execution, robust productivity gains, and strong demand in industrial, semiconductor, and data center markets. Management successfully offset consumer electronics softness and input cost pressures by accelerating new product launches, expanding manufacturing capacity through strategic partnerships like AWS and GSEO, and streamlining operations by closing 16 facilities. Looking ahead, this strong momentum and a healthy backlog enabled the company to raise its full-year profit guidance.
For the current fiscal year, ending in December, analysts expect MMM’s EPS to grow 13.4% to $9.14 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
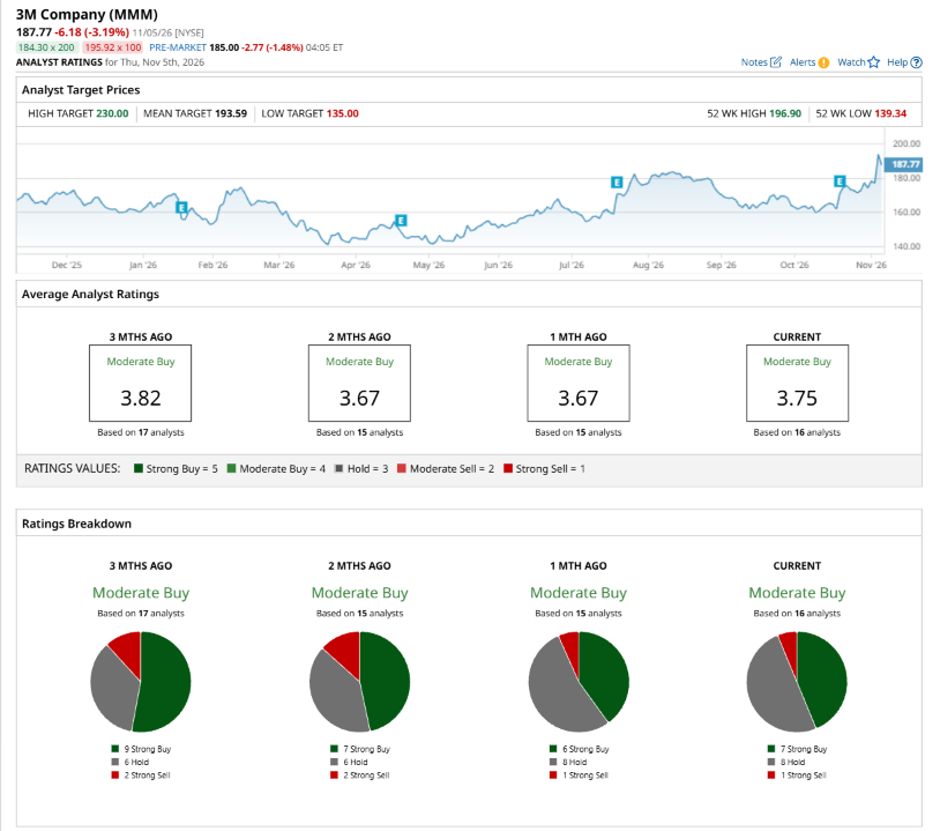
Among the 16 analysts covering MMM stock, the consensus is a “Moderate Buy.” That’s based on seven “Strong Buy” ratings, eight “Holds,” and one “Strong Sell.”
 www.barchart.com
This configuration is more bullish than a month ago, with six analysts suggesting a “Strong Buy.”
On Nov. 4, The Goldman Sachs Group, Inc. (GS) kept a “Buy” rating on MMM and raised the price target to $225, implying a potential upside of 19.8% from current levels.
The mean price target of $193.59 represents a 3.1% premium to MMM’s current price levels. The Street-high price target of $230 suggests a notable upside potential of 22.5%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why Wall Street Still Thinks Appian Stock Can Gain 50% from Here Why You Shouldn’t Buy the Dip in Tesla Stock Dear Cerebras Stock Fans, Mark Your Calendars for November 12 Dear Cerebras Stock Fans, Mark Your Calendars for November 9