

“There has never been a trillion-dollar revenue business, and we may have two of them in the next 5-10 years,” says Andy Jassy. On Amazon's (AMZN) last earnings call, he said that the two are AWS and its stores business. For scale, in the past 12 months, Amazon's entire business made $797 billion, well short of a trillion. Let's take a closer look at Amazon and that math.
About Amazon Stock
Amazon is best known for its online store, but it's also the world's biggest cloud company and runs ads, Prime Video, and Alexa. AWS and its online stores are the two businesses Andy Jassy thinks could each make a trillion dollars a year in the next 5-10 years. Founded in 1994 by Jeff Bezos, the company is headquartered in Seattle, Washington.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
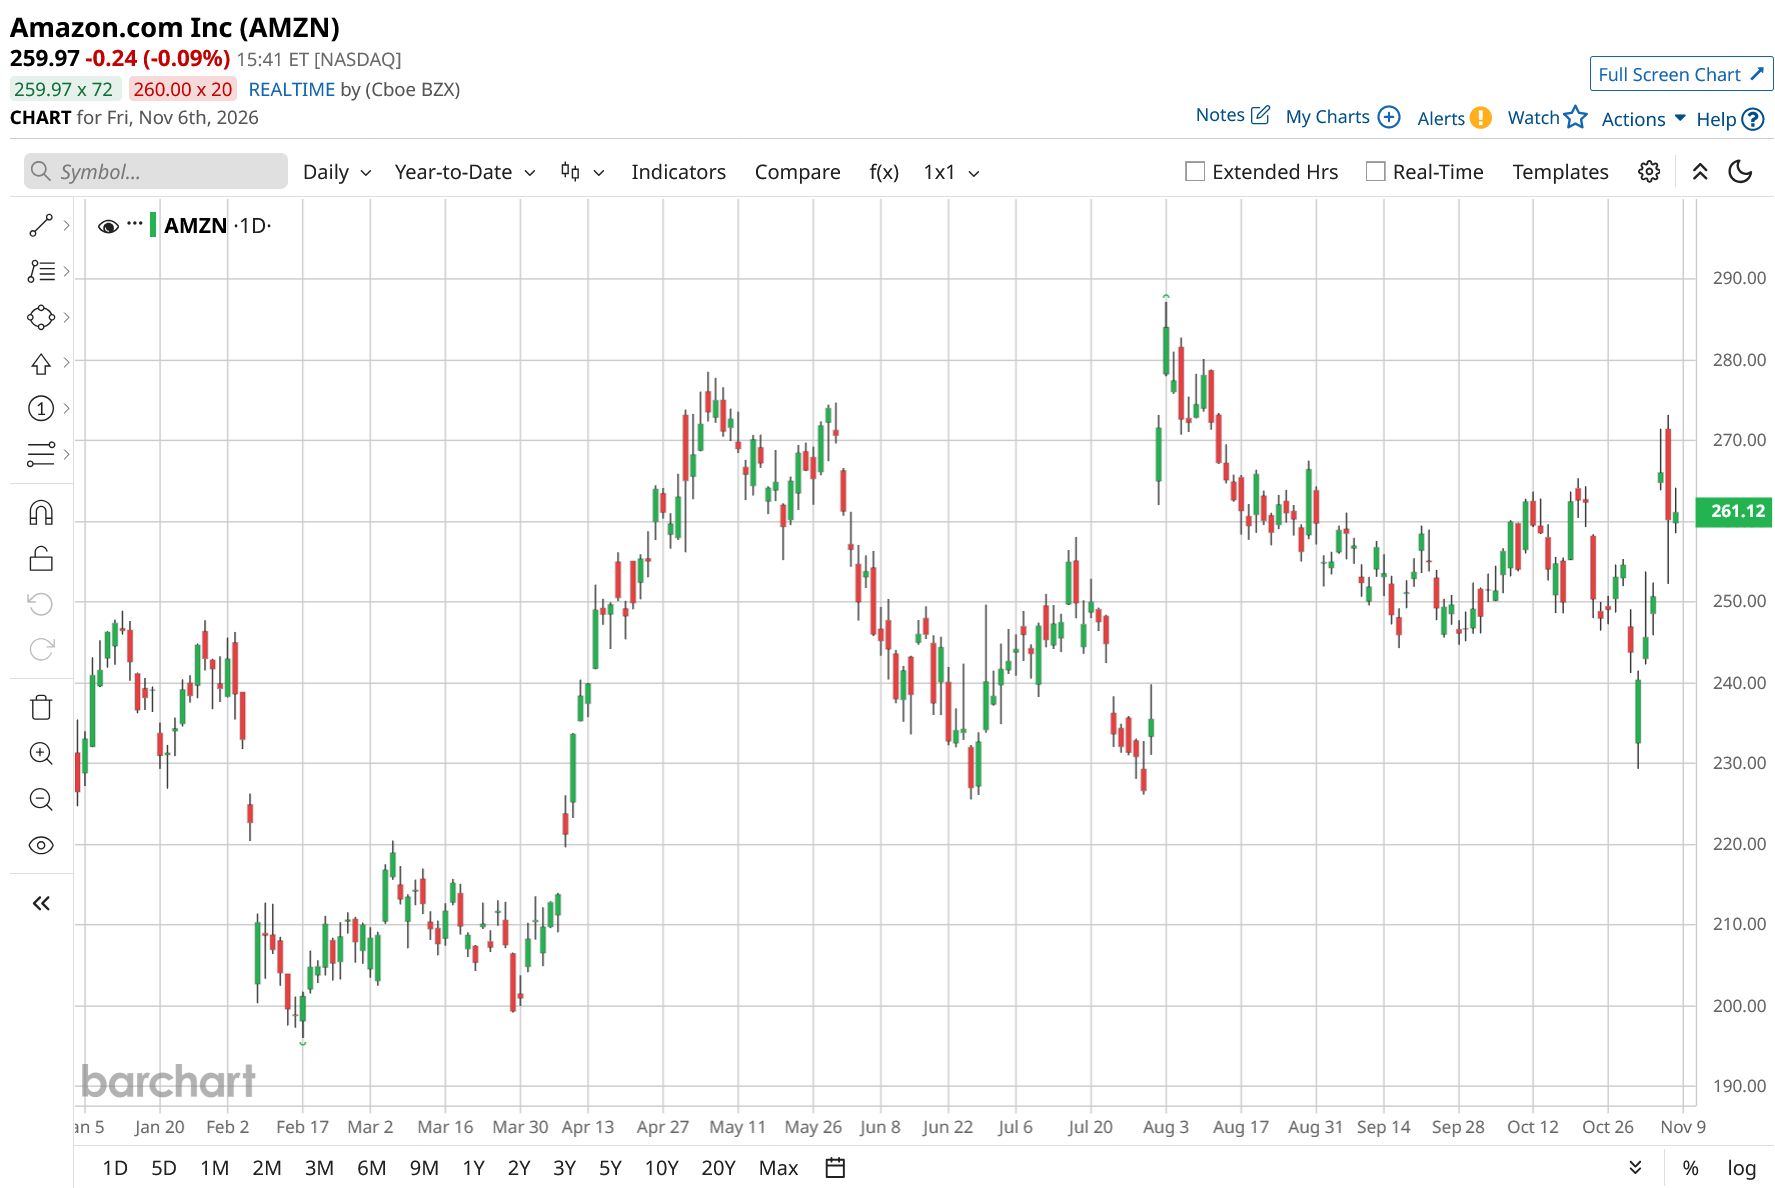
Amazon’s stock is up roughly 13% this year, outperforming the S&P 500’s ($SPX) 8% gain during the same period. In the last five days alone, it has surged 9%, more than erasing its post-earnings drop as analysts stepped in and investors refocused on AWS' 39% growth.
 www.barchart.com
A Closer Look at the Math
Here's the math behind AWS and stores getting to a trillion-dollar annual revenue and whether I believe it actually gets there.
AWS now earns $184 billion in annual run rate and grew 39.3% last quarter. Management said that enterprises are looking to run their core and AI workloads in AWS, and the company continues to add capacity every year. This is why it believes AWS can grow over 40% in each of 2027 and 2028. If it continues to grow at that rate, it gets to roughly $990 billion in about five years. Some people might question if maintaining a 40% growth rate for years is possible, and therefore decide that the goal isn't reachable. But I think the target seems realistic. Even if the growth slows to about 30%, the company still reaches the milestone within seven years, within Jassy's 10-year window.
AWS' numbers also keep getting stronger. Its backlog is now at $578 billion, more than double from a year earlier and up from $496 billion last quarter.
For the Stores business, reaching the goal looks a little harder, although still achievable. Amazon's Stores-only revenue in the past 12 months is about $497 billion. Over this period, its Stores revenue has grown at roughly a rate of 9-10%. Assuming a similar growth rate in the coming years, it reaches the $1 trillion mark in about eight years. Furthermore, Jassy seems to include advertising in Stores, since most of Amazon's ads run on its store pages. Adding ads and subscriptions together would bring the revenue to about $629 billion. The target in that case looks a lot easier to achieve, especially considering that ad revenue has been growing at 22-26% in most quarters recently.
If the Math Holds, Amazon's Valuation Is Modest
I think if Jassy's math plays out, Amazon's current valuation looks quite modest. The stock trades at about 24x forward earnings, far below its five-year average of 158x. The historical average is inflated by years when profits were too small, making the price-to-sales (P/S) ratio a better guide. At 3.39x, it sits 18% above its five-year average of 2.88x. The premium reflects how much more of its revenue now comes from AWS and ads, its higher-margin businesses. Analysts expect profits to dip about 17% in 2027, but that's mainly because this year's numbers included significant paper gains on Amazon's Anthropic stake. Subsequently, growth picks back up, and the price-to-earnings (P/E) is estimated to drop to 15x by 2029. Looking at the balance sheet, Amazon now holds net debt of $190 billion. This still seems pretty manageable for a company worth $2.8 trillion.
Overall, I believe the price looks fair, and even cheap, if AWS can get anywhere close to a trillion in annual revenue.
What Do Analysts Expect for AMZN Stock?
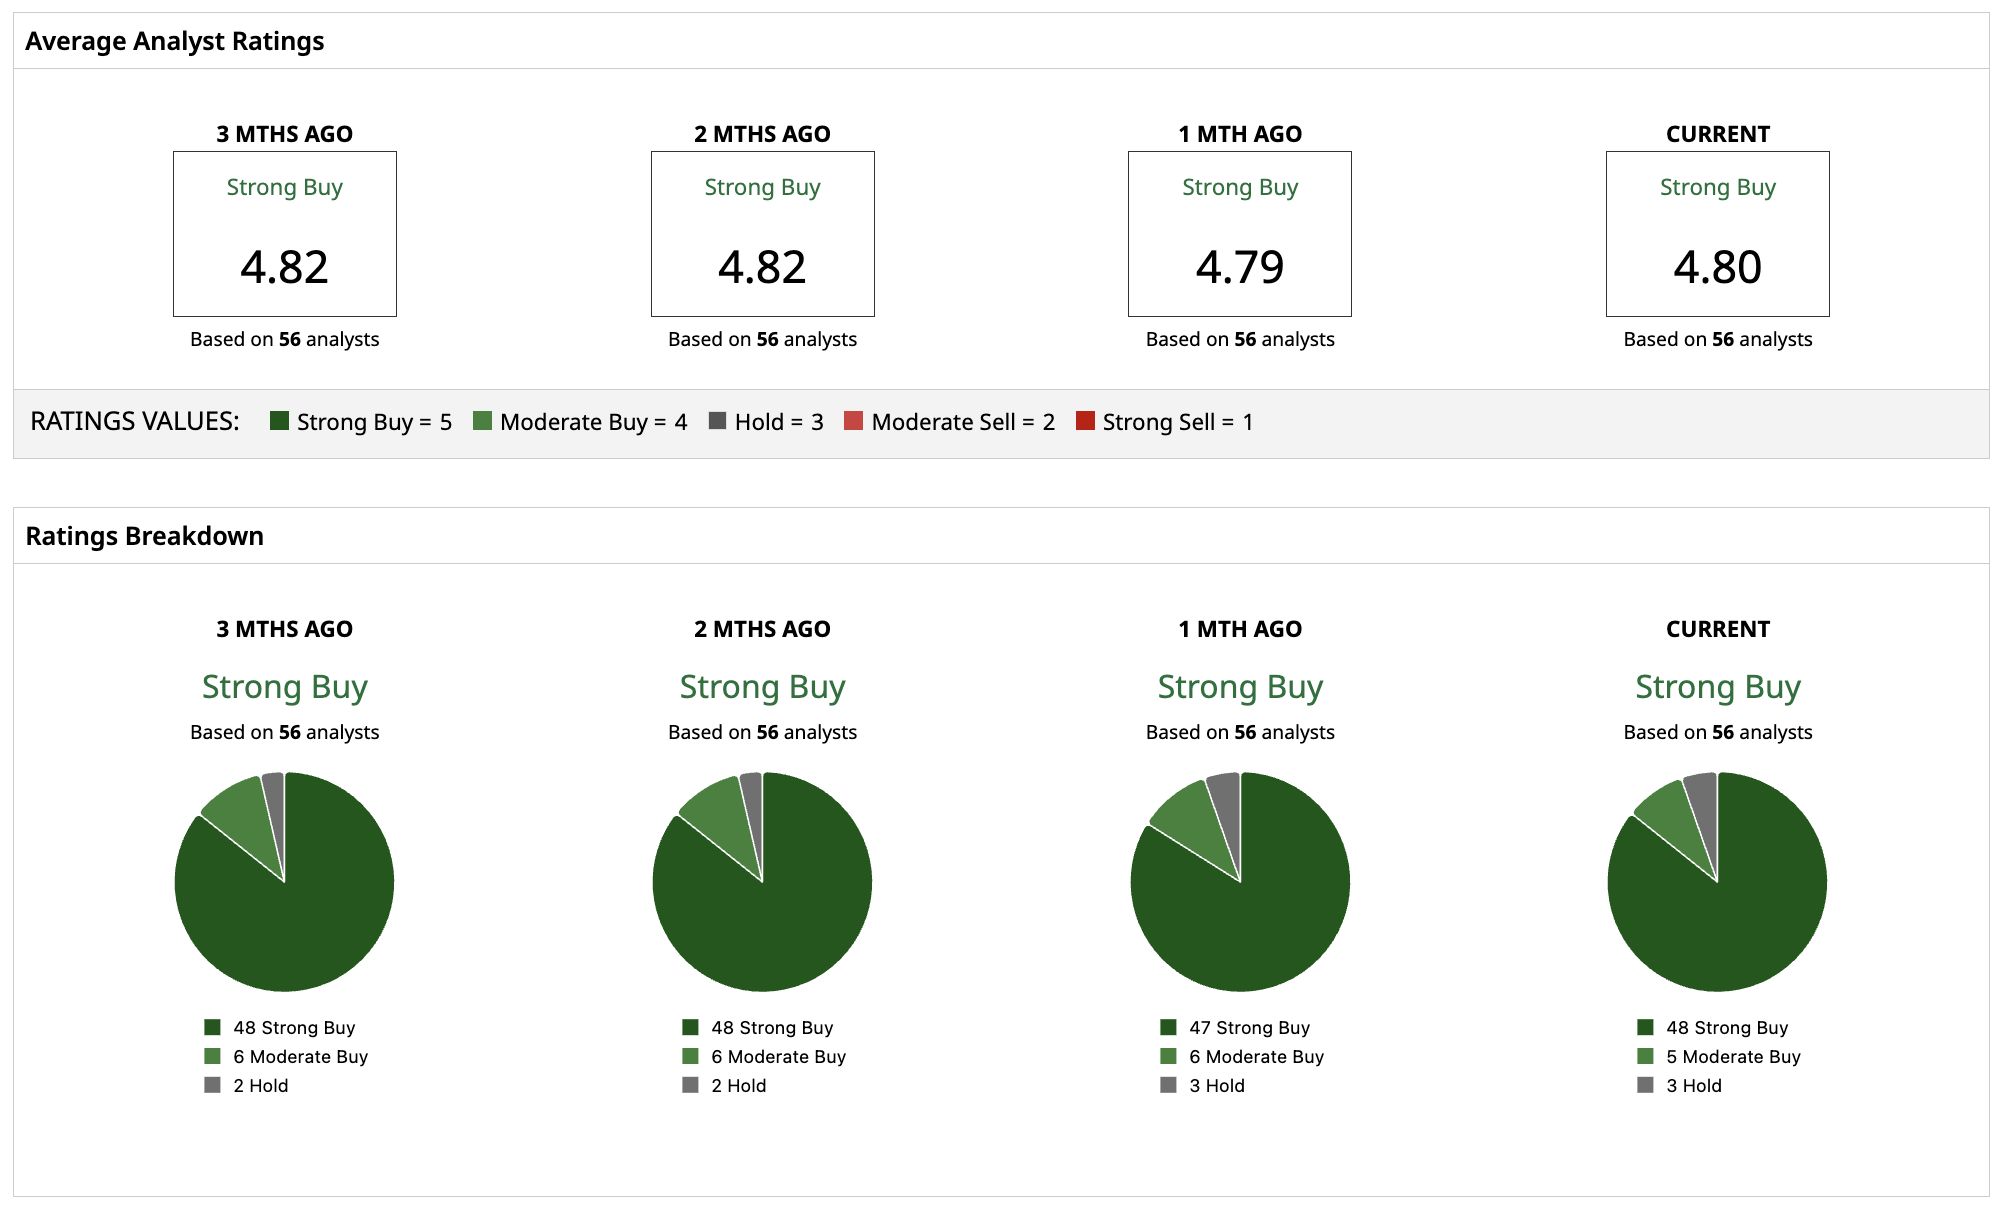
Based on 56 Wall Street analysts, Amazon holds a consensus “Strong Buy” rating with a mean price target of $328.33, still implying 26% upside despite the recent surge.
 www.barchart.com
On the date of publication, Jabran Kundi did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Andy Jassy Claims Amazon ‘May Have Two’ Trillion-Dollar Businesses. Here’s the Math Behind It. Option Volatility and Earnings Report For Nov 9-13 U.S. Stock Futures Gain as Oil Drop Offsets Nvidia Slump; Inflation Data Awaited Starlink Deal Adds Yet Another Growth Engine for Qualcomm Stock