

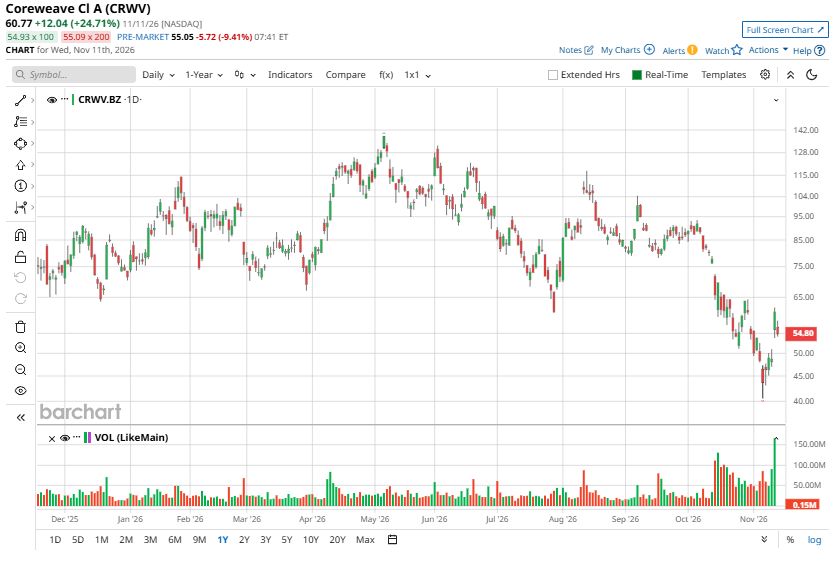
CoreWeave (CRWV) recently delivered a solid third-quarter performance, giving investors fresh reason to reconsider CRWV stock after a prolonged period of selling pressure. Shares closed roughly 25% higher on Nov. 11 following the earnings announcement as the artificial intelligence (AI) infrastructure provider reported exceptional revenue growth, expanding margins, and a significantly stronger business outlook.
More importantly, management's commentary offered greater visibility into customer demand, future revenue opportunities, and the company's financing strategy.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Notably, concerns about a potential slowdown in AI spending, mounting capex requirements, elevated interest expenses, and persistent cash burn have weighed heavily on CRWV stock. However, its latest results suggest that demand for AI computing infrastructure remains exceptionally strong and that the company is making meaningful progress toward improving profitability. The latest developments make a compelling case for a more constructive outlook on CoreWeave stock.
 www.barchart.com
Exceptional Revenue Growth Highlights AI Demand
CoreWeave reported Q3 revenue of $3.7 billion, up 168% year-over-year (YOY). The growth reflects strong demand for its AI cloud infrastructure and services, along with favorable pricing conditions.
Backlog reached $133 billion at the end of the quarter, up 138% YOY. Notably, more than half of the company's backlog is tied to contracts in which customer deliveries are expected to begin by the end of 2026. Further, demand continues to outpace capacity significantly, indicating solid growth ahead.
CoreWeave’s Expanding Margins Are a Positive
CoreWeave’s Q3 reflected improving operating leverage as its infrastructure footprint expands. Adjusted operating income reached $379 million in Q3, while adjusted operating margin was roughly 10%. This represents a substantial improvement from 5% in Q2 and just 1% in Q1 2026.
Several factors are contributing to this improvement. Strong demand and favorable pricing are supporting profitability, while the company's expanding scale provides greater flexibility to allocate computing capacity toward higher-margin opportunities.
CoreWeave is also benefiting from increasing adoption of its AI products and services. Customers are moving beyond experimentation and deploying AI applications in production environments, resulting in deeper engagement and higher spending.
Another important catalyst for the company's margins is revenue opportunity from renewing existing GPU contracts. CoreWeave said that over 130,000 GPUs are scheduled to come off contract in 2027, followed by approximately 170,000 in 2028. Management is already seeing a strong pipeline of customers competing for this capacity.
At current pricing levels, renewing the 2027 GPU contracts could generate nearly $4 billion in incremental annualized revenue without requiring additional capital expenditures. Including the 2028 renewals, this opportunity could hit $10 billion.
This could significantly improve the business' economics. CoreWeave is signing multiyear customer commitments that extend beyond the depreciable lives of its GPUs. As depreciation expenses decline while contractual pricing and operating costs remain relatively stable, margins could improve considerably during the later years of these agreements.
CoreWeave's Financing Strategy Addresses a Major Investor Concern
Despite the encouraging operating performance, financing remains an important consideration for investors. CoreWeave requires substantial capital to build data centers, acquire GPUs, and fulfill its growing customer commitments.
The company expects 2026 capital expenditures of $37 billion to $39 billion, highlighting the enormous investment required to support its expansion. Fourth-quarter interest expense is also projected at $1.05 billion to $1.15 billion.
However, management emphasized that its financing strategy is increasingly aligned with customer contracts, which will lower interest costs. At the end of Q3, its weighted average cost of debt was 7.9%, down 250 basis points from a year ago.
Higher Guidance Strengthens the Bull Case
CoreWeave raised its full-year 2026 revenue guidance to $13 billion to $13.3 billion and adjusted operating income guidance to $1.28 billion to $1.38 billion, a 26% increase at the midpoint versus its previous outlook. Management also expects the company to exit 2026 with an annualized revenue run rate (ARR) of $20 billion to $21 billion.
Most importantly, CoreWeave expects its adjusted net loss to moderate meaningfully in 2027 and anticipates achieving positive adjusted net income in the first half of 2028. Management also retains flexibility over the pace of future capex, allowing investments to be adjusted according to customer demand, financing availability, and expected returns.
What Do Analysts Think of CoreWeave Stock?
CoreWeave is well-positioned to deliver solid growth. The company should continue to benefit from record backlog, accelerating revenue, improving margins, and strong demand for AI computing capacity, while its GPU renewal opportunities and increasingly contract-backed financing strategy further strengthen the long-term investment thesis.
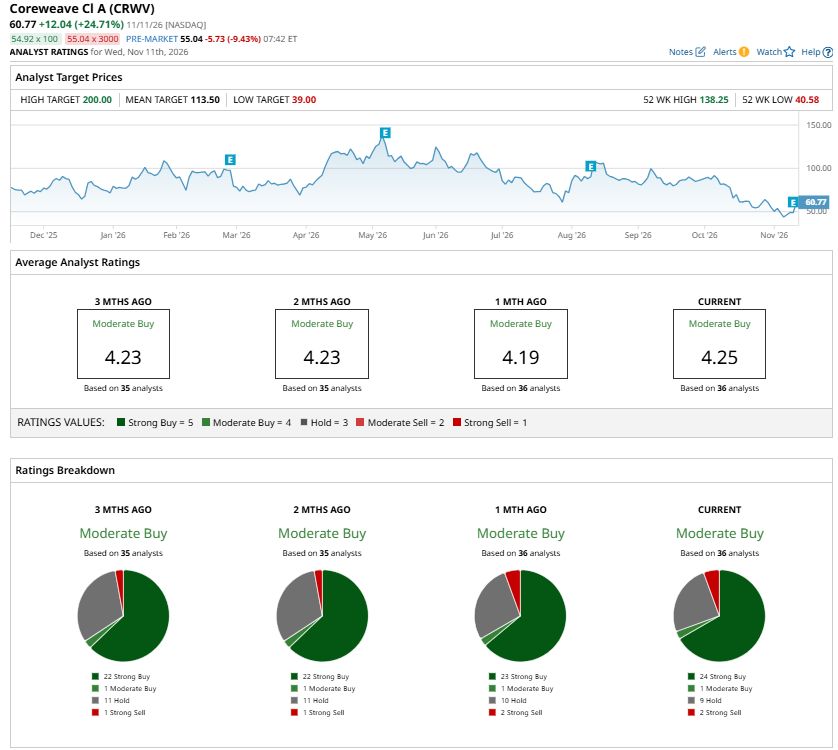
While substantial capital requirements, elevated interest expenses, and execution risks remain, the company’s improving operating performance, strong demand, and expected improvement in profitability warrant a positive view. Overall, analysts have a consensus “Moderate Buy” rating on CRWV stock.
 www.barchart.com
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why It’s Time to Load Up on CoreWeave Stock Dear AST SpaceMobile Stock Fans, Mark Your Calendars for November 17 Who Is Ian Buck? 10 Things to Know About the Nvidia Executive Investors Are Betting on to Replace Jensen Huang. Nvidia Fallout, Anthropic IPO and Other Can't Miss Items this Week