

AST SpaceMobile (ASTS) is facing a major test of investor confidence after its latest earnings report added fresh pressure to a stock already deep in correction territory. ASTS shares are down about 60.7% year-to-date (YTD), while the stock has also fallen sharply from its 52-week high.
The selling intensified after the company reported third-quarter results on Nov. 9, with revenue of $42.3 million falling short of the consensus estimate, while the company posted a net loss of $132.4 million. Although AST SpaceMobile maintained its 2026 revenue target of $150 million to $200 million and ended the quarter with roughly $3.2 billion in cash, investors remain concerned about heavy spending, launch execution, and the long path toward commercial-scale revenue.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
On the other hand, the company continues to advance its satellite constellation, targets initial intermittent nationwide service before year-end and has secured around $1 billion in non-dilutive Japanese funding. With ASTS now trading at significant lows, the key question for investors is whether this brutal selloff represents a compelling entry point or a warning that more downside could lie ahead.
About AST SpaceMobile Stock
AST SpaceMobile is a Midland, Texas-based space technology company developing a space-based cellular broadband network designed to connect directly with everyday smartphones, enabling 4G and 5G connectivity in areas outside traditional terrestrial mobile coverage. The company is building its BlueBird satellite constellation and works with mobile network operators to extend wireless coverage globally, while also pursuing commercial and government applications. ASTS has a market cap of approximately $11.1 billion.
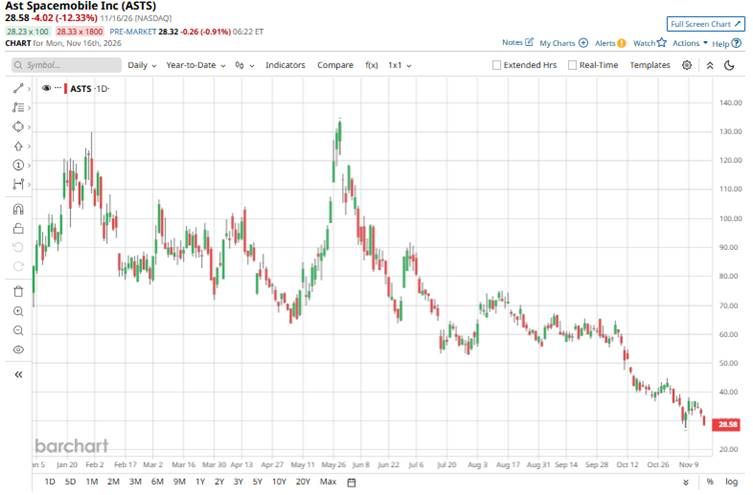
ASTS has endured a brutal 2026, with the stock down 60.7% YTD and 53.5% over the past year. The decline has left shares about 78.7% below their 52-week high of $133.86, underscoring just how dramatically investor sentiment has deteriorated. ASTS closed at $28.58 on Nov. 16, after falling another 12.3% in the latest session.
The selling pressure has been particularly intense around the company’s third-quarter earnings report. ASTS initially climbed 14.1% on Nov. 9 to $36.89, although the earnings report itself was released after the market close. The rally appears to have reflected optimism surrounding the company’s satellite rollout and commercial opportunity. However, that optimism quickly reversed once investors digested the results.
Shares subsequently plunged 8.7% on Nov. 10, as investors focused on the revenue miss, continued losses, heavy spending and execution risks. Also, competition from SpaceX (SPCX) expanding direct-to-cell ambitions has remained a major overhang.
While ASTS then rebounded 8.7% on Nov. 11, the recovery proved short-lived as ASTS fell another 5.8% on Nov. 12, followed by a 5.5% decline on Nov. 13 and 12.3% in the last session. The latter decline came without a major new company-specific announcement, suggesting that investors were continuing to digest the earnings disappointment and reassess the stock’s risk-reward profile.
 www.barchart.com
Despite the selloff, the stock is currently trading at 189.32 times sales, which is a premium to industry peers.
Revenue Surges, but Losses and Spending Remain Elevated
AST SpaceMobile reported its third-quarter 2026 results on Nov. 9, delivering revenue growth of 187.1% year-over-year (YOY) to $42.3 million. Product revenue increased to $20.6 million from $7.7 million, while services revenue climbed to $21.8 million from $7 million. The company said the quarterly revenue increase was driven primarily by gateway deliveries and milestones achieved under U.S. government contracts. For the first nine months of 2026, revenue reached $88.6 million, up from $16.6 million in the comparable period of 2025.
The sharp increase in revenue, however, was accompanied by a substantial rise in expenses. Total operating expenses jumped 123.5% to $211 million. Moreover, AST SpaceMobile’s bottom line remained deeply negative. Net loss attributable to common stockholders widened to $132.4 million, or $0.44 per share, from $122.9 million, or $0.45 per share, in Q3 2025 and missed expectations.
The pressure on profitability becomes even clearer when looking at the first nine months. AST SpaceMobile generated $88.6 million of revenue through September, but its net loss attributable to common stockholders expanded to $554.3 million from $268 million. Total operating expenses reached $704.3 million, compared with $232 million in the first nine months of 2025.
The balance sheet nevertheless remains a key positive. AST SpaceMobile ended September with approximately $3.2 billion in cash, cash equivalents and restricted cash, versus roughly $1.2 billion in cash and restricted cash at the end of Q3 2025. Plus, capital intensity has increased substantially, with gross capitalized property and equipment reaching approximately $2.6 billion. Long-term debt also increased to $4.1 billion from $2.2 billion at the end of 2025, underscoring the financing requirements associated with the company’s aggressive expansion.
Moreover, AST SpaceMobile reiterated its 2026 revenue target of $150 million to $200 million, while noting that recently signed contracts could provide upside to that range. Management also expects to activate initial intermittent nationwide service in the United States and other key markets before the end of 2026. The company is targeting approximately 45 BlueBird satellites in orbit by mid-2027 and expects to reach a production run rate of six ASIC-enabled satellites per month in December 2026.
Beyond the financial numbers, AST SpaceMobile announced several developments that could strengthen its long-term growth opportunity. The company secured approximately $1 billion in non-dilutive funding from Japan for satellite manufacturing and launches, while also announcing its Blacklift 20-ton reusable rocket, with launches targeted to begin in late 2028. It also said launch agreements now cover more than 100 BlueBird satellites expected to be deployed during 2027 and 2028.
In addition, analysts forecast a loss per share of about $1.95 for fiscal 2026, a 45.5% YOY deterioration, and a 27.7% improvement to $1.41 in 2027.
What Do Analysts Expect for AST SpaceMobile Stock?
Recently, Analyst Michael Funk from Bank of America maintained a “Neutral” rating on AST SpaceMobile but sharply reduced the price target to $45 from $80 following the company’s third-quarter results.
Also, UBS cut its AST SpaceMobile price target to $43 from $78 while maintaining a “Neutral” rating, one day after the company reported its third-quarter results. The lower target primarily reflects increased execution risk and delays in scaling AST SpaceMobile’s satellite constellation.
On the other hand, last month, Scotiabank analyst Andres Coello upgraded AST SpaceMobile from “Sector Perform” to “Sector Outperform” and raised the price target to $55.70 from $50.80, despite a steep selloff in ASTS shares, which Scotiabank viewed as having made the stock’s valuation more attractive.
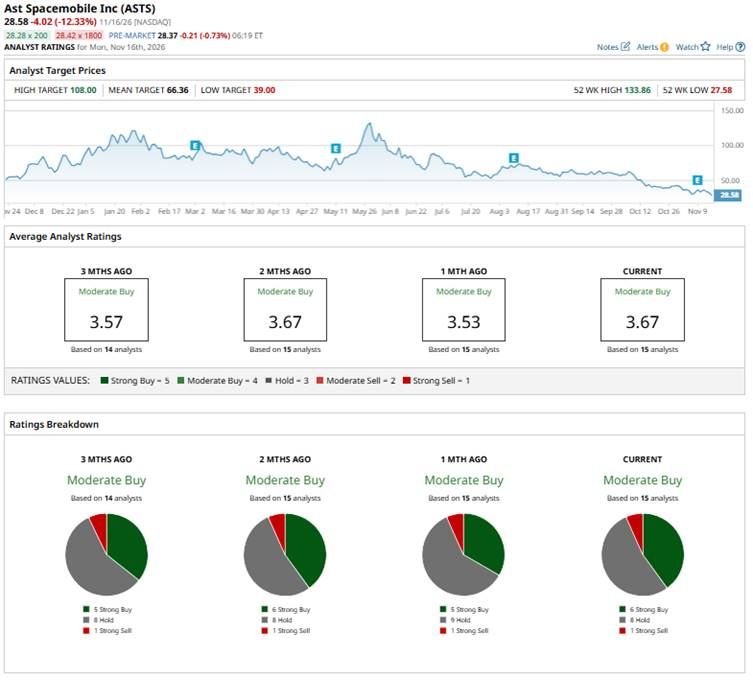
Overall, ASTS has a consensus “Moderate Buy” rating. Of the 15 analysts covering the stock, six advise a “Strong Buy,” eight analysts are on the sidelines, giving it a “Hold” rating, and one recommends a “Strong Sell.”
ASTS’ average analyst price target of $66.36 indicates an upside of 132.2%, while the Street-high target price of $108 suggests that the stock could rally as much as 277.9%.
 www.barchart.com
On the date of publication, Subhasree Kar did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘I Would Be Honored to Answer These Calls and Return as CEO,’ Jensen Huang Says as Employees, Fellow Tech Leaders Rally Behind the Nvidia Founder Billionaire Charlie Munger Called Robinhood ‘A Gambling Parlor Masquerading As a Respectable Business’ and Now They Hold 70 Million Trump Accounts A Strong Q3 Puts Nvidia (NVDA) Stock on Track for a Quick 194% Options Payout As Netflix Stock Hovers Near Its 52-Week Low, Analyst Sentiment Remains Mixed. Here's Why.