

Chip giant Nvidia (NVDA) is at the center of Wall Street’s biggest discussion right now after ex-CEO Jensen Huang was found to have extramarital affairs, including one with an alleged Chinese spy.
In connection with that, Huang is set to appear for a transcribed interview with several House committees on Dec. 1 to gauge whether his actions could breach national security. He is expected to face questions about his relationship with Alice Huang and Nvidia’s chip sales to Singapore-based Megaspeed.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Amid all this, Nvidia reported solid Q3 results, with the Vera Rubin infrastructure ramp well underway. In its earnings call, the company made it clear that it does not intend to reinstate Huang as CEO, despite his solid track record at Nvidia’s helm for more than three decades.
Meanwhile, the Commerce Department introduced stricter export rules intended to stop China from obtaining advanced AI chips through data centers in third-party countries. Nvidia’s board said that it had created a new committee to oversee national security and export control compliance, ensuring the company follows global trade rules.
At this juncture, Huang’s Dec. 1 appearance on Capitol Hill is important, as it could show whether the security risk affects Nvidia's shipments in the future.
About Nvidia Stock
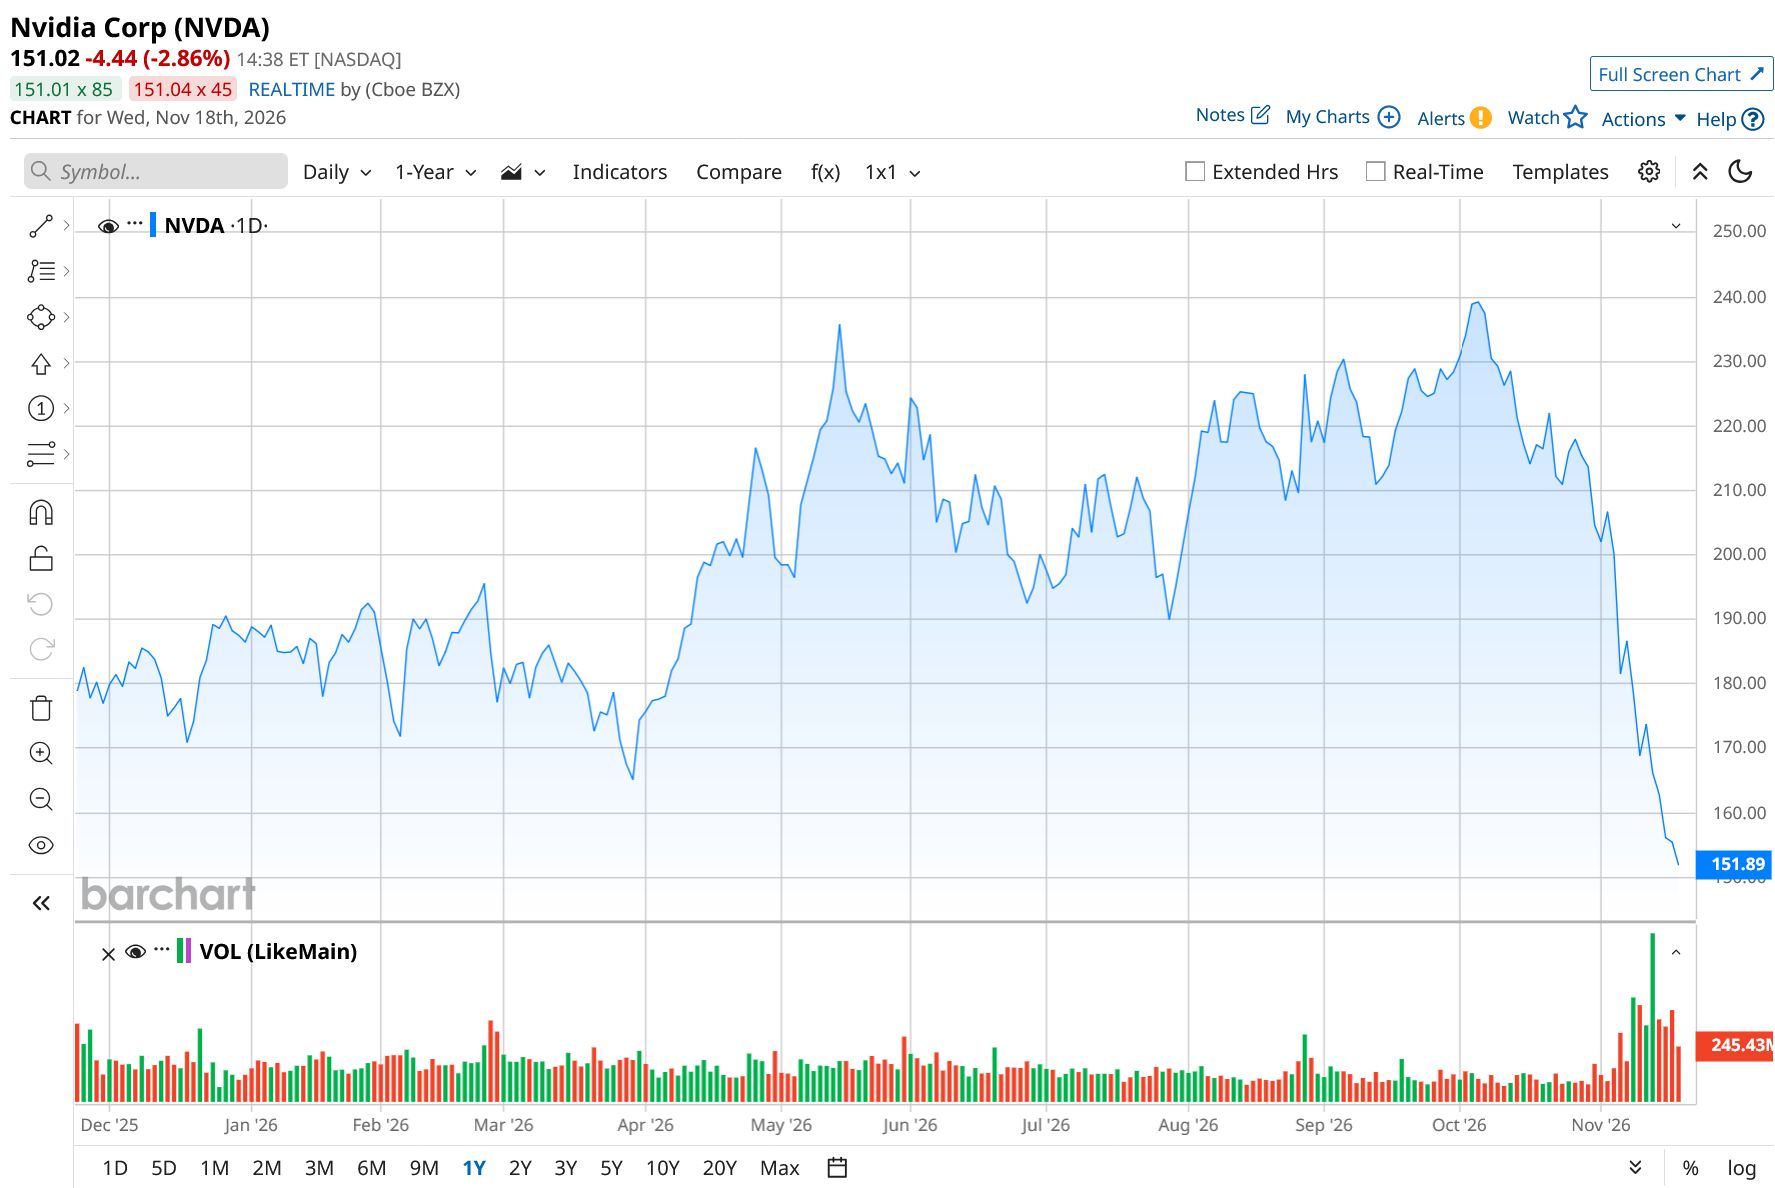
Nvidia, headquartered in Santa Clara, California, is the world’s largest company by market value and a dominant force in AI chipmaking. Its stock has recently come under pressure after Huang’s resignation, with shares falling sharply and its market capitalization dipping below $4 trillion (to $3.75 trillion), raising questions about leadership stability despite continued strong demand for its AI GPUs.
Nvidia’s stock has declined over the past year as investors have begun questioning whether the AI boom can keep expanding fast enough to justify its price tag, although the company’s growth remains strong. NVDA stock has dropped 16% over the past 52 weeks and 32% over the past six months. The decline reflects valuation pressure, slowing expected AI infrastructure spending, export-control risk, and recent leadership uncertainty. It reached a 52-week low of $148.80 on Nov. 12, but is up 2% from that level.
The recent selloff has brought down Nvidia’s valuation, but it still isn't cheap. Its forward-adjusted price-to-earnings (non-GAAP) ratio of 16.64x is lower than the industry average of 18.81x.
 www.barchart.com
Strong Q3 as AI Demand Holds
Nvidia reported another quarter of exceptional growth as AI demand continued to advance. For the third quarter of fiscal 2027 (quarter ended Oct. 25), the company’s revenue rose 103% year-over-year (YoY) to $115.8 billion, beating Wall Street's $108.19 billion estimate. This was, of course, based on data center revenue growing 110% YoY to $107.60 billion.
Nvidia's Vera Rubin NVL72 started shipping in the third quarter, alongside expansion of the Vera Rubin cloud ecosystem, reporting an “explosive start.” In addition, Nvidia deepened its relationships with supply chain partners to secure AI infrastructure buildout.
Top-line growth also showed up in bottom-line earnings, as non-GAAP operating income rose 116% YoY to $77.90 billion. Its non-GAAP EPS was $2.68, up 111% from the prior-year period and higher than the $2.47 that Street analysts had expected.
In September, Nvidia increased its share repurchase authorization by $150 billion. The chip giant also issued an upbeat outlook, expecting $130 billion in revenue for Q4 FY2027, plus or minus 3% (without assuming any data center compute revenue from China). Wall Street analysts expect EPS to climb 73.3% YoY to $2.72 for Q4 FY2027. For fiscal 2027, EPS is projected to surge 102.6% YoY to $9.26, followed by 67.9% growth to $15.55 in fiscal 2028.
What Do Analysts Think About NVDA Stock?
After the company’s solid Q3 results, Stifel analysts maintained a “Buy” rating and a $205 price target on NVDA stock. The analysts noted that Nvidia is shifting capital allocation from customer financing to supplier prepayments, while networking revenue has grown as co-packaged optics enter volume production.
Meanwhile, analysts at Morgan Stanley lowered the price target from $267 to $260 while keeping an “Overweight” rating, citing uncertainty from potential Commerce Department measures, reported investigations by the DOJ and the SEC, and Nvidia’s internal review of the CEO transition. Wells Fargo analysts also maintained an “Overweight” rating but lowered the price target from $300 to $250.
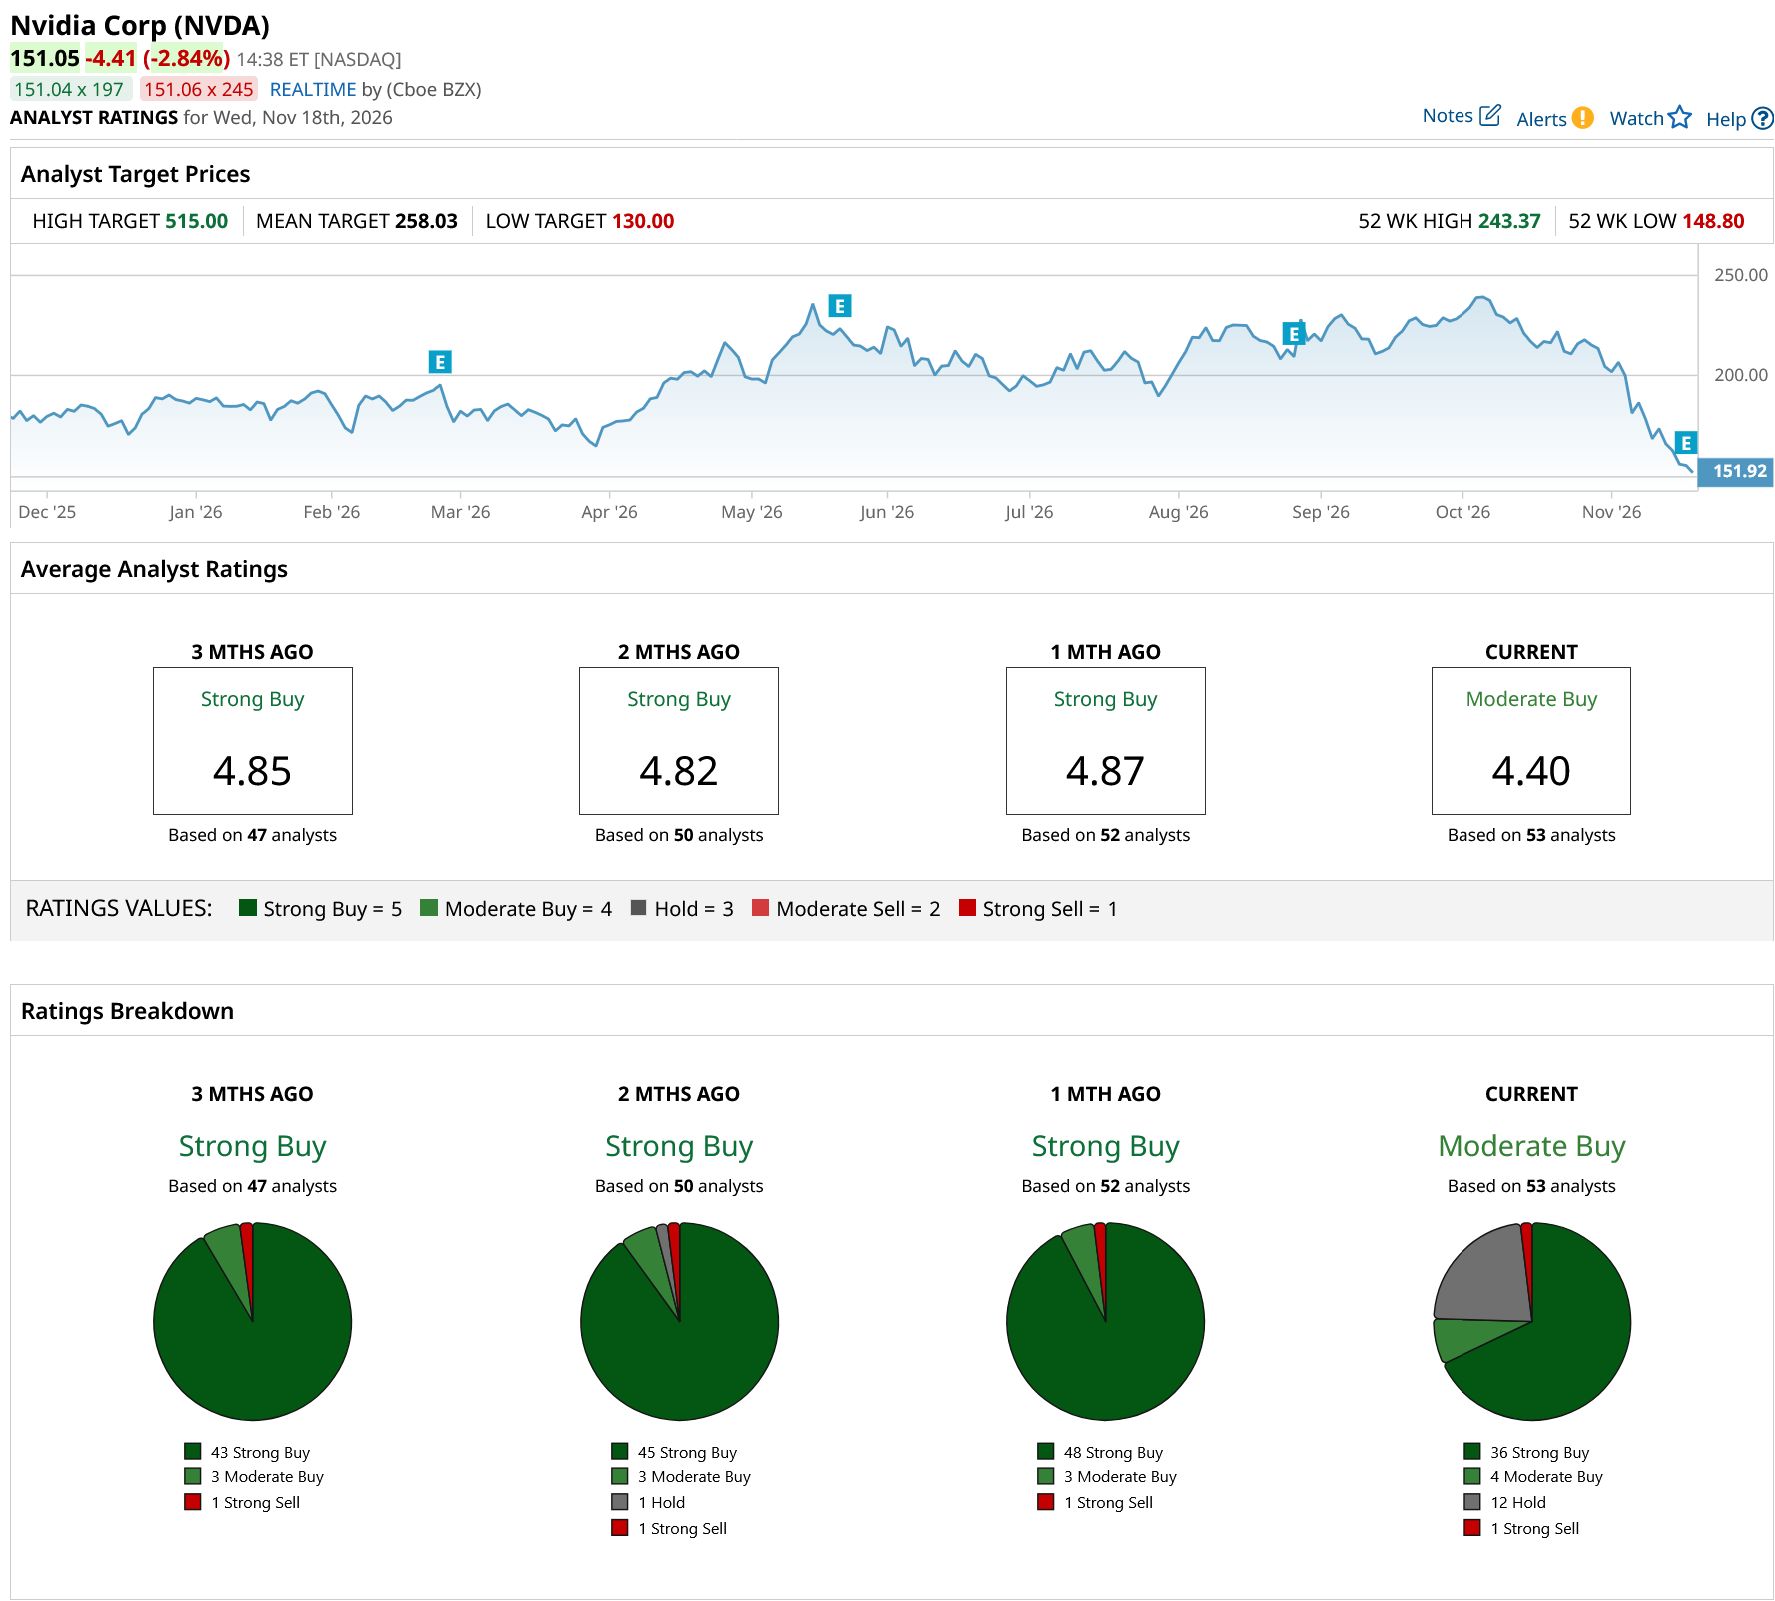
Nvidia has been in the spotlight on Wall Street for some time, with analysts awarding it a consensus “Moderate Buy” rating. Of the 53 analysts rating NVDA stock, 36 rate it a “Strong Buy,” four rate it a “Moderate Buy,” 12 analysts take a middle-of-the-road approach with a “Hold,” and only one analyst gives it a “Strong Sell” rating. However, the overall rating has turned from “Strong Buy” to “Moderate Buy” over the past month. The consensus price target of $258.03 represents 71% upside from current levels. Moreover, the Street-high price target of $515 indicates a 241% upside.
 www.barchart.com
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
I Used This Options Strategy to Profit from the Post-IPO Plunge in SpaceX. Now I’ll Use It Again on ANT Stock After Anthropic Starts Trading. Alphabet Stock Is Falling. Here’s Why Investors Should Be Buying the Dip. Dear Nvidia Stock Fans, Mark Your Calendars for December 1 Ahead of Intuit Earnings, Here's What Barchart Data Says Comes Next for INTU Stock