

The Iran war shock is driving crude oil prices higher, with West Texas Intermediate (“WTI”) trading above $100 per barrel, according to data from Oilprice.com. The high crude price has significantly increased input costs for refiners such as Valero Energy Corporation VLO. However, unlike many refiners, Valero Energy has a heavy-crude advantage, as heavy crude is cheaper than light crude like WTI.
Regarding the company’s access to diverse crude feedstocks, Valero has an advantage because its Gulf Coast refineries can buy crude oil from many low-cost sources, including the United States, Canada and Venezuela. This gives the company more flexibility to purchase cheaper oil, which helps keep refining costs low and can boost profits when competitors have fewer sourcing options.
Also, global refining capacity is constrained and fuel inventories are low. On the demand side, gasoline, diesel and jet fuel remain resilient. This means people are still driving and flying quite often, while diesel demand suggests transportation, freight, agriculture and industrial activity are still holding up. As a result, with busy refineries and fuel not in abundant supply, refining margins for refiners like VLO are likely to remain strong.
Will PSX and PARR Also Gain?
The favorable business environment is also likely to benefit refiners such as Phillips 66 PSX and Par Pacific Holdings, Inc. PARR.
On its second-quarter 2026 earnings call, PSX noted that there aren’t enough refineries or products globally right now because much refining capacity is offline and fuel inventories are low. China is also exporting less fuel than usual. This shortage helps keep refining margins, also called crack spreads, high. PSX believes these shortages may take longer to resolve than in 2022, which could keep the energy major’s refining profits strong into the September quarter and potentially 2027.
Coming to Par Pacific, the company continued to benefit from a strong refining market at the start of the third quarter. Its refining index, which is a rough measure of how profitable it is to turn crude oil into products like gasoline and diesel, was still very high in July at $31.34 per barrel, slightly below the second-quarter average of about $33.
VLO’s Price Performance, Valuation & Estimates
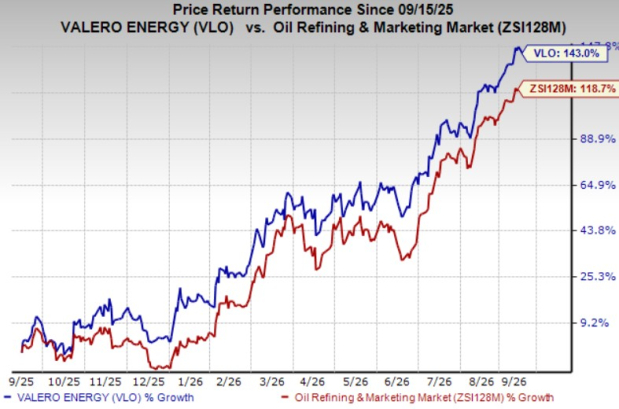
Shares of VLO have gained 143% over the past year compared with the industry’s growth of 118.7%.
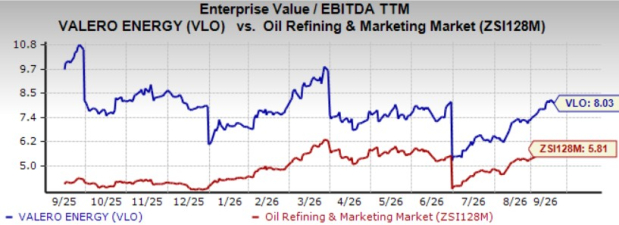
From a valuation standpoint, VLO trades at a trailing 12-month enterprise value to EBITDA (EV/EBITDA) of 8.03X. This is above the broader industry average of 5.81X.
The Zacks Consensus Estimate for Valero’s 2026 earnings hasn’t seen any revisions over the past seven days.
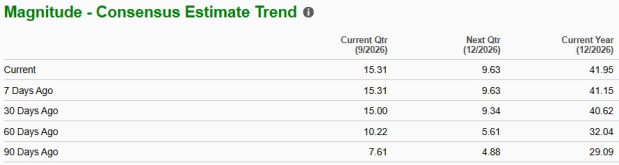
VLO currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Valero Energy Corporation (VLO): Free Stock Analysis Report
Phillips 66 (PSX): Free Stock Analysis Report
Par Pacific Holdings, Inc. (PARR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).