

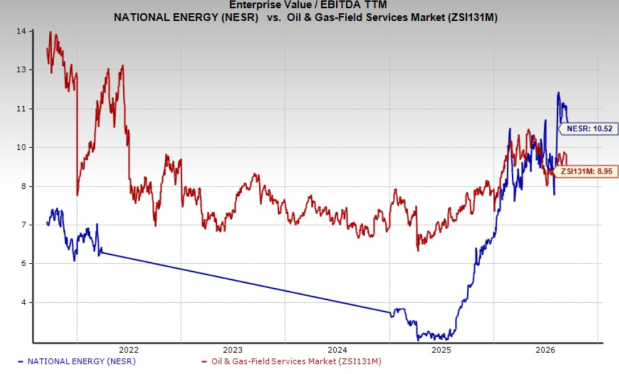
National Energy Services Reunited NESR is trading at a premium, indicating that investors are willing to pay more for the stock. On a relative basis, NESR is trading at a trailing 12-month Enterprise Value to Earnings Before Interest, Taxes, Depreciation and Amortization (EV/EBITDA) multiple of 10.52X, higher than the broader industry average of 8.95X. Baker Hughes Company BKR and Halliburton HAL, which are two other oilfield service players in the same space, are trading at 11.69X and 8.48X, respectively.
Image Source: Zacks Investment Research
Given that the oilfield service player commands a premium valuation, what should investors do now? Before getting into that, let us take a closer look at the company’s fundamentals and overall business environment.
Can Strong Oil Prices Benefit NESR’s Operations?
The oil-pricing environment remains favorable for National Energy Services. The U.S. Energy Information Administration (“EIA”) expects WTI crude to average $84.65 per barrel in 2026, sharply higher than $65.40 in 2025, while Brent is projected to average $91.01 per barrel this year. Among other factors, elevated prices reflect constrained Middle East oil exports and significant inventory drawdowns amid ongoing regional conflicts.
A stronger oil-price environment should generally encourage National Energy Services’ customers to spend more on exploration, field development and production activities, supporting the demand for oilfield services. NESR itself identifies oil prices and rig count as key operational indicators, with customer spending heavily influenced by expectations for future oil prices.
Importantly, NESR is one of the largest oilfield service providers in the Middle East and North Africa, with operations across Saudi Arabia, Oman, Kuwait, the UAE, Iraq, Algeria, Egypt and Libya. Its offerings include production services, such as hydraulic fracturing, coiled tubing, cementing, artificial lift and completions, as well as Drilling and Evaluation Services, including rigs, directional drilling, well testing and wireline services.
Nearly 99% of National Energy Services’ revenues are generated in the MENA region, where producers benefit from some of the world’s lowest production breakeven costs and have historically maintained investment through commodity cycles. Against this backdrop, sustained high oil prices could further strengthen customer spending capacity and support drilling, completion and production activity, creating a favorable demand environment for National Energy Services’ broad service portfolio.
Recent Contract Wins & Technology Expansion Support Growth
NESR’s recent contract wins represent another important growth catalyst. The company highlighted a $300-million well-testing and Ahmadi Innovation Valley (“AIV”) technology contract in Kuwait, alongside several other long-term service awards across its core markets.
The AIV agreement is particularly significant as it places National Energy Services within a long-term technology framework that provides access to dedicated innovation spending and opportunities to commercialize solutions across drilling, flow assurance, heavy oil, industrial inspection, enhanced recovery and unconventional resources.
These awards are likely to strengthen NESR’s backlog and revenue visibility while expanding its technology-led offerings and presence in Kuwait. Management also expects the continued ramp-up of the Jafurah contract and recent awards across Kuwait, the UAE and North Africa to support strong year-over-year revenue growth.
This momentum also advances the company’s 3B3 strategy, under which National Energy Services is targeting a $3-billion revenue run rate after reaching its $2-billion annualized milestone ahead of schedule.
Estimates Reflect Continued Earnings Growth
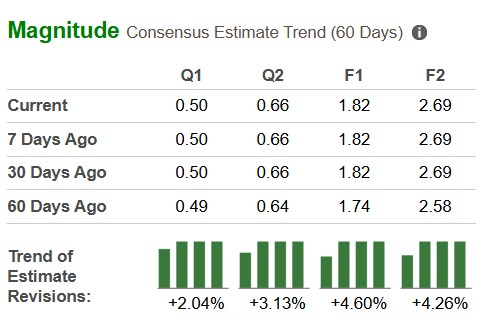
Analyst sentiment toward NESR has become increasingly constructive in recent months. The Zacks Consensus Estimate for 2026 revenues stands at $2.03 billion, implying 53.5% year-over-year growth. Earnings are projected to reach $1.82 per share, indicating an impressive 122% surge from the prior year’s actual.
For 2027, the consensus estimate calls for an additional 23.3% year-over-year increase in revenues, while earnings are expected to grow 47.8%.
Reflecting improved confidence in the company’s outlook, earnings estimates have also moved higher. Over the past 60 days, the consensus estimate for earnings per share has increased 4.6% for 2026 and 4.26% for 2027.
What Should Investors Do Now?
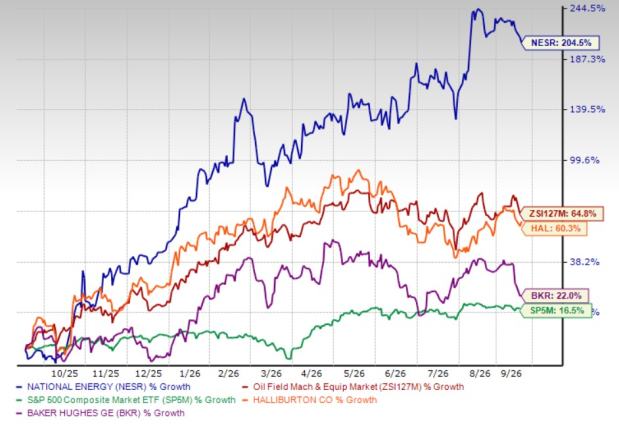
The positive developments are reflected in National Energy Services’ share price performance. Over the past year, the NESR stock has skyrocketed 204.5%, significantly outperforming the industry’s 64.8% surge. Meanwhile, BKR and HAL have gained 22% and 60.3%, respectively.
Although National Energy Services is trading at a premium to the broader industry, its strong operating backdrop, sizable contract wins, expanding technology capabilities and robust earnings-growth expectations provide support for the higher valuation. Continued strength in Middle East oilfield activity, coupled with improving revenue visibility and upward earnings-estimate revisions, further strengthens the investment case.
Thus, investors willing to pay a premium for a company with strong growth prospects may consider adding the NESR stock to their portfolios. The stock currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
National Energy Services Reunited (NESR): Free Stock Analysis Report
Halliburton Company (HAL): Free Stock Analysis Report
Baker Hughes Company (BKR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).