

Johnson & Johnson JNJ stock has risen 18.3% in the past three months, backed by improving earnings and sales, a raised 2026 outlook, strong performance from newer medicines, pipeline wins and progress toward reducing the long-running uncertainty surrounding talc litigation.
However, to make an informed decision on whether to buy, sell or hold the stock amid the recent price increase, it is better to assess J&J’s overall fundamentals and analyze its strengths and weaknesses.
Innovative Medicine Drives J&J’s Growth Despite Stelara LOE
J&J’s Innovative Medicine segment is the company’s primary growth engine. Innovative Medicine segment sales rose 6.2% on an organic basis in the first half of 2026, despite the loss of exclusivity (LOE) of the blockbuster drug, Stelara. Growth was driven by J&J’s key drugs like Darzalex, Erleada and Tremfya. New drugs like Carvykti, Tecvayli, Talvey, Rybrevant and Spravato also contributed significantly to growth.
The segment recorded five consecutive quarters of sales of more than $15 billion despite the LOE of Stelara.
J&J expects its Innovative Medicine segment to remain a key growth driver in the second half of 2026. The growth is expected to be driven by its key products, such as Darzalex, Tremfya, Spravato, Carvykti and Erleada, as well as increased contribution from new launches like Icotyde, Rybrevant and Inlexzo, which can offset the ongoing impact of Stelara biosimilar competition. J&J expects continued above-market growth through the remainder of 2026.
J&J’s New Launches Strengthen Its Product Portfolio
J&J also rapidly advanced its pipeline in the past year, attaining significant clinical and regulatory milestones that will help drive growth through the back half of the decade. In the past year, it has gained approval for new products like Inlexzoh, a first-of-its-kind drug-releasing system for treating high-risk non-muscle invasive bladder cancer, Imaavy (nipocalimab) for treating generalized myasthenia gravis and Icotyde, an oral targeted peptide inhibitor of the IL-23 receptor for treating moderate-to-severe plaque psoriasis (PsO). J&J markets Icotyde in partnership with Protagonist Therapeutics PTGX.
J&J believes that nipocalimab has pipeline-in-a-product potential and Protagonist Therapeutics-partnered Icotyde has the potential to revolutionize the treatment of plaque psoriasis with a once-a-day pill. It has the potential to be J&J’s largest product ever, with $10 billion in sales potential.
On the second-quarter conference call, J&J said that it is seeing strong launches of all these new drugs, Inlexzo, Icotyde as well as Imaavy.
J&J’s new cancer drugs, Carvykti, Tecvayli, Talvey and Rybrevant/Lazcluze are contributing significantly to top-line growth, driven by market share gains. Combined, they generated $2.6 billion in sales in the first half of 2026.
J&J believes 10 of its new products in the Innovative Medicine segment have the potential to deliver peak sales of $5 billion, including Talvey, Tecvayli, Imaavy, Caplyta, Inlexzo, Rybrevant, plus Lazcluze and Icotyde.
J&J’s MedTech Business Faces Some Near-Term Headwinds
J&J’s MedTech business is performing well, but its growth has moderated. In the second quarter of 2026, MedTech sales rose 4.5% year over year to $8.93 billion, while operational sales growth was 3.6%. This was below the 6.8% operational growth delivered by Innovative Medicine, making MedTech the slower-growing of J&J’s two major businesses.
Cardiovascular was a weaker area in the quarter. Operational sales in the business grew 3.1%, as competitive pressure in electrophysiology and lower Abiomed sales offset continued double-digit growth at Shockwave.
Abiomed sales declined 2% as procedure volumes slowed following changes in Impella usage after a recent U.K. clinical trial raised questions about the device’s benefit in certain high-risk procedures, prompting physicians to reassess patient selection and adopt a more cautious approach to using the device.
J&J expects only modest Abiomed growth in the second half of 2026, with the impact of the study likely to persist until PROTECT IV study data are presented in 2027. PROTECT IV is a large clinical study of the company’s Impella device in high-risk percutaneous coronary intervention.
Meanwhile, the company continues to face headwinds in China from the government's volume-based procurement program and expects these pressures to continue through 2026, particularly in the second half.
Nonetheless, while J&J’s Cardiovascular sales slowed down in the second quarter due to weakness in Abiomed, its other three businesses, Surgery, Vision and Orthopedics, all accelerated in the quarter and performed above expectations. J&J claimed that overall procedure volumes were stable and there was no broad-based slowdown in medical procedure volumes across its MedTech business.
Patent Expiration of J&J’s Drug Stelara & Other Headwinds
J&J lost U.S. patent exclusivity of Stelara in 2025. Stelara was a key top-line driver for J&J, accounting for around 18% of J&J’s Innovative Medicine unit’s sales in 2024, before it lost patent exclusivity in 2025.
Several biosimilar versions of Stelara were launched in the United States in 2025 as the drug lost patent exclusivity.
Stelara’s LOE negatively impacted the Innovative Medicine segment’s growth by 10.4% in 2025, 9.2% in the first quarter and 7.6% in the second quarter of 2026. J&J also expects generic impact for both Simponi and Opsumit to begin in 2026 as the drugs lose patent protection.
J&J faces approximately 76,000 lawsuits for its talc-based products, primarily baby powders. The lawsuits allege that its talc products contain asbestos, which caused many women to develop ovarian cancer. While the company has taken steps to resolve many of these matters, litigation has remained an overhang for a long time that has resulted in high costs, negative headlines and weighed on investor sentiment. However, J&J has seen some positive developments recently surrounding its long-running talc litigation.
In July 2026, J&J agreed to a $5.5 billion settlement covering nearly all its remaining talc litigation. The agreement requires participation by plaintiff firms representing at least 95% of the remaining claims before it becomes effective. J&J expects the first payment of up to $3 billion in 2027, with additional payments beginning in 2028.
J&J Stock Price, Valuation and Estimates
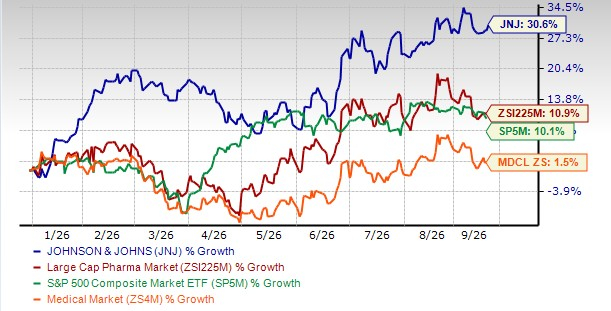
J&J’s shares have outperformed the industry so far this year. The stock has risen 30.6% this year compared with 10.9% appreciation of the industry. The stock has also outperformed the sector and the S&P 500 Index, as seen in the chart below.
JNJ Stock Outperforms Industry, Sector & S&P 500
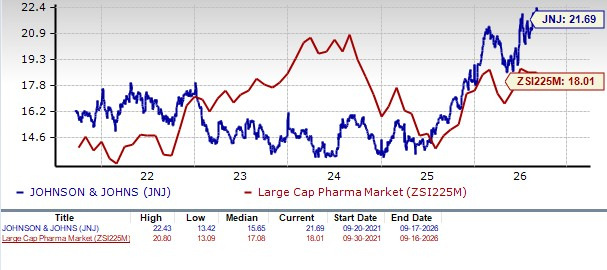
J&J is steeply valued. Going by the price/earnings ratio, the company’s shares currently trade at 21.69 forward earnings, higher than 18.01 for the industry. The stock is also trading above its five-year mean of 15.65. J&J stock is cheaper than only two large drugmakers, Eli Lilly LLY and Gilead GILD.
JNJ Stock Valuation
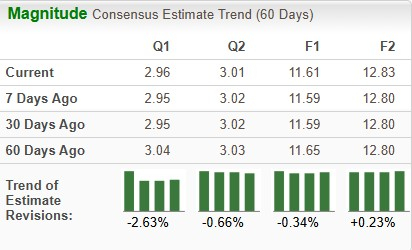
The Zacks Consensus Estimate for 2026 earnings per share has risen from $11.59 to $11.61 over the past 30 days, while that for 2027 has gone up from $12.80 per share to $12.83 per share over the same time frame.
JNJ Estimate Movement
Stay Invested in J&J’s Stock
J&J’s biggest strength is its diversified business model, as it operates through pharmaceuticals and medical devices divisions, which reduces dependence on any single product or market. It has more than 275 subsidiaries and boasts 28 platforms or products with more than $1 billion in annual sales, with the aim of adding even more. Its diversification helps it withstand economic cycles more effectively. It also boasts strong cash flows and has increased its dividends for 64 consecutive years. J&J believes that the depth of its portfolio and pipeline is stronger than ever.
The company expects 2026 to be a year of accelerated growth. The company is confident that it can achieve its target of generating around $100 billion in revenues in 2026, with $49.4 billion already generated in the first half. It expects sales to continue to improve in 2027, with a “line of sight” to double-digit growth by the end of the decade. J&J believes that it is already achieving this growth. Though J&J’s total revenues are currently rising in a mid-single-digit range, excluding Stelara, J&J’s top line grew in a double-digit range in both the first and second quarters of 2026.
J&J also expects its MedTech business to perform better in the second half of the year than it did in the first half, driven by strength in Vision, Orthopedics, Surgery and better performance in Cardiovascular. While the Abiomed softness creates a new overhang, it is only 2% of sales, and J&J has various other top-line drivers to compensate.
J&J faces its share of headwinds like the Stelara patent cliff, the upcoming LOE of key drugs Opsumit and Simponi, and softness in MedTech. Though the litigation issue is close to resolution, it has not yet been fully resolved. However, J&J looks quite confident that it will be able to navigate these challenges.
J&J’s price appreciation, rising estimates, consistent earnings and sales growth, important new launches and pipeline depth suggest that one should stay invested in this Zacks Rank #3 (Hold) stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Johnson & Johnson (JNJ): Free Stock Analysis Report
Eli Lilly and Company (LLY): Free Stock Analysis Report
Gilead Sciences, Inc. (GILD): Free Stock Analysis Report
Protagonist Therapeutics, Inc. (PTGX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).