

Root, Inc. ROOT is showing better insurance economics even as its premium growth cools. First-half underwriting metrics improved, and lower reinsurance cessions allowed the company to retain more premium.
The trade-off is that Root is prioritizing target returns over volume as direct auto competition intensifies. Rising claims severity and planned second-half spending make the next phase of profitable growth more demanding.
ROOT's Underwriting Gains Support the Bull Case
Root's first-half 2026 net combined ratio improved to 91.7% from 95.4% a year earlier, while the net loss and loss adjustment expense ratio improved to 64.1% from 65.1%. Adjusted EBITDA rose to $100.6 million from $69.5 million.
Reinsurance is adding another benefit. Root ceded about 1.5% of gross premiums earned in the first half, down from 5.8% a year earlier. Management also plans to launch its next predictive pricing model in the fourth quarter of 2026, with a larger impact expected in 2027.
Slower Premium Growth Tests ROOT's Expansion Story
Gross written premium declined 3.7% in the first half of 2026 as Root reduced customer acquisition that failed to meet its return thresholds. Direct performance marketing spending fell $35.4 million year over year during the period.
Policies in force still increased 6.2% year over year to 483,921 at second-quarter end, but management expects the 2026 year-end count to be relatively flat if current competition persists. Premiums per policy also fell to $1,479 from $1,616 a year earlier, while the first-half gross accident-period loss ratio rose to 59.7% from 56%.
ROOT's Valuation Sits Near Its Five-Year Median
ROOT trades at a trailing 12-month price-to-tangible-book ratio of 2.58, matching its five-year median. That leaves less room for a valuation-based argument that the shares are unusually depressed relative to their own history.
The stock has fallen 51.6% in the past year, yet its current multiple remains at that historical midpoint. Investors therefore have more reason to focus on earnings execution, underwriting durability and the pace of renewed premium growth than on simple multiple normalization.
New Channels Could Broaden ROOT's Growth Base
Partnerships and independent agents represented about 51% of second-quarter new writings, up from about 44% a year earlier. Root was active in 37 auto insurance markets as of August 2026, covering more than 80% of the U.S. population, and is targeting a near-national footprint by the end of 2027.
ROOT's Strong Style Scores Meet a Hold Signal
ROOT's setup remains balanced. Better underwriting, broader distribution and favorable estimate revisions support the case, while slower premium growth, higher loss costs and normalized expenses limit the near-term argument for aggressive expansion.
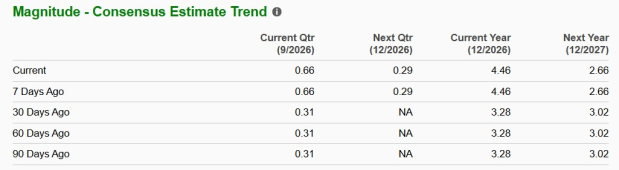
The Zacks Consensus Estimate for 2026 has risen 36% in the last 30 days.
Image Source: Zacks Investment Research
ROOT currently carries a Zacks Rank #3 (Hold). ROOT also has a Value Score of A, Growth Score of A, Momentum Score of A and VGM Score of A. Those grades indicate favorable characteristics across the four style measures, but Style Scores are designed to complement the Zacks Rank and are most compelling alongside a #1 (Strong Buy) or #2 (Buy) rank.
Stocks to Consider
Mercury General MCY, Heritage Insurance HRTG and American Integrity Insurance Group, Inc. AII are some top-ranked stocks from the Zacks Property and Casualty Insurance industry. All three stocks currently sport a Zacks Rank #1. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for 2026 and 2027 earnings of Mercury General, Heritage Insurance and American Integrity witnessed northbound movement in the last 30 days. In terms of share price movement, Mercury General, Heritage Insurance and American Integrity lost 6.8%, 1.1% and 1.6%, respectively, in the past month.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Root, Inc. (ROOT): Free Stock Analysis Report
Mercury General Corporation (MCY): Free Stock Analysis Report
Heritage Insurance Holdings, Inc. (HRTG): Free Stock Analysis Report
American Integrity Insurance Group, Inc. (AII): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).