

Novo NVO is expanding its external innovation strategy with the latest license agreement with Hengrui Pharma for HRS-1596, a phase I-ready GLP-1/GIP dual receptor agonist with potential for once-weekly oral dosing. Under the deal, Novo gains exclusive rights to develop, manufacture and commercialize the candidate globally outside mainland China, Hong Kong, Macao and Taiwan. The agreement has a total potential value of up to $2.6 billion, including a $300 million upfront payment, plus potential sales royalties. Hengrui has received approval in China to begin phase I studies of HRS-1596 for weight management and type II diabetes (T2D). The transaction is expected to close in the fourth quarter, subject to the fulfilment of certain regulatory and customary conditions.
The Hengrui agreement builds on another important 2026 partnership. In February, Novo partnered with Vivtex to develop next-generation oral biologic medicines for obesity, diabetes and associated comorbidities. Under the agreement, Vivtex licensed selected oral drug-delivery technologies to Novo, while Novo will lead global development and commercialization. Vivtex is eligible to receive up to $2.1 billion in upfront consideration, research funding and milestone payments, along with royalties on future product sales. The technology is designed to improve the oral delivery and bioavailability of peptide and protein therapies.
Last year, Novo entered into an exclusive global collaboration and license agreement with Septerna to discover, develop and commercialize multiple oral small-molecule medicines targeting GPCRs, including GLP-1, GIP and glucagon receptors for obesity, T2D and other cardiometabolic diseases. Septerna received a $195 million upfront payment, while the overall agreement provides for approximately $2.2 billion across upfront, research, development and commercial milestone payments, plus tiered royalties.
Taken together, these agreements show that Novo is using licensing and partnerships to supplement its internal pipeline with new molecules, mechanisms and delivery technologies. This is particularly relevant because semaglutide-based products, comprising Ozempic and Rybelsus for T2D and Wegovy for obesity, generated roughly 75.5% of Novo’s adjusted first-half 2026 sales, leaving it heavily exposed to shifts in competition and exclusivity.
Novo Faces Intensifying Competition From Lilly
Pipeline diversification is becoming more important as Novo’s arch rival, Eli Lilly LLY, continues to expand across diabetes and obesity. Its tirzepatide-based GLP-1 medicines, Mounjaro (for T2D), generated $18.6 billion in first-half 2026 sales, up 106%, while Zepbound (for obesity) sales rose 60% to $9.1 billion. By comparison, Novo’s first-half Ozempic sales declined 2% at constant exchange rates, while Wegovy product sales increased 7%. Novo’s latest outlook calls for both adjusted sales and adjusted operating profit to decline 0% to 6% at constant exchange rates in 2026.
Eli Lilly is also challenging Novo in oral obesity treatment with Foundayo (orforglipron), which launched in the United States in April and can be taken without food or water restrictions. Foundayo is currently under regulatory review in more than 40 additional countries, with further approvals expected later this year. Lilly expects to launch Foundayo in most international markets by 2027. For the T2D indication, Lilly has filed regulatory applications in several countries, including the United States. In addition to obesity and diabetes, Lilly is evaluating Foundayo across separate phase III studies for other diabetes and obesity-related diseases, which could broaden its reach in cardiometabolic care.
Against this backdrop, Novo’s licensing strategy could play an important role in broadening its long-term growth base. HRS-1596 adds a potential once-weekly oral incretin, Vivtex brings oral drug-delivery technology and Septerna expands access to oral small-molecule approaches. While these programs remain in early-stage, their development could give Novo additional cardiometabolic growth drivers and reduce its reliance on Ozempic and Wegovy over time.
Smaller Biotechs Intensify NVO’s GLP-1 Competitive Pressure
While Novo and Eli Lilly currently dominate this space, smaller biotechs like Structure Therapeutics GPCR and Viking Therapeutics VKTX are also advancing GLP-1–based therapies for treating obesity.
Viking Therapeutics’ dual GIPR/GLP-1 RA, VK2735, is being developed in both oral and subcutaneous formulations for the treatment of obesity. Viking recently reported positive top-line results from a subcutaneous maintenance study, with patients maintaining up to 97% of their prior weight loss on every-other-week dosing and up to 90% on monthly dosing over the 12-week maintenance period. Viking plans to advance oral VK2735 into phase III development for obesity in the fourth quarter of 2026.
Structure Therapeutics’ phase II ACCESS program on its orally administered small molecule GLP-1 RA, aleniglipron, demonstrated significant weight loss across all doses. Based on such encouraging results, Structure Therapeutics has initiated dosing patients in its late-stage ACCOMPLISH program to evaluate aleniglipron for chronic weight management.
NVO’s Stock Price, Valuation & Estimates
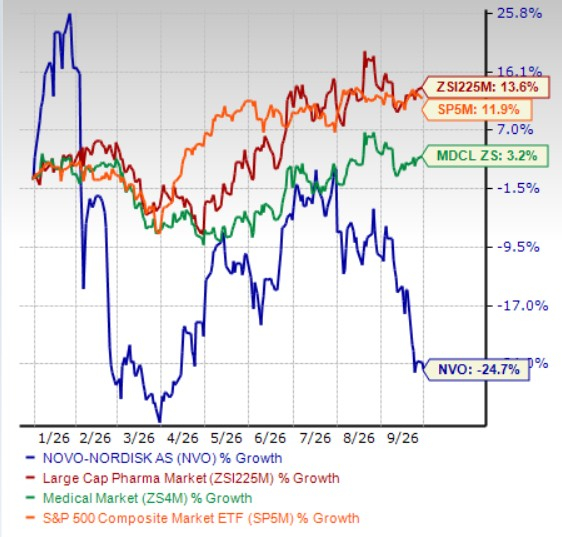
Year to date, Novo shares have lost 24.7% against the industry’s 13.6% growth. The company has also underperformed the sector and the S&P 500 during the same time frame, as seen in the chart below.
NVO Stock Underperforms the Industry, Sector & the S&P 500
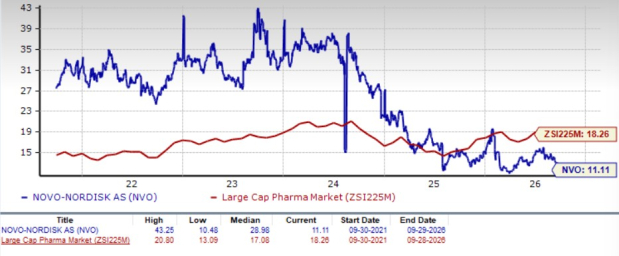
Novo is trading at a discount to the industry, as seen in the chart below. Going by the price/earnings ratio, the company’s shares currently trade at 11.11 forward earnings, which is lower than 18.26 for the industry. The stock is trading below its five-year mean of 28.98.
NVO Stock Valuation
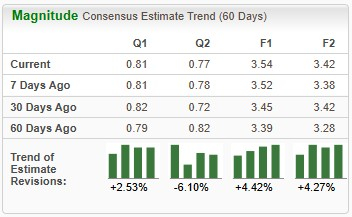
Earnings estimates for 2026 have increased from $3.39 to $3.54 per share over the past 60 days. During the same time frame, Novo’s 2027 earnings estimates have increased from $3.28 to $3.42.
NVO Estimate Movement
Novo currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Novo Nordisk A/S (NVO): Free Stock Analysis Report
Eli Lilly and Company (LLY): Free Stock Analysis Report
Viking Therapeutics, Inc. (VKTX): Free Stock Analysis Report
Structure Therapeutics Inc. Sponsored ADR (GPCR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).