

Ondas, Inc. ONDS trades at a forward 12-month price-to-sales ratio of 4.65X, a discount compared with the Zacks Wireless National industry’s 8.67X and the Zacks Computer and Technology sector’s 6.24X.
Image Source: Zacks Investment Research
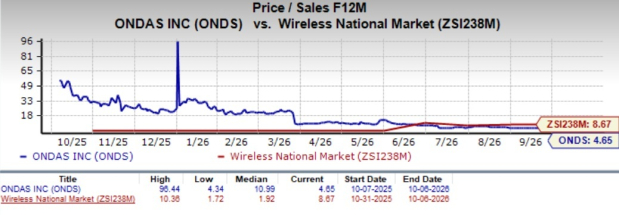
Moreover, shares of the company have lost 24% year to date against the industry’s growth of 150.3%.
The valuation discount against a weak share-price backdrop suggests that investors remain cautious despite Ondas’ rapid expansion across the autonomous systems space, including counter-UAS, precision strike, intelligence, surveillance and reconnaissance and autonomous ground systems.
At first glance, the pullback, coupled with the discounted sales multiple, could make the stock appear increasingly attractive. However, the investment case is not straightforward.
Ondas is pursuing an aggressive acquisition strategy while investing heavily in the infrastructure needed to support a much larger business. However, M&A brings significant execution risks.
Against this backdrop, let’s do a deep dive to assess investment prospects and make an informed decision.
Ondas’ Momentum Is in Sharp Contrast to Share Price Decline
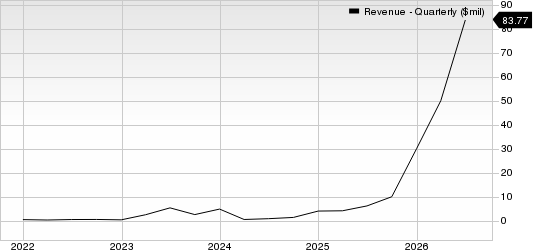
Ondas’ second-quarter 2026 revenues surged more than 13 times year over year to $83.8 million and increased 67% sequentially. The top-line growth reflected acquisitions and solid execution across Ondas' core business. Pro forma organic revenues increased 85% year over year.
Ondas Holdings Inc. Revenue (Quarterly)
Ondas Holdings Inc. revenue-quarterly | Ondas Holdings Inc. Quote
Visibility is improving alongside revenues. Reported backlog reached approximately $613 million as of June 30, with pro forma backlog of $757 million including DZYNE and Cyberhawk acquisitions. Management is not only focusing on selling drones but on connecting a portfolio of technologies into integrated systems spanning detection, intelligence, command and control, electronic warfare and kinetic defeat.
Since reporting second-quarter results, Ondas has continued to broaden its autonomous-defense platform through acquisitions. In September, Ondas acquired three defense technology businesses (Insignito, Ottopia Defense and Caribou Labs) for $56 million, payable in cash or its common stock, with potential performance-based earn-outs of up to $32 million based upon achieving key performance milestones through 2028.
Before that, the company acquired GATE Technologies and Bron Technologies, adding electronic safe-and-arm (ESADs) devices and advanced electronic fuzing technologies. Ondas will pay $205 million, comprising $105 million in cash and $100 million in its stock, plus a working-capital adjustment. The transaction also includes up to $185 million of performance-based earn-outs through 2028. Ondas expects GATE to generate $65 million of full-year 2026 revenues, rising to $180 million in 2028, with more than $130 million in aggregate adjusted EBITDA through 2028.
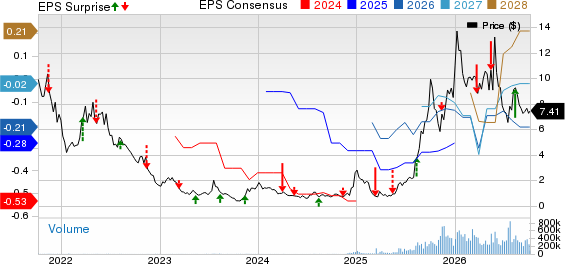
Ondas Holdings Inc. Price, Consensus and EPS Surprise
Ondas Holdings Inc. price-consensus-eps-surprise-chart | Ondas Holdings Inc. Quote
On Oct. 5, the company announced a $56 million order for ESADs, supporting a European loitering munition program. The order represents an important early commercial development following Ondas’ acquisition of GATE Technologies and Bron Technologies.
In August, it entered into a definitive agreement to acquire Aran Defense Ltd., the defense division of Aran Ltd., for approximately $33 million in cash or common stock. Aran Defense would expand Ondas’ Israeli engineering and manufacturing capacity, including roughly 4,400 square meters of facilities.
Counter-UAS Portfolio Continues to Expand
Counter-UAS is an important tailwind for the company. Ondas recently introduced Dronebuster REACH, a long-range variant of its Dronebuster family of non-kinetic counter-drone systems. The product launch could strengthen Ondas’ position in the rapidly developing counter-drone market by addressing a key operational gap – defeating drones before they enter the effective range of handheld systems.
The first Dronebuster REACH system is already under contract for delivery to the Office of Naval Research following customer acceptance testing. The system will support C-UAS research, evaluation and testing activities, providing an early validation point for Ondas’ new product.
Ondas is combining DZYNE's Sawtooth technology with Sentrycs' Cyber-over-RF capabilities for counter-UAS applications. On the last earnings call, Ondas highlighted that IonStrike (through DZYNE) was positioned to begin receiving commercial-volume orders and initial deliveries during the second half of 2026.
Sentrycs’ second-quarter pro forma revenues increased approximately 298% year over year, highlighting the commercial momentum in this part of the portfolio.
Precision Strike represents another important near-term revenue catalyst. Mistral is preparing to deliver against more than $240 million of aggregated orders under the U.S. Army's $982 million Lethal Unmanned Systems IDIQ program. On the last earnings call, management noted that the commercial deliveries are expected to ramp in the second half of 2026 and continue into 2027.
Execution Remains the Key Question
The scale of Ondas’ opportunity is increasing, but so is the complexity of executing its strategy.
Ondas has added World View, Mistral, Omnisys, DZYNE and Cyberhawk during 2026 and expanded further through the acquisitions of GATE Technologies, Bron Technologies, Insignito, Ottopia Defense and Caribou Labs.
The company deployed about $325 million of cash in the third quarter to complete DZYNE and Cyberhawk acquisitions before announcing and completing additional acquisitions subsequently. It is also expanding production, sales and marketing reach and field-support infrastructure.
Multiple acquisitions in such a short period can create integration overload and execution risks, since achieving targets depends on timely integration and conversion of backlog into revenues.
Profitability Remains Distant for ONDS
For all the excitement surrounding revenue growth, second-half ramp and profitability remain the key tests for ONDS.
The company raised its full-year revenue outlook to $525-$550 million from the previous target of at least $525 million, representing more than 10 times the reported figure for 2025. At the midpoint, the outlook implies more than 30% year-over-year organic growth on a pro forma basis. The pace of order conversion and production scaling will determine whether ONDS can deliver the steep second-half ramp embedded in its outlook
Coming to profitability, second-quarter operating expenses were $199 million, substantially exceeding the quarterly revenues of $83.8 million.
While more than half of expenses consisted of noncash or acquisition-related items, adjusted cash operating expenses still totaled approximately $93 million. The company incurred approximately $4.4 million of acquisition-related transaction costs.
Adjusted EBITDA remained a loss of approximately $51 million. The company expects the second quarter to represent the peak adjusted EBITDA loss, but actual profitability still depends on anticipated second-half revenue ramp materializing. At the last earnings call, management cautioned about some gross-margin pressure during the second half of 2026 because of product mix and excess capacity associated with newly acquired businesses.
However, the company expects adjusted EBITDA losses to narrow beginning in the third quarter and has pulled forward its profitability timeline. Management now targets adjusted EBITDA profitability for the operating platform, including OAS and Ondas Sentinel, by the fourth quarter of 2026 and company-wide adjusted EBITDA profitability by the fourth quarter of 2027.
Image Source: Zacks Investment Research
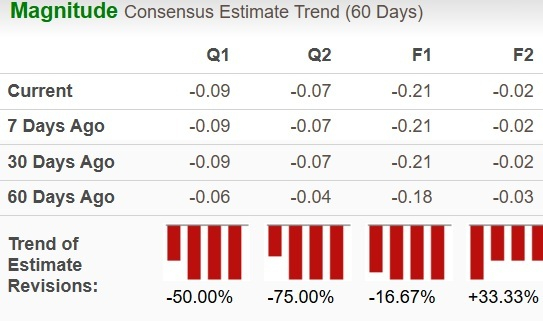
That makes the next several quarters particularly important. Strong revenue growth without corresponding improvement in operating leverage would weaken the core thesis.
Given these factors, analysts have downgraded their earnings estimates for ONDS’ current year over the past 60 days.
Competition in the Drone Space
Ondas operates in a highly competitive autonomous defense and unmanned systems market, competing with established and emerging players such as Kratos Defense & Security Solutions KTOS, Red Cat Holdings RCAT and AeroVironment AVAV.
Intense competition could pressure market share, making product differentiation, execution and rapid commercialization critical to sustaining growth.
Price Performance
Image Source: Zacks Investment Research
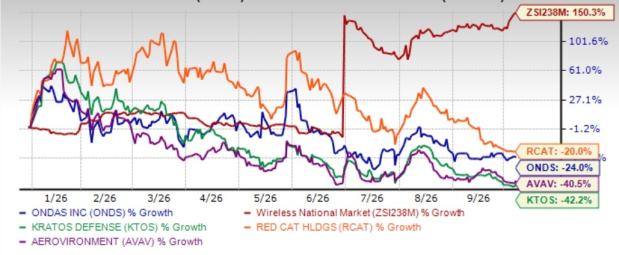
Year to date, RCAT, AVAV and KTOS have also registered declines of 20%, 40.5%, and 42.2%, respectively. This could be due to investor caution around heavy investment requirements and execution risks across the rapidly expanding drone and autonomous-defense market.
The forward 12-month price/sales multiple for KTOS, AVAV and RCAT stands at 3.91X, 3.1X and 4.09X, respectively.
ONDS Stock: How to Approach?
Although ONDS’ share price decline and valuation discount warrant attention, greater visibility into profitable growth would improve the risk-reward proposition.
With ONDS carrying a Zacks Rank #4 (Sell), investors need to exercise caution and wait for clearer evidence of improving profitability.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ondas Holdings Inc. (ONDS): Free Stock Analysis Report
AeroVironment, Inc. (AVAV): Free Stock Analysis Report
Kratos Defense & Security Solutions, Inc. (KTOS): Free Stock Analysis Report
Red Cat Holdings, Inc. (RCAT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).