

Marsh & McLennan Companies, Inc. MRSH is set to report third-quarter 2026 results on Oct. 15, before the opening bell. The Zacks Consensus Estimate for the to-be-reported quarter’s earnings is currently pegged at $1.96 per shareon revenues of $6.63 billion.
The third-quarter earnings estimate has witnessed two upward revisions and four downward movements over the past 60 days. The bottom-line projection still indicates a year-over-year increase of 6%. The Zacks Consensus Estimate for quarterly revenues implies year-over-year growth of 4.5%.
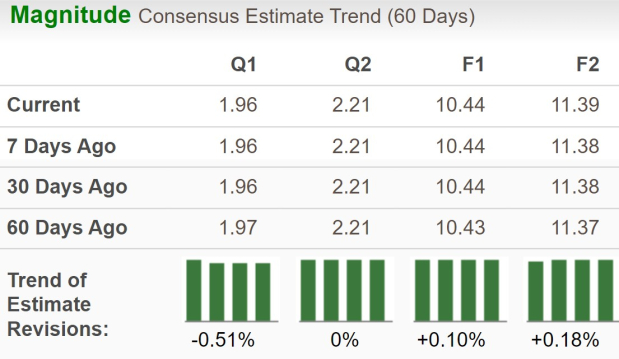
For the full year 2026, the Zacks Consensus Estimate for Marsh’s revenues is pegged at $28.52 billion, implying growth of 5.7% year over year. The consensus mark for the current year EPS is pegged at $10.44, signaling an increase of around 7.1% on a year-over-year basis.
Marsh’s earnings beat the consensus estimate in each of the last four quarters, with the average surprise being 4.1%.
Marsh Price and EPS Surprise
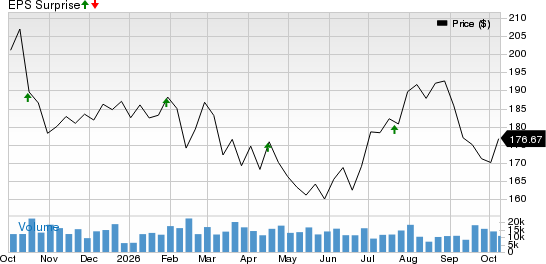
Marsh price-eps-surprise | Marsh Quote
Q3 Earnings Whispers for MRSH
Our proven model predicts a likely earnings beat for the company this time around as well. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That’s precisely the case here.
Marsh has an Earnings ESP of +0.42% and a Zacks Rank #3. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
What’s Shaping MRSH’s Q3 Results?
Both the Zacks Consensus Estimate and our model estimate for total Risk and Insurance Services revenues indicate 4.1% year-over-year growth. Revenues from the United States and Canada are expected to grow 4.5% from a year ago. Adjusted operating income from the Risk and Insurance Services segment is pegged at $1.02 billion, indicating 5.6% growth.
The consensus mark for total Mercer revenues suggests a 3.7% year-over-year jump, while our model suggests 3% growth. The consensus estimate for total Consulting revenues indicates 4.9% year-over-year growth, whereas our model signals a 4.1% increase. The Zacks Consensus Estimate for adjusted operating income from the segment of $565.7 million signals a 3.8% rise from a year ago.
The consensus estimate for consolidated organic revenue growth is pegged at 3.9% for the to-be-reported quarter. The above-mentioned factors are likely to have positioned MRSH for year-over-year growth and an earnings beat in the third quarter. However, rising costs will likely partly offset the positives.
Our model estimate for total operating expenses is pegged at $5.32 billion, which suggests a nearly 3% year-over-year increase due to higher compensation, benefits and other operating expenses. Also, the consensus mark for interest income signals a 27% decline from a year ago.
Other Stocks That Warrant a Look
Here are some other companies worth considering from the broader insurance space, as our model shows that these, too, have the right combination of elements to beat on earnings this time around:
MetLife, Inc. MET has an Earnings ESP of +2.04% and a Zacks Rank of 2. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for MetLife’s bottom line for the to-be-reported quarter is pegged at $2.64 per share, a 12.8% jump from a year ago. The consensus estimate for MET’s revenues is pegged at $20.10 billion, indicating 12.3% year-over-year growth.
Prudential Financial, Inc. PRU has an Earnings ESP of +0.69% and a Zacks Rank of 2.
The Zacks Consensus Estimate for Prudential Financial’s bottom line for the to-be-reported quarter is pegged at $3.44 per share, which witnessed five upward estimate revisions over the past 60 days against one downward movement. The consensus estimate for PRU’s revenues is pegged at $14.60 billion.
Willis Towers Watson Public Limited Company WTW has an Earnings ESP of +0.52% and a Zacks Rank #3.
The Zacks Consensus Estimate for Willis Towers’ bottom line for the to-be-reported quarter is pegged at $3.60 per share, which indicates 17.3% year-over-year growth. The consensus estimate for WTW’s revenues is pegged at $2.48 billion, an 8.3% increase from a year ago.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Marsh (MRSH): Free Stock Analysis Report
MetLife, Inc. (MET): Free Stock Analysis Report
Prudential Financial, Inc. (PRU): Free Stock Analysis Report
Willis Towers Watson Public Limited Company (WTW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).