

Johnson & Johnson's JNJ shares declined around 5.8% on Tuesday in response to its third-quarter 2026 results. While earnings beat estimates, J&J’s sales slightly fell short of expectations. Although the company increased its full-year outlook, weaker-than-expected performance in its MedTech business weighed on investor sentiment while Innovative Medicine continued to outperform.
Abiomed and International Markets Hurt MedTech Growth
The biggest concern was sluggish growth in the MedTech segment, where sales increased just 2.5% to $8.64 billion, compared with 7.7% growth in Innovative Medicine. Management acknowledged that MedTech’s performance fell below internal expectations, particularly in international markets and at Abiomed.
Abiomed sales declined 2.3% in the third quarter due to lower procedure volumes and more cautious physician use of Impella following a U.K. clinical trial that questioned its benefit in certain high-risk procedures. Changes in patient selection weighed on demand, creating uncertainty around the business’s recovery.
Internationally, expanded volume-based procurement in China, the impact of J&J’s surgery transformation program, and Middle East disruptions to tender timing and ordering patterns hurt sales in the Surgery segment. Competitive pressure in pulsed field ablation, particularly in Asia-Pacific, hurt electrophysiology growth.
Cancer Drugs Fall Short of Estimates in JNJ’s Innovative Medicine
In the Innovative Medicine segment, sales of key cancer drugs Darzalex, Erleada and Imbruvica fell short of expectations. Share gains and market growth for Darzalex and Erleada were partially offset by outside U.S. pricing headwinds for Darzalex and unfavorable patient mix for Erleada. The loss of exclusivity of blockbuster immunology drug Stelara reduced Innovative Medicine’s operational growth by approximately 690 basis points.
Acquisition Costs Weigh on JNJ’s Adjusted Earnings
Earnings performance also offered less reassurance than revenue growth. Total sales rose 5.9% to $25.4 billion, but adjusted earnings per share declined 7.5% to $2.59. The company said the Firefly Bio acquisition and Sail Biomedicines collaboration affected adjusted earnings. These investments may strengthen its pipeline over time, but their immediate costs reduced profitability.
J&J Maintains Growth Outlook Despite Q3 Headwinds
Despite these headwinds, J&J continued to expect accelerated growth in 2026. Strength in Innovative Medicine is expected to persist, while MedTech performance is projected to improve in the fourth quarter, supported by a stable procedure environment and new product launches. Growth is expected to strengthen further in 2027. J&J also expects Surgery to return to growth in the fourth quarter, driven by continued U.S. growth and an acceleration in EMEA.
J&J is confident about achieving its target of generating more than $100 billion in revenues in 2026, with $74.8 billion already generated in the first three quarters. It expects sales growth to be even better in 2027, with a “line of sight” to double-digit growth by the end of the decade.
J&J’s Key Competitors in the Medical Devices Market
J&J’s MedTech unit faces strong competition from several major players in the medical device industry, such as Medtronic MDT, Abbott, Stryker SYK and Boston Scientific BSX.
While Medtronic has a strong presence in cardiovascular, neuroscience and surgical technologies, Stryker is a major player in orthopedics and surgical equipment. Boston Scientific markets products for cardiovascular, endoscopy, urology and neuromodulation. Abbott is known for its medical devices across cardiovascular, diagnostics and diabetes care.
JNJ’s Price Performance, Valuation and Estimates
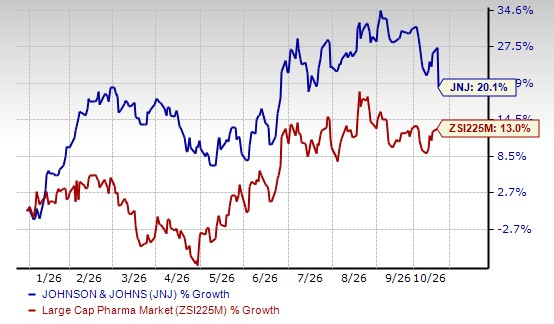
J&J’s shares have outperformed the industry so far this year. The stock has risen 20.1% this year compared with 13.0% appreciation of the industry.
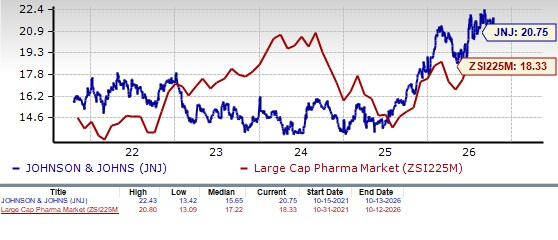
From a valuation standpoint, J&J is slightly expensive. Going by the price/earnings ratio, the company’s shares currently trade at 20.75 forward earnings, higher than 18.33 for the industry. The stock is also trading above its five-year mean of 15.65.
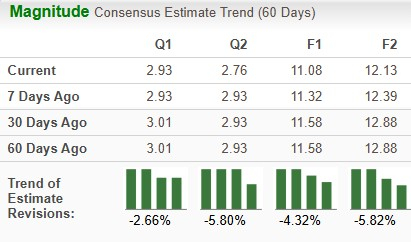
The Zacks Consensus Estimate for 2026 earnings has declined from $11.32 to $11.08 over the past seven days, while that for 2027 earnings has declined from $12.39 per share to $12.13 over the same time frame.
J&J has a Zacks Rank #4 (Sell) at present.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Johnson & Johnson (JNJ): Free Stock Analysis Report
Boston Scientific Corporation (BSX): Free Stock Analysis Report
Medtronic PLC (MDT): Free Stock Analysis Report
Stryker Corporation (SYK): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).