

Salesforce CRM and ServiceNow NOW are expanding their businesses with artificial intelligence (AI), automation and autonomous AI agents. Salesforce is using its strong customer relationship management (CRM) business to build a broader AI-powered enterprise platform, while ServiceNow is embedding AI into business workflows and IT service management.
Both companies have attractive long-term growth opportunities as businesses invest in AI. However, differences in revenue growth, AI adoption, earnings estimates and stock valuations make Salesforce the more appealing choice at present.
The Case for Salesforce Stock
Salesforce has long been a leader in CRM software, but it is now looking beyond traditional customer management to drive its next growth phase. The company is building an integrated platform that combines customer data, collaboration tools, enterprise applications and AI-powered automation.
Its acquisitions support this strategy. Slack has strengthened its collaboration capabilities, while Informatica has expanded its data management offerings. Acquisitions such as Doti AI and Spindle AI further support Salesforce's AI ambitions.
The biggest opportunity lies in converting its large customer base into a growing market for AI products. Early results are encouraging. In the second quarter of fiscal 2027, Agentforce annual recurring revenues (ARR) exceeded $1.5 billion, rising more than 240% year over year. Combined AI and Data ARR, including Agentforce, Data 360 and Informatica Cloud, surged 210% to $3.9 billion.
These figures show that Salesforce's AI business is gaining traction. However, the company still needs to translate this momentum into faster overall revenue growth. Second-quarter fiscal 2027 revenues rose 11% to $11.3 billion. Although this is solid growth for a company of its size, the gap between AI growth and total revenue growth remains significant.
Non-GAAP earnings per share (EPS) jumped 102.7% to $5.90, but the increase was partly influenced by gains on strategic investments, including Salesforce's investment in Anthropic. Investors should not interpret the entire EPS increase as evidence of stronger underlying operations.
Salesforce, Inc. Price, Consensus and EPS Surprise
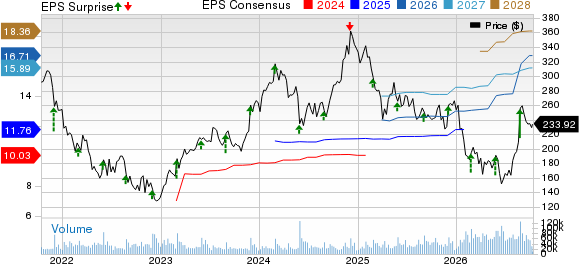
Salesforce, Inc. price-consensus-eps-surprise-chart | Salesforce, Inc. Quote
The Case for ServiceNow Stock
ServiceNow is also making progress in AI-powered automation. Its products help businesses automate IT support, manage incidents and streamline workflows across departments. In the second quarter of 2026, AI annual contract value (ACV) exceeded $1 billion, surpassing management's expectations. AI net new ACV growth also accelerated by more than 40% sequentially. ServiceNow is progressing toward its goal of generating 30% of ACV from AI by 2030.
Customer adoption is another positive sign. The number of customers using Agentic AI in production increased ninefold over the past nine months. Deal volume among first-time Agentic AI buyers also grew more than 45% year over year in the second quarter. This suggests that ServiceNow is attracting new AI customers while encouraging existing clients to expand their use of its products.
Its AI-native offerings are also creating opportunities to increase revenue per customer. Customers upgrading to these products are generating pricing increases of 20-30%, in line with the company's target. As businesses adopt AI for incident management, case handling and other complex workflows, ServiceNow could benefit from greater customer spending and additional cross-selling opportunities. The company’s second-quarter revenues soared 24% year over year to $3.99 billion, and earnings increased 11.1% to 90 cents per share.
ServiceNow, Inc. Price, Consensus and EPS Surprise
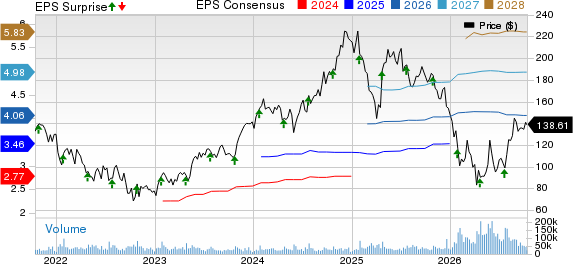
ServiceNow, Inc. price-consensus-eps-surprise-chart | ServiceNow, Inc. Quote
However, rapid AI adoption comes with costs. ServiceNow's non-GAAP total gross margin declined to 78% in the second quarter of 2026 from 81% a year earlier. Higher AI infrastructure expenses and greater reliance on cloud service providers could continue to pressure margins in the near term.
Acquisitions also introduce additional financial and execution risks. ServiceNow acquired Armis for approximately $7.6 billion and Veza for roughly $1.2 billion, expanding its security offerings. The company issued $4 billion in senior notes to help finance Armis, while commercial paper outstanding totaled $2.1 billion as of June 30, 2026. These transactions expand its growth opportunities but increase financing obligations, integration challenges and balance sheet complexity.
NOW vs. CRM: Earnings Estimate Trends
Analysts’ earnings estimates favor Salesforce. The Zacks Consensus Estimate for ServiceNow's 2026 and 2027 EPS stands at $4.06 and $4.98, respectively. Both estimates have remained unchanged over the past 60 days.
In comparison, the Zacks Consensus Estimate for Salesforce's fiscal 2027 and 2028 EPS is pegged at $16.71 and $15.88, respectively. These estimates have increased 18% and 2.8%, respectively, over the past 60 days.
Upward earnings revisions generally indicate improving analyst expectations. Salesforce's positive revision trend suggests that analysts see better earnings prospects, giving the company an advantage on this measure.
NOW vs. CRM: Stock Performance and Valuation
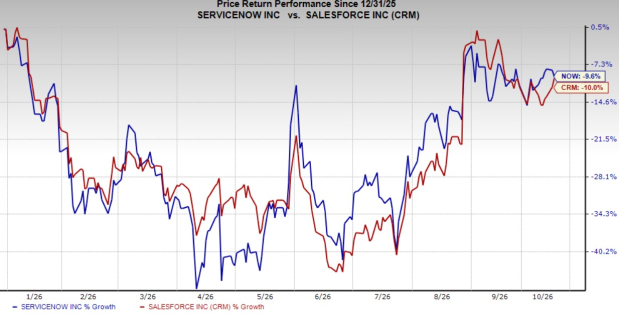
Both stocks have struggled in 2026. Year to date, ServiceNow shares have declined 9.6%, while Salesforce shares have fallen 10%. Salesforce's larger decline indicates weaker recent share price performance, although it also contributes to its more attractive valuation.
Image Source: Zacks Investment Research
Salesforce currently trades at a forward 12-month price-to-earnings (P/E) multiple of 14.76 compared with ServiceNow's 28.99. This means investors pay considerably less for each dollar of Salesforce's expected earnings.
Image Source: Zacks Investment Research
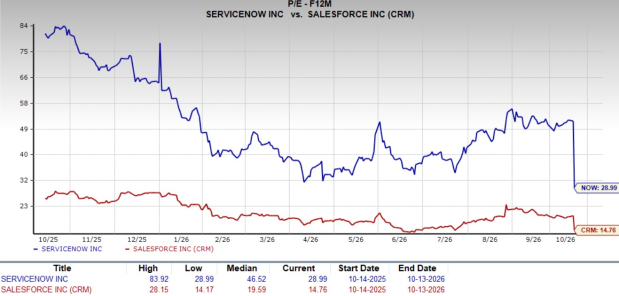
ServiceNow's premium valuation reflects its AI opportunity and strong demand for workflow automation. Nevertheless, its lower gross margin and acquisition-related risks make that premium harder to justify without sustained earnings growth. Salesforce's lower valuation offers a more favorable entry point, provided it can convert its expanding AI business into stronger company-wide growth.
Conclusion: Salesforce Has the Edge Over ServiceNow
Both Salesforce and ServiceNow are well positioned to benefit from rising enterprise AI adoption. ServiceNow has demonstrated strong demand for its Agentic AI products, and its workflow automation platform offers significant opportunities for customer expansion. However, higher infrastructure costs, declining gross margins and acquisition-related financial commitments remain important risks.
Salesforce, meanwhile, is seeing rapid growth in Agentforce and its broader AI and Data business. Its upward earnings estimate revisions also suggest improving analyst confidence. Most importantly, Salesforce trades at a forward P/E of 14.50X, well below ServiceNow's 29.36X, offering investors a more attractive valuation.
Salesforce has the edge over ServiceNow at present, based on its stronger earnings revision trend, expanding AI business and substantially lower valuation.
Currently, Salesforce and ServiceNow both carry a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Salesforce, Inc. (CRM): Free Stock Analysis Report
ServiceNow, Inc. (NOW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).