

Emerson Electric Co. EMR is well-poised for growth in the near term, courtesy of strength across its segments and accretive acquisitions. The company's efforts to reward its shareholders handsomely add to its appeal.
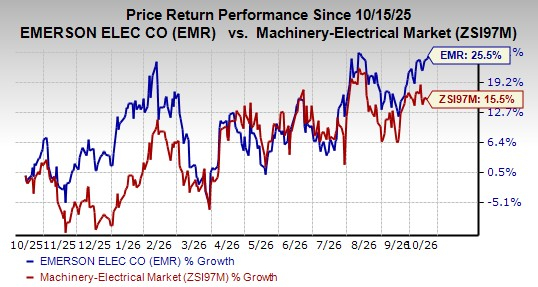
EMR currently carries a Zacks Rank #2 (Buy). In the past year, the company has gained 25.5% against the industry’s 15.5% decline.
Image Source: Zacks Investment Research
Let’s delve into the factors that make this company a smart investment choice at the moment.
Market Demand: EMR is experiencing healthy demand across most of its end markets. The company’s underlying sales increased 6% year over year in the third quarter of fiscal 2026, while underlying orders rose 7%. Emerson anticipates overall underlying sales to grow about 3.5% year over year in fiscal 2026, driven by strength in the power, LNG, life sciences, semiconductor and aerospace & defense end markets. Continued customer investments in automation, productivity, reliability and resiliency should also support steady progress.
Business Strength: The company is benefiting from the performance of the Intelligent Devices and Software and Systems groups. Within the Intelligent Devices group, strength in the Final Control segment, driven by momentum in power, LNG and midstream gas end markets, is aiding EMR. Within the Software & Systems group, strength in the power end market is supporting the Control Systems & Software segment.
Strength in the semiconductor and aerospace & defense end markets is aiding the Test & Measurement segment. A rise in demand for electrical products and growth in industrial activity in North America are boosting performance in Emerson’s Safety & Productivity segment. Given the healthy demand across its end markets, Emerson expects net sales to increase approximately 5% year over year in fiscal 2026.
Accretive Acquisitions: Emerson continues to use acquisitions to broaden its automation, software and measurement capabilities. In August 2026, EMR acquired Glue Inc. The acquisition will strengthen Emerson’s Test & Measurement segment by adding software-defined, data-centric validation capabilities to the NI portfolio.
In March 2025, the company acquired the remaining shares of Aspen Technology that it did not already own for approximately $7.2 billion. Emerson had acquired a 55% majority stake in AspenTech in 2022 and later increased its ownership to about 57%. AspenTech now operates as a wholly owned subsidiary and is reported within the Control Systems & Software segment. The transaction expands EMR’s industrial software offering and its capabilities in software-defined control and grid management. In the third quarter of fiscal 2026, the company’s software annual contract value increased 9% year over year to $1.68 billion, while annual contract value in AspenTech’s Digital Grid Management suite rose to 28%.
Shareholder Returns: Strong cash flows allow Emerson to effectively deploy capital to make acquisitions, repurchase shares and pay dividends. In the first nine months of fiscal 2026, its free cash flow increased 9% year over year to approximately $2.62 billion. The company’s free cash flow totaled $3.25 billion, up 12% in fiscal 2025. In the first nine months of fiscal 2026, it paid out dividends of $935 million and repurchased common stock worth $898 million. In November 2025, the company hiked its dividend by 5%. Emerson plans to repurchase shares worth approximately $1 billion and pay out dividends of about $1.2 billion in fiscal 2026.
Other Stocks to Consider
Some other top-ranked companies are discussed below.
Eaton Corporation plc ETN presently carries a Zacks Rank of 2. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The company delivered a trailing four-quarter average earnings surprise of 1.3%. In the past 60 days, the consensus estimate for ETN’s 2026 earnings has increased 0.6%.
Crane Company CR presently carries a Zacks Rank of 2. It has a trailing four-quarter average earnings surprise of 10.4%.
The Zacks Consensus Estimate for CR’s 2026 earnings has increased 0.4% in the past 60 days.
Constellium SE CSTM currently has a Zacks Rank of 2. CSTM delivered a trailing four-quarter average earnings surprise of 83.3%.
In the past 60 days, the Zacks Consensus Estimate for Constellium’s 2026 earnings has increased 2.4%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Emerson Electric Co. (EMR): Free Stock Analysis Report
Eaton Corporation, PLC (ETN): Free Stock Analysis Report
Crane Company (CR): Free Stock Analysis Report
Constellium SE (CSTM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).