

Texas Instruments Incorporated TXN is slated to release its third-quarter 2026 results on Oct. 21, after market close.
The company anticipates revenues between $5.65 billion and $6.15 billion for the third quarter. The Zacks Consensus Estimate is pegged at $5.91 billion, suggesting growth of 24.7% from the year-ago period's reported figure.
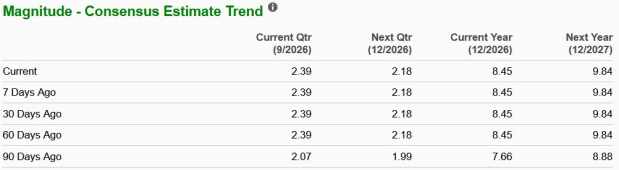
Texas Instruments expects earnings per share between $2.23 and $2.57. The Zacks Consensus Estimate for third-quarter earnings is pinned at $2.39 per share, implying a surge of 61.5% from the year-ago period's reported figure. The consensus mark for earnings has remained unchanged over the past 60 days.
Image Source: Zacks Investment Research
TXN’s earnings surpassed the Zacks Consensus Estimate in three of the trailing four quarters while missing once, with an average surprise of 8.3%.
Texas Instruments Incorporated Price and EPS Surprise
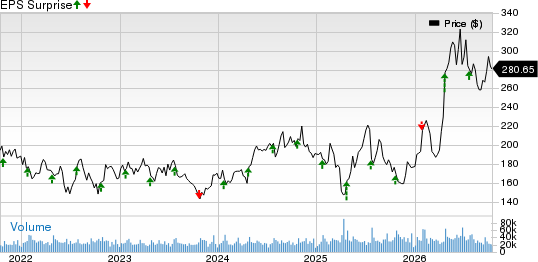
Texas Instruments Incorporated price-eps-surprise | Texas Instruments Incorporated Quote
What the Zacks Model Unveils for TXN
Our proven model does not conclusively predict an earnings beat for Texas Instruments this season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. However, that’s not the case here.
Earnings ESP: Texas Instruments has an Earnings ESP of 0.00% at present. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Zacks Rank: TXN currently carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Likely to Influence TXN’s Q3 Results
Texas Instruments’ third-quarter performance is likely to have benefited from strong demand for its analog and embedded chips. The company’s analog business remains the largest contributor, which is showing renewed strength supported by improving industrial demand, stronger data center investments and stable automotive sales.
Industrial revenues rose nearly 30% year over year in the second quarter of 2026, with growth spreading across regions and customer groups. At the same time, Texas Instruments is benefiting from rising demand for power-management chips used in artificial intelligence (AI)-driven data center infrastructure. In the second quarter, data center revenues doubled year over year and increased about 20% sequentially.
Analog revenues jumped 26% year over year to $4.37 billion in the second quarter, and the trend is likely to have continued in the third quarter. Our model estimates for the analog division’s third-quarter revenues are pegged at $4.79 billion, indicating 28.6% year-over-year growth.
Gradually improving end-market demand and easing customer inventory adjustments are likely to have aided growth in the embedded processing business during the third quarter. The segment is anticipated to have benefited from improving industrial demand and increasing semiconductor content across connected devices, vehicles and factory automation.
In the second quarter, embedded processing revenues rose 16.1% year over year to $788 million. The growth trend is likely to have continued in the third quarter. Our model estimates for the embedded processing division’s third-quarter revenues are pegged at $823 million, indicating 16.1% year-over-year growth.
However, Texas Instruments’ third-quarter performance is likely to have been affected by rising geopolitical tensions and the ongoing U.S.-China trade and tariff wars. TXN is a major player in China, accounting for more than 20% of its annual revenues in 2025.
TXN Stock Price Performance & Valuation
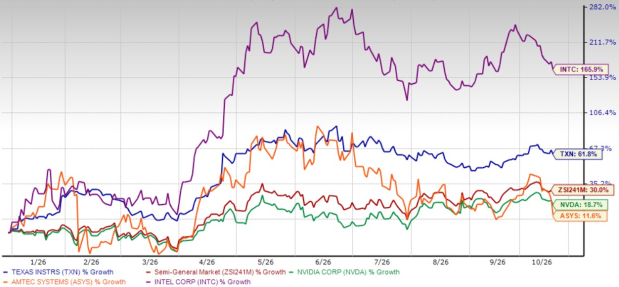
Texas Instruments shares have surged 61.8% year to date, outperforming the Zacks Semiconductor – General industry, which has risen 30%. Compared to other industry peers, the stock has outpaced NVIDIA Corporation NVDA and Amtech Systems, Inc. ASYS but has underperformed Intel Corporation INTC. Shares of NVIDIA, Amtech Systems and Intel have soared 18.7%, 11.6% and 165.9%, respectively.
Texas Instruments YTD Price Return Performance
Image Source: Zacks Investment Research
Let us look at the value Texas Instruments offers investors at current levels. Currently, TXN is trading at a premium, with a forward 12-month P/E of 29.38X compared with the industry’s 18.18X.
Texas Instruments Forward 12-Month P/E Ratio
Image Source: Zacks Investment Research
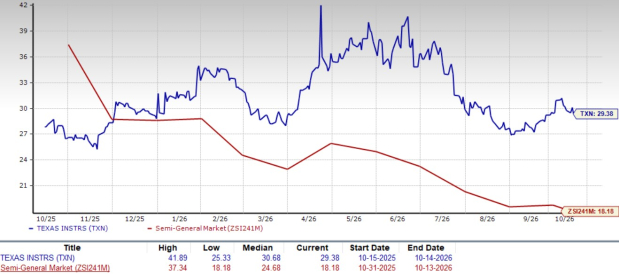
Compared with semiconductor giants, the stock trades at a higher multiple than NVIDIA and Amtech Systems, while at a lower multiple than Intel. At present, NVIDIA, Amtech Systems and Intel have forward 12-month P/E of 16.19X, 11.20X and 52.59X, respectively.
Investment Thesis on Texas Instruments Stock
Texas Instruments is not an AI accelerator company like NVIDIA or AMD, but it is becoming an important beneficiary of the AI boom. TXN makes analog and embedded chips that help manage power, process signals and control equipment used in data centers and industrial systems. As AI data centers become more powerful, they require more electricity and increasingly sophisticated power-management systems.
Instead of competing in the crowded AI processor market, the company is benefiting from the broader AI infrastructure buildout. This positions Texas Instruments to capture AI spending regardless of which GPU (graphics processing unit) maker ultimately dominates the data center market.
The numbers already reflect this trend. Texas Instruments' data center business reached an annual revenue run rate of approximately $1.2 billion in 2025, growing more than 50% year over year. During the second quarter of 2026, data center revenues doubled from the prior-year quarter and increased 20% sequentially.
Such strong growth suggests AI infrastructure could become an increasingly important revenue driver over the coming years. If AI data center investment remains strong, TXN's exposure could expand without requiring the company to compete directly in the highly competitive accelerator market.
Conclusion: Hold Texas Instruments Stock for Now
TXN is benefiting from rising AI infrastructure spending, rapidly expanding data center demand and a manufacturing strategy that should continue aiding its financial results. With AI infrastructure spending still in the early stages of a multi-year expansion cycle, Texas Instruments looks well-positioned to deliver steady growth for years to come. However, the stock’s premium valuation warrants a cautious approach.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Texas Instruments Incorporated (TXN): Free Stock Analysis Report
Intel Corporation (INTC): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Amtech Systems, Inc. (ASYS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).