

The Boston Beer Company, Inc. SAM is likely to register growth in its bottom line when it reports third-quarter 2026 results on Oct. 22, 2026, after market close. The company’s top line is expected to have declined year over year.
The Zacks Consensus Estimate for revenues is pegged at $523.4 million, implying a 2.6% drop from the prior-year quarter’s reported figure. The consensus mark for earnings has been stable in the past 30 days at $4.30 per share. This implies a rise of 1.2% from the year-ago quarter.
In the last reported quarter, the company delivered a negative earnings surprise of 23.5%. SAM has a trailing four-quarter negative earnings surprise of 3.4%, on average.
Factors Likely to Impact SAM’s Q3 Results
Boston Beer’s quarterly performance is likely to have been influenced by brand trends, consumer spending, cost pressures and the effectiveness of its growth initiatives. Weakness in Twisted Tea and Truly, along with declines in Samuel Adams and Dogfish Head, is likely to have weighed on volumes and market share. Competitive pressure from spirits-based ready-to-drink (RTD) beverages and softer consumer demand remain key concerns.
Persistent inflation, higher gasoline prices and reduced discretionary spending could further pressure alcoholic beverage demand. Meanwhile, rising aluminum, energy, freight and tariff costs may constrain profitability. Boston Beer expects 2026 tariff expenses of $20-$30 million.
Boston Beer has been witnessing weak depletion, with continued challenges in the hard seltzer category for a while. The hard seltzer segment remains under pressure, which has been weighing on Truly Hard Seltzer as it faces declining volumes and continued loss of shelf space. Intense competition across flavored malt beverages and tea-based drinks is further straining shelf space, as retailers streamline assortments and reduce the number of brands they carry. Such limitations are likely to hurt the company’s top-line results during the quarter under review.
On the flip side, Boston Beer’s focus on strategic pricing, product innovation and brand development to strengthen its market position and drive performance appears encouraging. The company is expanding its presence in the Beyond Beer category, which continues to outpace the traditional beer market. Sun Cruiser remains a major growth driver, benefiting from triple-digit depletion growth, expanding distribution and favorable product mix. Strong price realization and ongoing procurement savings are helping offset the inflationary and tariff pressures. These positives are likely to have contributed to the company’s bottom-line performance in the quarter under review.
The Boston Beer Company, Inc. Price and EPS Surprise
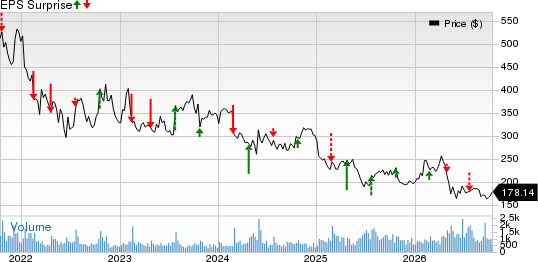
The Boston Beer Company, Inc. price-eps-surprise | The Boston Beer Company, Inc. Quote
What the Zacks Model Unveils for SAM Stock
Our proven model does not conclusively predict an earnings beat for Boston Beer this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chance of an earnings beat. But that is not the case here.
Boston Beer currently has an Earnings ESP of 0.00% and a Zacks Rank of 3. You can uncover the best stocks before they are reported with our Earnings ESP Filter.
Valuation Picture of SAM Stock
From a valuation perspective, Boston Beer stock is trading at a premium relative to historical and industry benchmarks. SAM has a forward 12-month price-to-earnings of 17.73X, above the Beverages - Alcohol industry’s average of 14.85X.
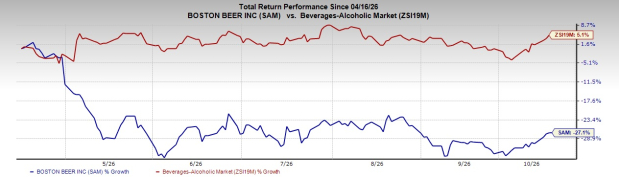
Boston Beer shares have shown a downward trend, losing 27.1% in the past six months against the industry’s growth of 5.1%.
Image Source: Zacks Investment Research
Stocks With the Favorable Combination
Here are some companies, which according to our model, have the right combination of elements to beat on earnings this reporting cycle.
Keurig Dr Pepper KDP currently has an Earnings ESP of +0.05% and a Zacks Rank of 2. The company is likely to register growth in the top and bottom lines when it reports third-quarter 2026 numbers. The consensus mark for revenues is pegged at $7.4 billion, which indicates a rise of 70.8% from the figure reported in the year-ago quarter. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Keurig Dr Pepper’s quarterly earnings per share of 64 cents implies a rise of 18.5% from the year-ago quarter. The consensus mark has been stable in the past 30 days. KDP has a trailing four-quarter earnings surprise of 2.7%, on average.
Celsius Holdings, Inc. CELH currently has an Earnings ESP of +4.00% and a Zacks Rank of 3. The company is likely to register an increase in the top line when it reports third-quarter 2026 numbers. The Zacks Consensus Estimate for CELH’s quarterly EPS is pegged at 34 cents, down 19.1% from the year-ago period. The consensus mark dipped a penny in the past 30 days.
The consensus estimate for Celsius’ quarterly revenues is pegged at $806.2 million, which implies an increase of 11.2% from the prior-year quarter. CELH has a trailing four-quarter negative earnings surprise of 28.5%, on average.
Anheuser-Busch InBev BUD currently has an Earnings ESP of +1.01% and a Zacks Rank #3. The Zacks Consensus Estimate for third-quarter 2026 EPS is pegged at $1.14, which implies an increase of 15.2% from the year-ago quarter’s actual. The consensus mark for EPS has dipped a penny in the past 30 days.
The consensus mark for BUD’s quarterly revenues is pegged at $16.3 billion, which indicates growth of 7.3% from the figure reported in the prior-year quarter. BUD delivered a trailing four-quarter earnings surprise of 6.3%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Boston Beer Company, Inc. (SAM): Free Stock Analysis Report
Anheuser-Busch InBev SA/NV (BUD): Free Stock Analysis Report
Celsius Holdings Inc. (CELH): Free Stock Analysis Report
Keurig Dr Pepper, Inc (KDP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).