

ASML Holding N.V. ASML emphasized accelerating semiconductor equipment demand during its third-quarter 2026 earnings call, driven by sustained artificial intelligence (AI) investments and expanding customer capacity requirements.
Management indicated that demand could exceed planned equipment supply through 2028, prompting additional manufacturing expansion efforts. Executives also discussed improved pricing, stronger memory investments and growing adoption of advanced lithography technologies.
ASML's Quarterly Results Reflect Strong Demand
ASML reported third-quarter 2026 earnings of $14.89 per share, exceeding the Zacks Consensus Estimate of $12.47. Revenues totaled $13.42 billion, surpassing the Zacks Consensus Estimate of $13.18 billion.
ASML Holding N.V. Price, Consensus and EPS Surprise
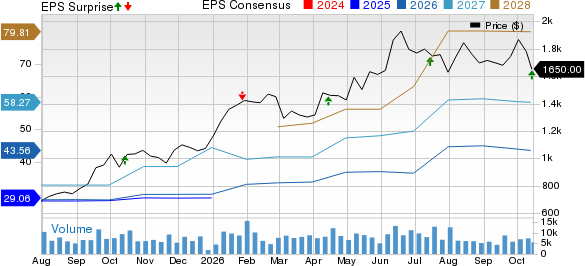
ASML Holding N.V. price-consensus-eps-surprise-chart | ASML Holding N.V. Quote
CFO Roger Dassen attributed the strong quarterly performance to increased system deliveries and productivity upgrades. Installed Base Management revenues reached €3.3 billion, exceeding the internal guidance by approximately €400 million.
Gross margin reached 57.5%, supported by higher-margin upgrade sales. The company also generated €11.4 billion in free cash flow, reflecting substantial customer down payments associated with strong ordering activity.
ASML Sees Equipment Demand Outpacing Supply
CEO Christophe Fouquet said customers continue extending equipment demand forecasts as AI infrastructure investments accelerate. Leading chipmakers increasingly anticipate supply shortages across advanced logic and memory manufacturing through at least 2028.
Management reaffirmed plans to expand Low NA EUV and immersion DUV manufacturing capacity by 30% in 2027. However, current expectations indicate that previously planned capacity increases for 2028 will be insufficient.
During questioning from Wells Fargo, Fouquet emphasized manufacturing efficiency improvements and shorter production cycles as expansion opportunities. He declined to provide revised shipment targets while the company evaluates additional capacity.
ASML's Revenue Outlook Reflects Continued Expansion
Dassen projected fourth-quarter revenues between €14.2 billion and €15.2 billion, with gross margin around 57%. Installed Base Management revenues are expected to reach approximately €3.7 billion.
For 2026, management expects revenues between €44 billion and €45 billion, representing approximately 36% annual growth. Gross margin is projected around 56%.
The outlook incorporates expected EUV revenue growth exceeding 45%, non-EUV system revenue growth around 20% and Installed Base Management growth around 50%. Management expects fourth-quarter manufacturing expansion costs to partially offset higher-volume margin benefits.
ASML Secures Pricing Increases for Critical Systems
Dassen confirmed that customer negotiations resulted in price increases for critical high-volume manufacturing products. The increases should begin benefiting revenues and gross margins during 2027, with fuller effects emerging in 2028.
Responding to JPMorgan's questions, Dassen acknowledged that additional manufacturing and supplier expansion expenditures would absorb some pricing benefits. Nevertheless, he expects a significant portion to support gross margins.
Management also clarified that pricing adjustments were negotiated within its value-based framework rather than as recurring annual increases. Executives emphasized maintaining pricing discipline even if industry conditions weaken.
ASML's Memory Business Gains Importance
Management expects memory system revenues to increase approximately 75% during 2026, reflecting expanding DRAM capacity and greater EUV adoption at advanced manufacturing nodes.
Logic revenues are expected to increase around 10%, although advanced logic growth should exceed 25%. Dassen indicated that logic would remain the larger business segment in 2027 despite memory's increasing contribution.
In discussions with Goldman Sachs, Fouquet emphasized robust demand across both markets. Management also highlighted customer interest in equipment deliveries extending into 2029 and 2030, although those longer-dated requests remain under evaluation.
ASML Advances Next-Generation Lithography Adoption
Fouquet highlighted growing commercial momentum for High NA EUV technology. Samsung and TSMC have outlined manufacturing adoption plans for 2028 and 2030, respectively.
ASML also plans to introduce its NXE:3800F system in early 2027, offering throughput of 260 wafers per hour compared with 230 for the preceding model.
Management expects next-generation immersion systems to achieve 330 wafers per hour. These productivity improvements are intended to expand customer manufacturing output while supporting equipment value and pricing.
ASML Maintains Focus on Execution
Management's overall commentary reflected confidence in sustained lithography demand alongside increasing pressure to expand manufacturing capacity.
Executives emphasized production efficiency, supplier coordination and customer commitments as priorities. Their immediate focus remains translating expanding equipment requirements into deliveries while managing ramp-up costs.
What ASML's Zacks Rank and Style Scores Indicate
ASML currently carries a Zacks Rank #4 (Sell), indicating an unfavorable earnings estimate revision trend. Its Growth Score of A reflects strong growth characteristics, while its Value Score of F signals less attractive valuation characteristics.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The stock's Momentum Score of C and VGM Score of C indicate mixed overall style characteristics. Despite its favorable Growth Score, the Zacks Rank warrants caution under the combined ranking framework. The rank may change as analysts revise earnings estimates following the latest results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
ASML Holding N.V. (ASML): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).