

Honeywell Technologies HON is scheduled to release third-quarter 2026 results on Oct. 22, before market open.
The Zacks Consensus Estimate for HON’s third-quarter revenues is pegged at $5.01 billion, indicating a decline of 51.8% from the prior-year quarter’s figure. The consensus mark for earnings is pinned at $2.17 per share, which has decreased a penny in the past 30 days. The figure indicates a decline of 61.5% from the year-ago quarter's figure.
It is worth noting that on June 29, 2026, Honeywell Technologies became a standalone public company following the spin-off of the Aerospace Technologies business from Honeywell International. The spin-off is likely to have weighed on its year-over-year top and-bottom-line comparison.
The company delivered better-than-expected results in each of the trailing four quarters, the earnings surprise being 6.7% on average. In the last reported quarter, its bottom line beat the consensus estimate by 8.3%.
Let us see how things have shaped up for Honeywell Technologies this earnings season.
Factors Likely to Have Shaped HON’s Quarterly Performance
Honeywell Technologies’ Process Automation and Technology segment is expected to have put up a weak show in the quarter due to softness in the aftermarket business with lower refining catalyst shipments and project delays. Also, reduced customer demand in the Middle East due to ongoing geopolitical tensions is likely to have hurt the segment’s performance in the third quarter.
Honeywell Technologies’ Industrial Automation Solutions segment is expected to have witnessed a year-over-year decrease in revenues due to the divestment of its Personal Protective Equipment business. For the third quarter, the Zacks Consensus Estimate for the segment’s total sales is pegged at $1.19 billion, indicating a 47.6% decrease from the year-ago reported number.
Over time, HON’s performance has been adversely impacted by high costs and expenses. Higher direct and indirect material costs and investments in digital infrastructure and business restructuring activities are expected to have pushed up the company’s operating expenses, which are likely to have reflected in its margins.
Also, given HON's extensive geographic presence, its operations are subject to foreign exchange headwinds. A stronger U.S. dollar is likely to have hurt its overseas business.
However, healthy demand for its products and solutions, led by increasing building projects across the Americas, India and the Middle East, is expected to drive the Building Automation segment’s results. Increasing order rates and capex investments in data centers and health care projects are likely to have been a tailwind as well. For the third quarter, the Zacks Consensus Estimate for the segment’s total sales is pegged at $2.01 billion, indicating a 7% rise from the year-ago reported number.
Honeywell International Inc. Price and EPS Surprise
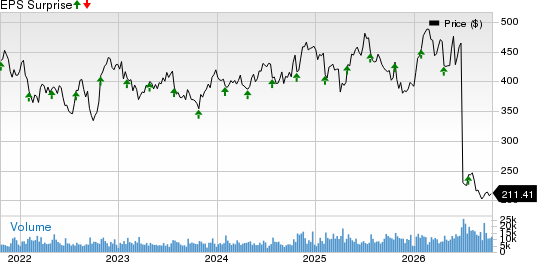
Honeywell International Inc. price-eps-surprise | Honeywell International Inc. Quote
Earnings Whispers for HON Stock
Our proven model does not conclusively predict an earnings beat for HON this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here, as elaborated below.
Earnings ESP: HON has an Earnings ESP of -0.44% as the Most Accurate Estimate is pegged at $2.16 per share, which is lower than the Zacks Consensus Estimate of $2.17. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
Zacks Rank: HON currently carries a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank stocks here.
Stocks With the Favorable Combination
Stanley Black & Decker, Inc. SWK has an Earnings ESP of +2.55% and a Zacks Rank of 2 at present. The company is slated to release third-quarter 2026 results on Nov. 4.
Stanley Black’s earnings surpassed the Zacks Consensus Estimate in each of the trailing four quarters, the average surprise being 23.3%.
Deere & Company DE has an Earnings ESP of +3.59% and a Zacks Rank of 3 at present. The company is slated to release third-quarter 2026 results on Nov. 25.
Deere & Company’s earnings surpassed the Zacks Consensus Estimate in three of the trailing four quarters and missed the mark in one, the average surprise being 11.1%.
Allegion plc ALLE has an Earnings ESP of +0.30% and a Zacks Rank of 3 at present. The company is slated to release third-quarter 2026 results on Oct. 22.
Allegion’s earnings surpassed the Zacks Consensus Estimate in two of the trailing four quarters while missing the mark in the other, the average surprise being 1%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Honeywell International Inc. (HON): Free Stock Analysis Report
Stanley Black & Decker, Inc. (SWK): Free Stock Analysis Report
Deere & Company (DE): Free Stock Analysis Report
Allegion PLC (ALLE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).