

Ecolab ECL is scheduled to release third-quarter 2026 results on Oct. 27, before the opening bell. In the last reported quarter, the company delivered earnings that surpassed the estimates by 0.48%. ECL’s earnings beat estimates in three of the trailing four quarters and met once, delivering an average surprise of 0.49%.
Q3 Estimates
Currently, the Zacks Consensus Estimate for revenues is pegged at $4.67 billion, indicating growth of 12.2% year over year. The consensus mark for earnings is pinned at $2.18 per share, indicating an improvement of 5.3%.
Factors to Note Before ECL Reports
Ecolab is expected to have sustained its growth momentum in the third quarter of 2026, supported by stronger pricing, resilient demand across core businesses and continued strength in its high-growth platforms. Global High-Tech, Life Sciences, Ecolab Digital and Pest Elimination are likely to have remained key growth drivers, benefiting from AI infrastructure investments, market share gains in bioprocessing, rising adoption of connected solutions and continued customer demand for productivity-enhancing technologies. However, elevated commodity costs, ongoing geopolitical disruptions and continued investments in growth businesses are likely to have influenced the company's margin and earnings performance.
Within the Global Industrial segment, Global High-Tech is expected to have remained a key contributor to growth, supported by strong demand for semiconductor manufacturing solutions and data center cooling technologies. In the second quarter, the business delivered 29% growth, reflecting the rapid expansion of AI infrastructure. The acquisition of CoolIT Systems, which closed in July, is expected to have further strengthened Ecolab's exposure to direct-to-chip liquid cooling and expanded its ability to provide integrated water, energy and cooling solutions.
Life Sciences is also likely to have remained a strong performer, following 15% growth in the second quarter, driven by market share gains in bioprocessing, pharmaceuticals and personal care, as well as improved purification performance. Investments in manufacturing capacity and innovation are expected to support further growth, although continued spending to expand the business could influence reported margins.
Meanwhile, Food & Beverage is likely to have benefited from the One Ecolab strategy and cross-selling opportunities, while Paper and Heavy Water could have continued their gradual recovery following signs of stabilization in the preceding quarter.
The Global Institutional & Specialty segment is expected to have maintained steady growth, supported by market share gains, value pricing and demand from restaurant, hotel, quick-service restaurant and specialty customers. In the second quarter, the segment delivered 4% organic growth despite softer U.S. restaurant traffic, highlighting the resilience of Ecolab's customer relationships and its ability to outperform underlying markets.
Continued cross-selling under the One Ecolab initiative and demand for solutions that improve productivity while reducing water and energy consumption are likely to have supported performance. Pest Elimination is also expected to have benefited from the expansion of its Pest Intelligence platform and connected-device offerings, while Ecolab Digital is likely to have continued to capitalize on growing adoption of software and subscription-based solutions.
Pricing realization and commodity inflation are expected to remain key factors influencing Ecolab's third-quarter performance. In the second quarter, pricing strengthened to 4%, and management expected pricing to reach 5% to 6% in the second half of 2026 as energy surcharges were fully realized. The company also anticipated high-single-digit commodity cost inflation for the remainder of the year.
Although pricing actions are expected to help offset higher input costs, the timing of recovery and the impact of acquisition-related expenses could influence reported earnings and margins. Management's second-half outlook called for organic sales growth of 6% to 7% and an adjusted operating income margin of 19%, while the full-year 2026 adjusted EPS outlook was raised to $8.05-$8.25, representing growth of 7% to 10% year over year. Investors will look for evidence that pricing is keeping pace with inflation, volumes remain resilient and productivity initiatives continue to support profitability.
Investors will also monitor the contribution from CoolIT and the pace of integration across Ecolab's Global High-Tech platform. Management expects the combined Global High-Tech business, including Ovivo and CoolIT, to grow more than 25% annually and reach $4 billion in sales by 2030, with an operating income margin of 25%. However, management indicated that it was too early to revise CoolIT's near-term growth expectations following the acquisition, despite its strong pre-acquisition sales momentum.
Commentary on demand across AI infrastructure, Life Sciences growth, the recovery in traditional industrial businesses and the trajectory of pricing and margins will be important as Ecolab works toward its long-term targets of 5% to 7% organic sales growth, a 20% operating income margin in 2027 and adjusted EPS growth of 12% to 15% beyond 2026.
Ecolab Inc. Price and EPS Surprise
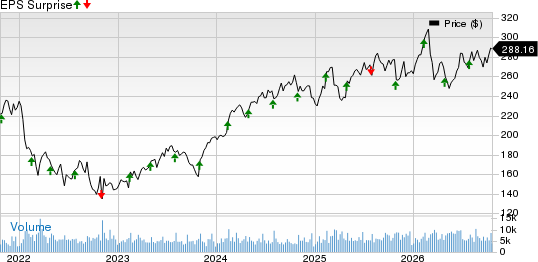
Ecolab Inc. price-eps-surprise | Ecolab Inc. Quote
Earnings Beat Unlikely
Our proven model does not predict an earnings beat for ECL this earnings season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat, which is not the case here.
Earnings ESP: Earnings ESP, which represents the difference between the Most Accurate Estimate and the Zacks Consensus Estimate, is +0.22%. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Zacks Rank: The company has a Zacks Rank #4 (Sell) at present.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Stocks Worth a Look
Here are some medical stocks worth considering, as these have the right combination of elements to post an earnings beat this time:
Phibro Animal Health PAHC has an Earnings ESP of +2.10% and a Zacks Rank #1. The company is expected to release first-quarter fiscal 2027 results soon.
PAHC’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 18.4%. The Zacks Consensus Estimate for the company’s first-quarter EPS indicates an increase of 8.2% from the year-ago quarter’s figure.
IDEXX Laboratories IDXX has an Earnings ESP of +0.59% and a Zacks Rank #2. The company is slated to release third-quarter 2026 results on Nov. 2.
IDXX’s earnings beat estimates in each of the trailing four quarters, the average surprise being 5.7%. The Zacks Consensus Estimate for the company’s third-quarter EPS implies an increase of 9.1% from the year-ago quarter’s figure.
Becton, Dickinson and Company BDX or BD has an Earnings ESP of +3.28% and a Zacks Rank #2. The company is due to release fourth-quarter fiscal 2026 results on Nov. 5.
BD’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 2.94%. The Zacks Consensus Estimate for the company’s fourth-quarter EPS calls for a rise of 2.5% from the year-ago quarter’s figure.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Ecolab Inc. (ECL): Free Stock Analysis Report
Becton, Dickinson and Company (BDX): Free Stock Analysis Report
IDEXX Laboratories, Inc. (IDXX): Free Stock Analysis Report
Phibro Animal Health Corporation (PAHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).