

Builders FirstSource, Inc. BLDR is slated to report third-quarter 2026 results on Oct. 29, before market open.
In the last reported quarter, the company’s adjusted earnings per share (EPS) missed the Zacks Consensus Estimate by 9.3%, and net sales lagged the same by 1.2%. On a year-over-year basis, both the top and bottom lines tumbled 8.8% and 50.8%, respectively.
BLDR’s earnings topped the consensus mark in one of the trailing four quarters and missed on one remaining occasion, the average surprise being negative 10.7%.
Trend in Estimate Revision of BLDR
The Zacks Consensus Estimate for Builders FirstSource’s third-quarter EPS has moved south to $1.13 from $1.16 in the past 30 days. The estimated figure indicates a 39.9% year-over-year decline from EPS of $1.88 reported in the year-ago quarter.
Builders FirstSource, Inc. Price, Consensus and EPS Surprise
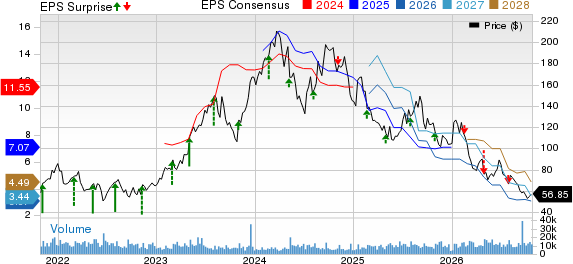
Builders FirstSource, Inc. price-consensus-eps-surprise-chart | Builders FirstSource, Inc. Quote
The consensus estimate for net sales is pegged at $3.79 billion, indicating a decline of 3.8% from $3.94 billion reported in the year-ago quarter.
Factors Likely to Shape BLDR’s Quarterly Results
Net Sales
Builders FirstSource’s third-quarter revenues are likely to have been pressured by persistent housing affordability challenges, elevated interest rates and subdued residential construction activity. Weak demand across single-family and multifamily markets, coupled with competitive pricing and commodity-price volatility, is expected to have weighed on the top line. However, the company’s focus on value-added products, integrated building solutions and strategic acquisitions is likely to have partly cushioned these headwinds in the to-be-reported quarter.
Value-added products, which accounted for approximately 46% of second-quarter 2026 sales, are likely to have remained pressured by weak single-family construction activity, lower manufactured product volumes and reduced structural content per home. Specialty Building Products & Services, representing about 27% of sales, may have benefited from the company’s diversified offerings and established customer relationships. However, lower product pricing and volumes are expected to have constrained growth. Lumber and lumber sheet goods, accounting for approximately 27% of sales, are likely to have benefited from product bundling and relative market-share resilience, although commodity-price volatility and competitive pricing may have limited revenue contributions.
Nonetheless, Builders FirstSource’s focus on value-added products and integrated building solutions is likely to have supported its competitive position. Its diversified product portfolio, installation services and bundled offerings are expected to have aided customer engagement amid the growing shift toward build-to-order homes.
Acquisitions are also likely to have supported third-quarter revenues. During the first half of 2026, the company acquired Premium Building Components and Precision Design & Trim, expanding its manufacturing and installation capabilities. With 42 acquisitions representing approximately $2.3 billion in annual sales since 2021, management expects recent acquisitions to contribute about 1% to full-year sales growth, partly offsetting weakness in the core business.
Margins
On the margin front, weaker sales volumes, unfavorable product pricing and reduced operating leverage are expected to have weighed on profitability. Elevated freight and fuel expenses are also likely to have pressured margins. Management anticipates approximately $100 million in full-year fuel-related cost pressures, with only partial recovery through surcharges and customer pricing. Although cost-saving initiatives are expected to have provided some relief, persistent demand weakness and higher operating expenses may have constrained margin recovery.
Management expects third-quarter net sales between $3.6 billion and $3.9 billion and adjusted EBITDA in the range of $275 million to $325 million, reflecting continued housing market challenges and a cautious near-term outlook.
What the Zacks Model Predicts for BLDR
Our proven model does not conclusively predict an earnings beat for Builders FirstSource this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. Unfortunately, this is not the case here, as you will see below.
BLDR’s Earnings ESP: BLDR has an Earnings ESP of -0.35%. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
Zacks Rank of BLDR: The company currently carries a Zacks Rank #4 (Sell).
Stocks With the Favorable Combination
Here are some companies in the Zacks Retail-Wholesale sector, which, per our model, have the right combination of elements to post an earnings beat in the respective quarters to be reported.
Sweetgreen, Inc. SG has an Earnings ESP of +4.26% and a Zacks Rank of 2 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
In the to-be-reported quarter, Sweetgreen’s earnings are expected to register a 3.7% year-over-year decline. SG’s earnings lagged estimates in each of the trailing four quarters, with the average miss being 43%.
Restaurant Brands International Inc. QSR currently has an Earnings ESP of +0.26% and a Zacks Rank of 3.
Restaurant Brands’ earnings for the to-be-reported quarter are expected to increase 4.9%. QSR reported better-than-expected earnings in each of the trailing four quarters, with the average surprise being 3.8%.
El Pollo Loco Holdings, Inc. LOCO currently has an Earnings ESP of +2.08% and a Zacks Rank of 3.
In the to-be-reported quarter, LOCO’s earnings are expected to decrease 11.1%. El Pollo Loco's earnings beat the Zacks Consensus Estimate in each of the trailing four quarters, the average surprise being 16.8%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Builders FirstSource, Inc. (BLDR): Free Stock Analysis Report
El Pollo Loco Holdings, Inc. (LOCO): Free Stock Analysis Report
Restaurant Brands International Inc. (QSR): Free Stock Analysis Report
Sweetgreen, Inc. (SG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).