

Xylem Inc. XYL is scheduled to release third-quarter 2026 results on Oct. 27, before market open.
The Zacks Consensus Estimate for XYL’s third-quarter revenues is pegged at $2.28 billion, indicating growth of 0.4% from the prior-year quarter’s number. The consensus mark for earnings is pinned at $1.47 per share, which has been stable in the past 60 days. The figure indicates an increase of 7.3% from the year-ago quarter’s figure.
The company’s earnings surpassed the Zacks Consensus Estimate thrice in the trailing four quarters and matched the mark in one, the average surprise being 5.6%.
Let’s see how things have shaped up for Xylem this earnings season.
Factors Likely to Have Shaped XYL’s Quarterly Performance
Strength in the transport application business, aided by increased infrastructure projects in the United States, is likely to have supported the Water Infrastructure segment’s performance. However, weakness in the water treatment business and lower demand in China are likely to have been a spoilsport. The Zacks Consensus Estimate for the Water Infrastructure segment’s revenues is pegged at $668 million, indicating 1.8% growth from the year-ago figure.
Electric metering project delays are expected to have affected the performance of the Measurement & Control Solutions (M&CS) segment in the third quarter. However, growing popularity for the company’s advanced metering solutions is likely to have offered some respite. The Zacks Consensus Estimate for the M&CS segment’s revenues is pinned at $486 million, reflecting a 6.9% decline from the year-ago quarter’s figure.
Strength in the Applied Water segment, supported by higher demand in commercial building and data-center markets, is likely to augment the segment’s results. The Zacks Consensus Estimate for the Applied Water segment’s revenues is pegged at $469 million, indicating 2.9% growth from the year-ago figure.
Recovery in Xylem’s dewatering applications business across utility and power end markets is likely to augment the Water Solutions and Services segment’s results. The Zacks Consensus Estimate for the Water Solutions and Services segment’s revenues is pegged at $671 million, indicating 5.8% growth year over year.
XYL’s acquisition of TriOS (in July 2026) added optical sensing and water-quality monitoring technology to the M&CS segment. This buyout is expected to bolster the company’s top-line results in the to-be-reported quarter.
However, XYL’s bottom line is likely to have reflected the impact of inflationary pressures in the third quarter. Also, increased spending on strategic investments is expected to have hurt its margins.
Xylem Inc. Price and EPS Surprise
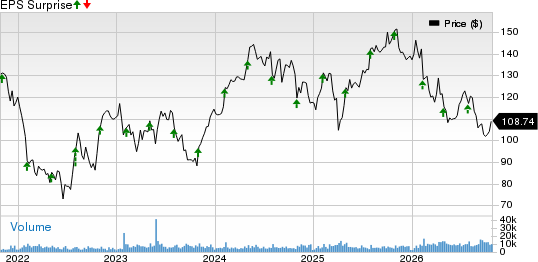
Xylem Inc. price-eps-surprise | Xylem Inc. Quote
Earnings Whisper
Our proven model does not conclusively predict an earnings beat for Xylem this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here, as elaborated below.
Earnings ESP: Xylem has an Earnings ESP of -1.27% as the Most Accurate Estimate is pegged at $1.45 per share, which is lower than the Zacks Consensus Estimate of $1.47. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
Zacks Rank: XYL presently carries a Zacks Rank #4 (Sell). You can see the complete list of today’s Zacks #1 Rank stocks here.
Stocks to Consider
Here are some companies, which according to our model, have the right combination of elements to beat on earnings in this reporting cycle.
Emerson Electric Co. EMR has an Earnings ESP of +0.40% and a Zacks Rank of 2 at present. The company is scheduled to release fourth-quarter fiscal 2026 results on Nov. 4.
Emerson’s earnings beat the Zacks Consensus Estimate twice and matched on the other two occasions of the preceding four quarters, the average surprise being 1.3%.
Constellium CSTM has an Earnings ESP of +14.50% and a Zacks Rank of 2 at present. The company is slated to release second-quarter 2026 results on Oct. 28.
Constellium’s earnings surpassed the Zacks Consensus Estimate in each of the trailing four quarters, the average surprise being 83.3%.
Kennametal Inc. KMT has an Earnings ESP of +1.50% and a Zacks Rank of 3 at present. The company is slated to release first-quarter fiscal 2027 results on Nov. 4.
Kennametal’s earnings surpassed the Zacks Consensus Estimate in each of the trailing four quarters, the average surprise being 29.3%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Xylem Inc. (XYL): Free Stock Analysis Report
Emerson Electric Co. (EMR): Free Stock Analysis Report
Kennametal Inc. (KMT): Free Stock Analysis Report
Constellium SE (CSTM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).