

West Pharmaceutical Services WST is scheduled to release third-quarter 2026 results on Oct. 29, before the opening bell. In the last reported quarter, the company delivered an earnings surprise of 13.94%. WST’s earnings beat estimates in each of the trailing four quarters, delivering an average surprise of 17.40%.
West Pharma is likely to have benefited from sustained demand for high-value product (HVP) components in the third quarter of 2026, although weakness in its West Vantage segment and the SmartDose divestiture are expected to have weighed on reported growth. Proprietary Products is expected to have remained the key growth driver, while West Vantage is likely to have faced near-term headwinds from the discontinuation of a continuous glucose monitoring (CGM) contract.
Q3 Estimates
Management expects third-quarter revenues to be in the range of $820-$835 million, implying 7-8.9% organic sales growth. Also, adjusted earnings per share (EPS) are expected to be in the range of $2.14-$2.24.
Currently, the Zacks Consensus Estimate for revenues is pegged at $825.9 million, indicating growth of 2.7% year over year. The consensus mark for earnings is pinned at $2.18 per share, indicating an improvement of 11.2%.
Our model estimates total revenues to be $825.1 million, implying a 7.6% organic improvement year over year. The adjusted EPS is estimated to be $2.14. While the Proprietary Products segment sales are anticipated to be $677.2 million (organic growth of 9.7%), West Vantage segmental sales are likely to be $147.9 million. Operating profit for the Proprietary Products segment is likely to improve 32.6%, while the metric for West Vantage is estimated to decline 16.5%.
Factors to Note
Proprietary Products: Biologics, GLP-1s and HVP Upgrades Drive Growth
The Proprietary Products segment is likely to have delivered low-double-digit growth, supported by continued momentum in HVP Components. Following 18.4% organic growth in the second quarter, demand is likely to have remained strong across biologics and biosimilars, GLP-1 therapies, and HVP upgrades associated with Annex 1 contamination-control requirements.
The company’s pipeline of nearly 800 Annex 1-related projects, up 50% year over year, should have supported further adoption of higher-value components and finishing services, including Envision inspection and pharmaceutical washing.
Both GLP-1 and non-GLP-1 HVP Components are expected to have remained important contributors. Expanding generic GLP-1 launches across international markets, increasing biologics adoption and new drug launches likely supported demand for premium components such as NovaPure and FluroTec.
Meanwhile, continued conversion from Standard Products to HVP components should have improved the segment’s revenue mix and margins. However, relatively flat Standard Products growth and the absence of SmartDose 3.5 revenues following its July 1 divestiture likely limited sales momentum. Growth in the remaining delivery-device portfolio, particularly SelfDose and Crystal Zenith, should have partly offset this impact.
West Vantage: Contract Exit Weighs on Performance
West Vantage’s revenues are expected to have declined in the third quarter, which management had identified as the segment’s anticipated revenue trough. The exit of the CGM contract likely created a significant headwind, while the recovery from the earlier cyber incident had shifted some revenues into the second half. The drug-handling business should have provided some support, although its more meaningful revenue contribution was expected in the fourth quarter as capacity ramped up at Dublin. Higher oil and commodity costs also posed margin risks, potentially requiring additional pricing actions.
West Pharmaceutical Services, Inc. Price and EPS Surprise
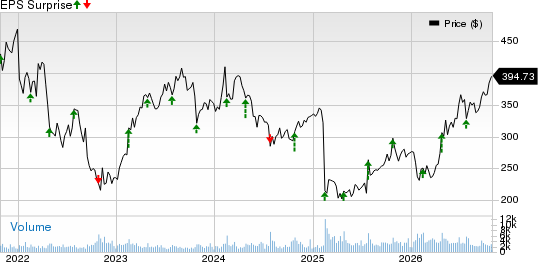
West Pharmaceutical Services, Inc. price-eps-surprise | West Pharmaceutical Services, Inc. Quote
What the Zacks Model Unveils
Our proven model does not conclusively predict an earnings beat for West Pharmaceutical this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. This is not the case here, as you will see below.
Earnings ESP: Earnings ESP, which represents the difference between the Most Accurate Estimate and the Zacks Consensus Estimate, is 0.00%. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Zacks Rank: The company carries a Zacks Rank #3 at present.
Stocks Worth a Look
Some stocks worth considering from the broader medical space are Glaukos GKOS, Edward Lifesciences EW and Globus Medical GMED, each carrying a Zacks Rank #2 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Glaukos reported second-quarter 2026 earnings per share of 14 cents, which beat the Zacks Consensus Estimate by 50.00%. Revenues of $186 million surpassed the Zacks Consensus Estimate by 24.1%.
Glaukos has an estimated earnings growth rate of 268.8% for 2027. GKOS’ earnings surpassed estimates in three of the trailing four quarters and missed once, the average surprise being 25.87%.
Edward Lifesciences reported second-quarter 2026 adjusted EPS of 78 cents, which beat the Zacks Consensus Estimate by 6.85%. Revenues of $1.74 billion surpassed the Zacks Consensus Estimate by 2.45%.
Edward Lifesciences has an estimated long-term earnings growth rate of 12.7%. EW’s earnings surpassed estimates in three of the trailing four quarters and missed once, the average surprise being 4.49%.
Globus Medical reported a second-quarter fiscal 2026 adjusted EPS of $1.34, which beat the Zacks Consensus Estimate by 19.6%. Revenues of $790 million missed the Zacks Consensus Estimate by 0.35%.
Globus Medical has an estimated long-term earnings growth rate of 12.4%. GMED’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 27.88%.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
West Pharmaceutical Services, Inc. (WST): Free Stock Analysis Report
Edwards Lifesciences Corporation (EW): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Glaukos Corporation (GKOS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).