

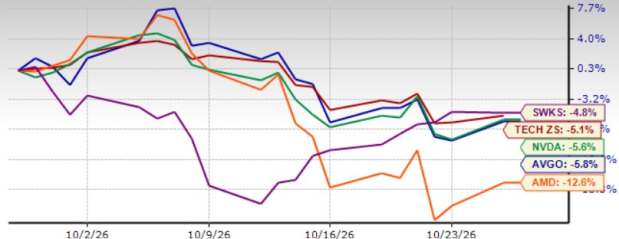
Broadcom AVGO shares have dropped 5.8% over the past month, underperforming the broader Zacks Computer and Technology sector’s drop of 5.1%. The company’s shares have suffered from margin pressure from the rising AI mix, supply constraints, a concentrated AI clientele and weak non-AI business.
AVGO shares have also underperformed NVIDIA NVDA, Advanced Micro Devices AMD and Skyworks SWKS over the same period. Shares of NVIDIA have dropped 5.6%, while AMD and Skyworks have declined 12.6% and 4.8%, respectively. So, what should investors do with the AVGO stock post the dip? Let us find out.
AVGO Stock’s Price Performance
Image Source: Zacks Investment Research
AVGO’s Prospects Suffer From Multiple Challenges
Broadcom’s rapidly expanding custom accelerator business is weighing on consolidated gross margins because XPUs carry an increasing proportion of expensive memory content. In the third quarter of 2026, non-GAAP gross margin declined 210 basis points sequentially to 75%. AVGO expects gross margin to decline further to approximately 73% in the fourth quarter compared with 78% in the year-ago period. Continued growth in lower-margin AI hardware relative to software could limit profitability expansion, although operating leverage should provide some offset.
AVGO faces limitations involving advanced semiconductor wafers, high-bandwidth memory, substrates and optical components. The company’s custom AI accelerator business currently depends on six major customers, exposing AVGO to changes in hyperscaler capital spending and product strategies. Competition from NVIDIA, AMD, MediaTek and customers’ internal semiconductor development teams could intensify over time. Any loss of design wins, customer insourcing or moderation in AI infrastructure investments could affect revenue growth and long-term earnings visibility.
Moreover, Broadcom's non-AI semiconductor business continues to experience relatively modest growth compared with its AI portfolio. In the third quarter of 2026, non-AI revenues increased only 5% year over year to $4.2 billion and remained flat sequentially. While broadband and server storage demand improved, weakness in wireless partially offset these gains. Continued softness across traditional semiconductor end markets could constrain revenue diversification. Broader concerns surrounding the sustainability of AI infrastructure spending have also weighed on semiconductor stocks, including Broadcom.
Can AVGO’s Strong AI Growth Boost Competitive Prowess?
Broadcom expects AI semiconductor revenues to reach approximately $58 billion in fiscal 2026, followed by $115 billion in fiscal 2027 and $230 billion in fiscal 2028. These projections reflect increasing deployments of custom accelerators and AI networking equipment by leading frontier-model developers.
Broadcom's long-term agreement with Google to develop and supply future generations of TPUs and networking products through 2031 strengthens revenue visibility. Anthropic is expected to deploy an additional 5 gigawatts of TPU capacity in 2027 and 10 incremental gigawatts in 2028. OpenAI is targeting more than 5 gigawatts of custom accelerator deployments in 2028, while Meta is expected to deploy approximately 3 gigawatts through 2028. These customer roadmaps offer substantial multiyear growth opportunities.
Broadcom’s expertise in advanced packaging, high-speed SerDes, chip-to-chip interconnects and high-bandwidth memory integration provides a competitive advantage. The company’s ability to co-develop accelerators optimized for customers’ specific AI workloads could support additional design wins. Increasing semiconductor complexity and the transition toward multi-die architectures may further strengthen demand for Broadcom’s engineering capabilities.
Growing enterprise requirements for data sovereignty, cybersecurity and cost-effective AI infrastructure could strengthen adoption of VMware Cloud Foundation and VMware Private AI Cloud. These platforms enable organizations to operate AI workloads alongside existing enterprise applications. Rising subscription adoption and recurring revenues could improve software revenue visibility and support Broadcom's long-term profitability.
However, Broadcom’s projected growth relies heavily on sustained capital expenditures by a limited number of hyperscalers and AI model developers. Higher HBM content, increasingly complex packaging and growing dependence on custom accelerators could continue pressuring gross margins. Although Broadcom expects operating leverage to offset some dilution, rising manufacturing costs or unfavorable semiconductor pricing could constrain long-term margin expansion. The company is facing stiff competition, which is a concern for investors.
AVGO’s FY26 Earnings Estimate Revision Shows Steady Trend
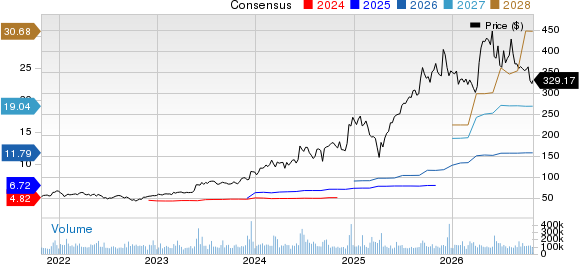
The Zacks Consensus Estimate for fiscal 2026 earnings is pegged at $11.79 per share, unchanged over the past 30 days, indicating 72.87% growth from the fiscal 2025 reported figure.
Broadcom Inc. Price and Consensus
Broadcom Inc. price-consensus-chart | Broadcom Inc. Quote
The Zacks Consensus Estimate for fourth-quarter fiscal 2026 earnings is pegged at $3.82 per share, unchanged over the past 30 days, indicating 95.9% growth from the figure reported in the year-ago quarter.
AVGO Stock: Buy, Sell or Hold?
Broadcom shares are trading at a premium, as suggested by the Value Score of F.
In terms of the forward 12-month price/sales (P/S), AVGO is trading at 9.04X, higher than the broader sector’s 5.49X. Broadcom is also trading at a premium compared with peers, NVIDIA and Skyworks, shares of which are currently trading at 9.96X and 2.76X, respectively.
AVGO Shares Are Overvalued
Image Source: Zacks Investment Research
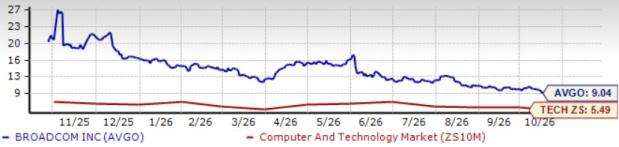
Broadcom’s expanding AI portfolio is expected to drive top-line growth. However, elevated AI expectations, a decline in gross margin expansion and customer concentration do not justify AVGO’s current valuation.
Broadcom currently has a Zacks Rank #3 (Hold), suggesting investors should wait for a more favorable point to start accumulating the stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Broadcom Inc. (AVGO): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Skyworks Solutions, Inc. (SWKS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).