

QuinStreet Inc. QNST is likely to beat earnings estimates when it reports first-quarter fiscal 2027 results after the market closes on Nov. 4.
The Zacks Consensus Estimate for first-quarter earnings has remained unchanged at 39 cents per share over the past 60 days, suggesting a 77.3% improvement from the year-ago quarter’s 22 cents.
QNST’s earnings beat the Zacks Consensus Estimate twice in the trailing four quarters, matched once and missed on one occasion, the average surprise being approximately 9.2%.
QuinStreet, Inc. Price and EPS Surprise
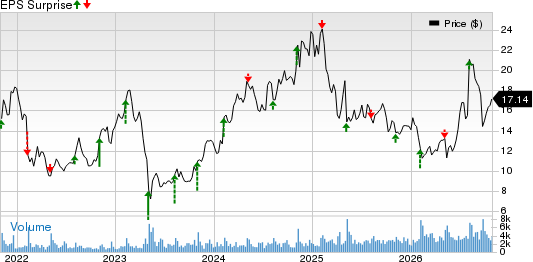
QuinStreet, Inc. price-eps-surprise | QuinStreet, Inc. Quote
For the first quarter, the company expects revenues of $370 million to $380 million. The Zacks Consensus Estimate for revenues is pegged at $374.7 million, indicating an increase of 31.1% from the year-ago quarter’s $285.9 million.
Let’s see how things are shaping up for the upcoming announcement.
Factors Likely to Influence QNST’s Q1 Results
QuinStreet's first-quarter performance is likely to have benefited from continued strength in Financial Services and Home Services businesses. Strong demand for auto insurance is likely to have contributed to Financial Services business growth.
In the fourth quarter of fiscal 2026, Financial Services revenues increased 24% year over year to $232.3 million, while auto insurance revenues grew 37%. Management attributed the auto insurance strength to higher demand from insurance carriers and continued consumer interest in shopping for better rates. The trend is likely to have continued in the to-be-reported quarter.
Home Services is anticipated to have remained another important growth driver in the first quarter. In the last reported quarter, Home Services’ revenues surged 88% year over year to $141.6 million, supported by strong client demand, expansion into new service categories and additional media channels.
The integration of HomeBuddy, which expanded QuinStreet's capacity to serve clients, had also progressed well. Continued benefits from this acquisition are likely to have helped the company increase revenues and improve profitability in the to-be-reported quarter.
QuinStreet is working to improve operating efficiency through artificial intelligence (AI) applications, greater use of owned and operated media and a shift toward higher-margin products. The company previously stated positive results from its AI initiatives. In the fourth quarter of fiscal 2026, adjusted EBITDA margin increased to 11.1% from 8.4% in the prior-year quarter. The company’s AI initiatives are likely to have supported productivity and margin expansion in the first quarter as well.
What the Zacks Model Unveils for QNST
Our proven model predicts an earnings beat for QuinStreet this season. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat, which is the case here.
Earnings ESP: QuinStreet has an Earnings ESP of +2.56% at present. You can uncover the best stocks to buy or sell before they’re reported with our Earnings ESP Filter.
Zacks Rank: QNST currently carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Other Stocks With the Favorable Combination
Here are some other stocks worth considering, as our model shows that these also have the right combination of elements to beat on earnings this reporting cycle.
AMETEK, Inc. AME has an Earnings ESP of +0.37% and sports a Zacks Rank #1 at present. AMETEK is set to report third-quarter 2026 results on Nov. 3.
The Zacks Consensus Estimate for AMETEK’s third-quarter earnings is pegged at $2.12 per share, up by a penny over the past 30 days and 12.2% from the year-ago quarter’s reported figure.
ON Semiconductor Corporation ON has an Earnings ESP of +5.68% and carries a Zacks Rank #3 at present. ON Semiconductor is set to report third-quarter 2026 results on Nov. 2.
The Zacks Consensus Estimate for ON Semiconductor’s third-quarter 2026 earnings is pegged at 88 cents per share, up by a penny over the past 30 days and 39.9% from the year-ago quarter’s reported figure.
Advanced Micro Devices, Inc. AMD has an Earnings ESP of +2.55% and a Zacks Rank #3 at present. Advanced Micro Devices is slated to report third-quarter 2026 results on Nov. 3.
The Zacks Consensus Estimate for Advanced Micro Devices’ third-quarter 2026 earnings is pegged at $1.94 per share, up by a couple of cents over the past 30 days, suggesting an increase of 61.7% from the year-ago quarter’s reported figure.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
QuinStreet, Inc. (QNST): Free Stock Analysis Report
Advanced Micro Devices, Inc. (AMD): Free Stock Analysis Report
AMETEK, Inc. (AME): Free Stock Analysis Report
ON Semiconductor Corporation (ON): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).