

Navitas Semiconductor NVTS is scheduled to report its third-quarter 2026 results on Nov. 3, 2026.
Navitas Semiconductor anticipates revenues of $13.5 million (+/- $0.5 million) for the third quarter of 2026. The Zacks Consensus Estimate for second-quarter revenues is pegged at $13.48 million, suggesting a year-over-year increase of 33.3%.
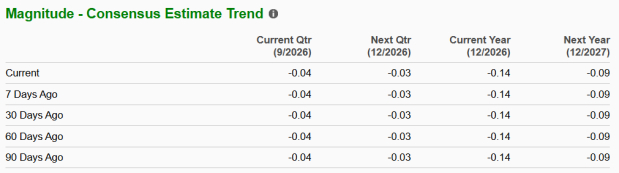
The consensus mark for loss is pegged at 4 cents per share for the third quarter of 2026, unchanged over the past 30 days. NVTS reported a loss of 5 cents per share in the year-ago quarter.
Image Source: Zacks Investment Research
Navitas Semiconductor’s bottom-line results have matched the Zacks Consensus Estimate in three of the trailing four quarters, while beating once, with the average surprise being 5%.
Navitas Semiconductor Corporation Price and EPS Surprise
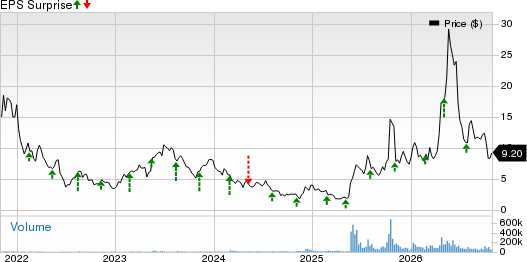
Navitas Semiconductor Corporation price-eps-surprise | Navitas Semiconductor Corporation Quote
Earnings Whispers for NVTS
Our proven model does not conclusively predict an earnings beat for Navitas Semiconductor this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here.
Navitas Semiconductor has an Earnings ESP of 0.00% and carries a Zacks Rank #3 at present. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter. You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Likely to Influence NVTS’ Q3 Results
Navitas Semiconductor is a well-known provider of power semiconductors, driven by its gallium nitride (GaN) business, under GaNFast, GaNSafe and GaNSense brands, along with silicon carbide (SiC) devices. Navitas Semiconductor is expected to have benefited from the growing demand for power that is served by the company’s GaN and SiC technologies.
Navitas Semiconductor is shifting its focus toward high-power markets, such as artificial intelligence (AI) data centers, performance computing, energy and grid infrastructure, and industrial electrification. Its GaN and SiC chips are well-suited for new high-voltage systems that need more efficient power use. This strategic move aligns with the company’s Navitas 2.0 strategy, under which the company is reallocating resources toward high-power markets, pruning lower-margin mobile business and working more closely with hyperscalers, graphics processing unit vendors and system OEMs.
Navitas Semiconductor’s inclusion in NVIDIA’s new 800-volt AI factory ecosystem is an important step. The new architecture shifts data center power distribution from traditional AC/DC stages to a high-voltage DC approach that requires faster, more efficient power electronics. This creates an opening for Navitas Semiconductor’s GaN and high-voltage SiC technologies, both of which are now part of the NVIDIA-led ecosystem.
Navitas Semiconductor remains one of the few companies offering both GaN and SiC solutions across the power chain, from the grid to the data center rack. During the second quarter of 2026, management noted increasing adoption of GaN in high-end computing applications, including chargers above 200 watts and a recently launched 1,600-watt platform for high-performance gaming systems. As AI infrastructure spending continues to grow, Navitas Semiconductor remains well-positioned to benefit from higher demand for its GaN and SiC products. The above-mentioned factors are likely to have contributed to the company’s prospects in the to-be-reported quarter.
However, NVTS’ Navitas 2.0 strategy involves moving away from mobile charging and consumer electronics toward higher-power AI and industrial markets. While this may improve long-term growth, it also introduces meaningful near-term revenue volatility. The company is effectively walking away from markets where it already had product traction and revenue history in exchange for newer markets with longer design cycles and more demanding qualification requirements. This transition could create revenue volatility over the next several quarters.
NVTS Price Performance & Stock Valuation
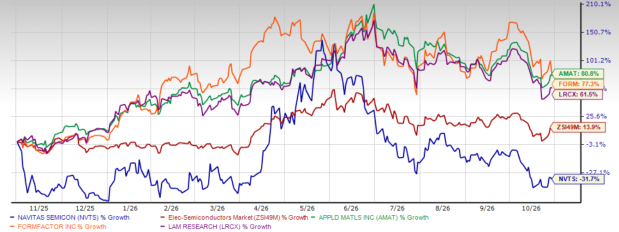
Navitas Semiconductor shares have plunged 31.7% over the past year, underperforming the Zacks Electronics - Semiconductors industry’s growth of 13.9%. Compared to other major players in the semiconductor space, NVTS has underperformed Lam Research LRCX, FormFactor FORM and Applied Materials AMAT. Over the past year, shares of Lam Research, FormFactor and Applied Materials have rallied 61.5%, 77.3% and 80.8%, respectively.
One-Year Price Return Performance
Image Source: Zacks Investment Research
Navitas Semiconductor is currently trading at a higher price-to-sales (P/S) multiple compared with the industry. NVTS’ forward 12-month P/S ratio sits at 36.67X, significantly higher than the industry’s forward 12-month P/S ratio of 4.50X.
NVTS Forward 12-Month P/S Ratio
Image Source: Zacks Investment Research
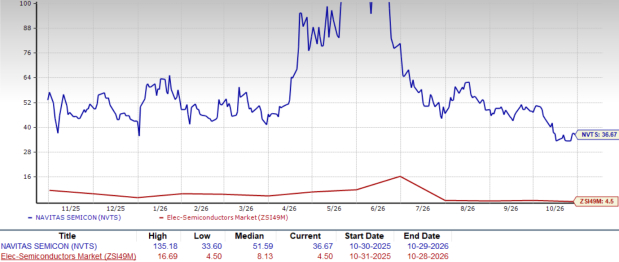
Navitas Semiconductor stock also trades at a higher P/S multiple compared with other industry peers, including Lam Research, FormFactor and Applied Materials. At present, Lam Research, FormFactor and Applied Materials have P/S multiples of 8.61X, 7.34X and 6.46X, respectively.
Investment Consideration for Navitas Semiconductor
Navitas Semiconductor is in a good position to benefit from the fast growth of AI data centers. Its GaN and SiC chips are well-suited for new high-voltage systems that need more efficient power use. Navitas Semiconductor’s inclusion in NVIDIA’s next-generation 800-volt DC “AI factory” positions NVTS in a large, fast-growing market where power design is becoming a priority, which bodes well for the company's prospects.
However, NVTS faces near-term challenges due to weakness in its China business, where the company has decided to prune its low-margin mobile business and low-end consumer business, which have not yet been fully offset by growth in high-power segments. These are likely to have hurt the company's prospects in the near term.
Conclusion: Hold Navitas Semiconductor Stock Right Now
Navitas Semiconductor is well-positioned to ride on the long-term growth in the AI data center market. The company’s GaN and high-voltage SiC products now play a role in NVIDIA’s new 800-volt power setup, which shows that the technology is relevant and in demand. If the company executes well, it could see better margins, a stronger product mix and a clearer path to stable long-term growth.
However, near-term risks from its decision to deprioritize its lower-margin mobile and consumer business, along with the company’s high valuation, warrant a cautious approach to the stock.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Navitas Semiconductor Corporation (NVTS): Free Stock Analysis Report
Lam Research Corporation (LRCX): Free Stock Analysis Report
FormFactor, Inc. (FORM): Free Stock Analysis Report
Applied Materials, Inc. (AMAT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).