

The Home Depot, Inc. HD has been benefiting from resilient demand for smaller repair and maintenance projects, even as consumer uncertainty, elevated borrowing costs and housing affordability challenges constrain spending on larger discretionary renovations. The company's second-quarter fiscal 2026 performance highlighted broad-based customer engagement, supported by strength in core home improvement categories and improving digital capabilities.
In the second quarter of fiscal 2026, comparable sales (comps) increased 1.7%, while U.S. comps advanced 1.3%. Notably, 13 of its 16 merchandising departments reported positive comps, including electrical, hardware, plumbing, paint, storage and building materials. Management highlighted particularly strong performance across core, nonseasonal categories, indicating sustained consumer spending on essential home maintenance and smaller improvement projects.
However, underlying demand remains uneven. Comparable average ticket increased 2.8%, while transactions declined 1%, suggesting sales growth was driven primarily by higher spending per transaction rather than increased customer traffic. Although big-ticket transactions exceeding $1,000 rose 2.4%, larger discretionary projects continued to face pressure.
Home Depot's strategic investments are reinforcing customer engagement. Digital sales increased 11%, marking the fifth consecutive quarter of double-digit growth. Faster fulfillment, improved product availability and expanded delivery capabilities are supporting conversion and customer convenience.
Management reaffirmed its fiscal 2026 comps outlook of flat to 2% growth. While smaller projects and Pro demand should sustain underlying sales momentum, a meaningful recovery in larger renovation spending remains dependent on improving housing conditions and consumer confidence.
Is Small-Project Demand Also Fueling Sales Growth at LOW & WSM?
With smaller repair and maintenance projects supporting Home Depot's sales growth amid subdued demand for larger renovations, the question is whether Lowe's Companies Inc. LOW and Williams-Sonoma Inc. WSM are witnessing similar spending trends.
Lowe's continues to benefit from resilient repair and maintenance demand as homeowners defer larger discretionary renovations. Second-quarter fiscal 2026 comps increased 0.2%, with nine of 13 merchandising divisions posting positive comps. Strength in plumbing, electrical, lumber, paint and kitchen and bath supported performance. Small and medium-sized Pro customers remained key growth drivers. However, cautious DIY spending and declining transactions constrained momentum, prompting management to project roughly flat fiscal 2026 comps.
Williams-Sonoma has been benefiting from demand for home refreshes and project-related purchases despite a stagnant housing market. Second-quarter fiscal 2026 comparable revenues increased 6.2% year over year, supported by strength in furniture and non-furniture categories. Rejuvenation delivered double-digit growth, driven by cabinet hardware, bath and lighting. Product innovation, collaborations and digital improvements further supported sales. Management raised its fiscal 2026 comparable-revenue growth outlook to 4-6.5%, reflecting sustained business momentum.
HD’s Price Performance, Valuation & Estimates
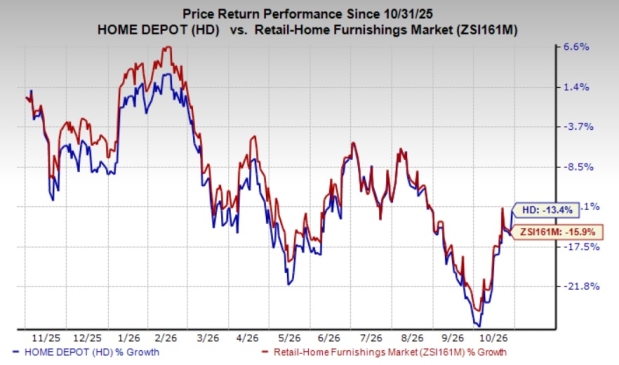
Shares of Home Depot have lost 13.4% in the past year compared with the industry’s decline of 15.9%.
Image Source: Zacks Investment Research
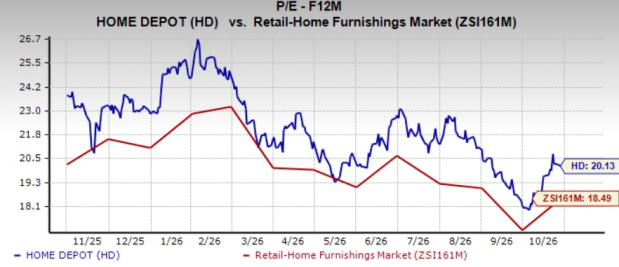
From a valuation standpoint, HD trades at a forward price-to-earnings ratio of 20.13X compared with the industry’s average of 18.49X.
Image Source: Zacks Investment Research
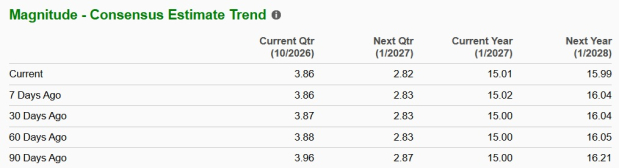
The Zacks Consensus Estimate for HD’s fiscal 2026 and 2027 EPS implies year-over-year growth of 2.2% and 6.6%, respectively. The company’s EPS estimate for fiscal 2026 has moved down by a penny in the past seven days. Meanwhile, the consensus estimate for fiscal 2027 EPS has moved down 0.3% in the past seven days.
Image Source: Zacks Investment Research
Home Depot currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
The Home Depot, Inc. (HD): Free Stock Analysis Report
Lowe's Companies, Inc. (LOW): Free Stock Analysis Report
Williams-Sonoma, Inc. (WSM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).