

FormFactor FORM and Cohu COHU are semiconductor testing equipment providers benefiting from accelerating artificial intelligence (AI) infrastructure investments, increasing semiconductor complexity, growing demand for high-bandwidth memory (HBM) and expanding adoption of advanced packaging technologies. However, their core offerings differ significantly. FormFactor specializes in advanced wafer-level probe cards, MEMS technologies and photonics testing solutions, serving foundry, logic and memory manufacturers. In contrast, Cohu focuses on automated test handlers, advanced thermal management, semiconductor inspection, test interfaces and automated test equipment for high-performance processors and power devices.
FORM or COHU, which is a better buy currently?
The Case for FORM Stock
FormFactor is benefiting from accelerating demand for semiconductor testing solutions, driven by increasing AI infrastructure investments, advanced packaging complexity and growing adoption of high-bandwidth memory (HBM). The company’s leadership in advanced MEMS probe cards positions it to capitalize on rising testing requirements for GPUs, custom ASICs, data center CPUs and advanced memory devices.
FormFactor's expanding presence in advanced logic and memory testing strengthens its long-term growth prospects. Foundry and Logic revenues increased 10% sequentially to $134 million in the third quarter of 2026, supported by growing demand across GPUs, custom ASICs, networking and data center processors. The company shipped multimillion-dollar volumes of probe cards for a leading foundry's GPU design, positioning it for additional market share gains in 2027. Meanwhile, DRAM probe card revenues remained near record levels at $84.9 million, supported by demand for HBM and DDR5. FormFactor's expanding collaboration with Teradyne, alongside its existing partnership with Advantest, strengthens its position in the semiconductor testing ecosystem. FormFactor offers broader exposure to wafer-level testing across advanced logic and memory architectures.
FormFactor's growing presence in silicon photonics and co-packaged optics (CPO) provides another important growth catalyst. Systems segment revenues surged 23% sequentially to $59.5 million in the third quarter, supported by accelerating adoption of TRITON photonics testing systems. The company raised its 2026 TRITON revenue expectation to more than $30 million, compared with its initial projection of $10-$20 million. Its Keystone Photonics acquisition strengthens optical probing capabilities across CPO, near-package optics and pluggable optical devices. FormFactor focuses on wafer-level photonics testing to establish known-good photonic integrated circuits before advanced packaging.
FormFactor is also strengthening its manufacturing capacity to capitalize on increasing demand for advanced semiconductor testing. Its new Farmers Branch facility is expected to provide approximately $400 million in annual probe card production capacity by the end of 2027, supporting higher volumes across GPUs, custom ASICs and advanced memory applications. The company expects fourth-quarter revenues of $285 million, plus or minus $10 million, and non-GAAP earnings of 95 cents per share, plus or minus 9 cents. However, the midpoint implies modest sequential revenue growth and lower earnings compared with the third quarter.
The Case for COHU Stock
Cohu is benefiting from accelerating demand for high-performance computing (HPC) semiconductor testing, growing adoption of advanced thermal handlers and improving semiconductor test equipment utilization. The company's Eclipse platform is gaining traction among AI processor manufacturers seeking precise thermal management for increasingly powerful CPUs, GPUs, networking chips and custom accelerators. Cohu's HPC opportunity pipeline expanded to approximately $1 billion, reflecting improving customer engagement and rising demand for advanced thermal testing solutions. Cohu's strong bookings momentum and accelerating customer qualifications offer significant growth potential.
Cohu's expanding AI infrastructure footprint is strengthening its competitive position in semiconductor testing. The company raised its 2026 HPC revenue outlook to approximately $120 million, supported by accelerating adoption of Eclipse thermal handlers across data center processors and networking applications. Its qualified annual revenue opportunities reached approximately $230 million, while another $440 million remained in active qualification. Seven additional customer programs represent approximately $340 million in potential annual systems revenues, subject to successful qualification and production ramps. Cohu is expanding manufacturing capacity in Malaysia and the Philippines, targeting approximately three times as many Eclipse handler shipments in 2027 as in 2026.
Cohu’s diversified product portfolio provides additional opportunities beyond high-performance computing. Its Neon inspection systems are gaining traction in HBM3 and HBM4 applications, with growing demand for advanced packaging inspection and subsurface microcrack detection. The company is also expanding Diamondx automated test equipment into AI power management applications, including high-voltage and high-current semiconductor devices. Meanwhile, interface solutions are benefiting from new hyperscaler customer wins and emerging CPO testing requirements.
Cohu’s improving financial outlook reflects accelerating AI-related demand and a recovery in its traditional semiconductor testing markets. The company expects fourth-quarter revenues of approximately $178 million, plus or minus $7 million, representing 46% year-over-year growth at the midpoint. However, the company faces execution risks associated with customer qualifications, supply-chain constraints, higher component costs and manufacturing capacity expansion.
FORM’s Earnings Estimate Revisions Positive, COHU’s Go South
The Zacks Consensus Estimate for FORM’s 2026 earnings is pegged at $3.11 per share, up by 6 cents over the past 30 days, indicating a 139.2% increase over fiscal 2025’s reported figure.
FormFactor, Inc. Price and Consensus
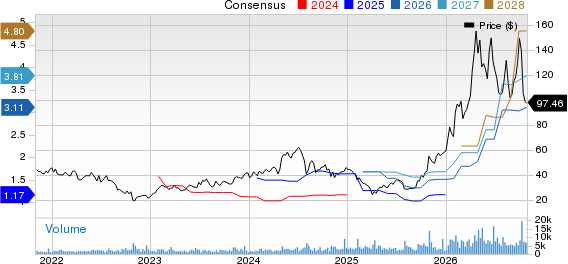
FormFactor, Inc. price-consensus-chart | FormFactor, Inc. Quote
The consensus mark for COHU’s 2026 earnings has declined by a nickel to 92 cents per share over the past 30 days. The company reported a loss of 22 cents per share in 2025.
Cohu, Inc. Price and Consensus
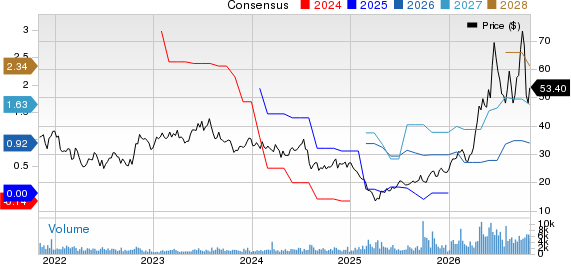
Cohu, Inc. price-consensus-chart | Cohu, Inc. Quote
FORM Shares Underperform Cohu
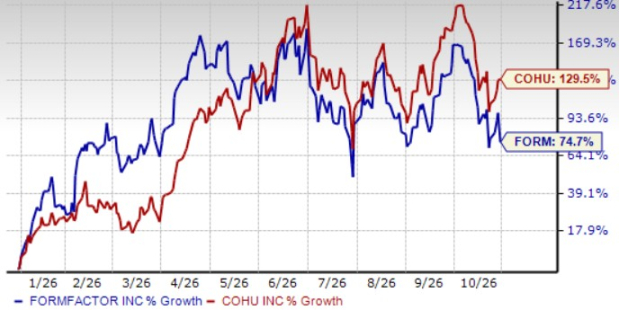
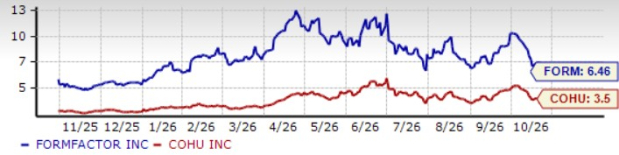
Year to date (YTD), FormFactor shares have returned 74.7%, underperforming Cohu’s appreciation of 129.5%.
FORM and COHU Stock’s Price Performance
Image Source: Zacks Investment Research
In terms of forward 12-month Price/Sales (P/S), FORM shares are trading at 6.46X, higher than Cohu’s 3.50X.
FormFactor and Cohu have a Value Score of F each, suggesting a stretched valuation for both stocks.
FORM and COHU Valuation
Image Source: Zacks Investment Research
Conclusion
FormFactor currently has an edge over Cohu in profitability, established AI-related revenue streams and cash generation. The company’s leadership in advanced probe cards, HBM testing and silicon photonics, coupled with manufacturing expansion and strategic partnerships, provides a strong foundation for sustained growth.
Currently, FormFactor sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Cohu has a Zacks Rank #4 (Sell), which implies that investors should avoid the stock right now.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
FormFactor, Inc. (FORM): Free Stock Analysis Report
Cohu, Inc. (COHU): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).